To say it’s too hard to predict this on my own is an obvious truth. Instead, we stay with our North Star: when insiders make big bets on their own company’s stock, they may just know something.
The current market environment is characterized by a significant rotation out of the technology sector, fueled by both a “blue wave” political climate and cooling sentiment toward the aggressive AI capital expenditure cycle. Legislative scrutiny regarding data center construction is mounting, creating potential headwinds for hyperscalers. While these regulatory pressures might slow the pace of growth, they also force a necessary conversation about the sustainability of massive infrastructure expansion.
We are left to wonder if the race to build compute capacity will hit a plateau as developers reconcile the physical constraints of data centers with the long-term potential of evolving technologies like quantum computing and continued miniaturization under Moore’s Law. Whether this environment serves as a temporary speed bump or a structural pivot for the industry, our focus remains on individual conviction. Delve into this week’s analysis; I believe you will find some gems among these recent insider transactions.
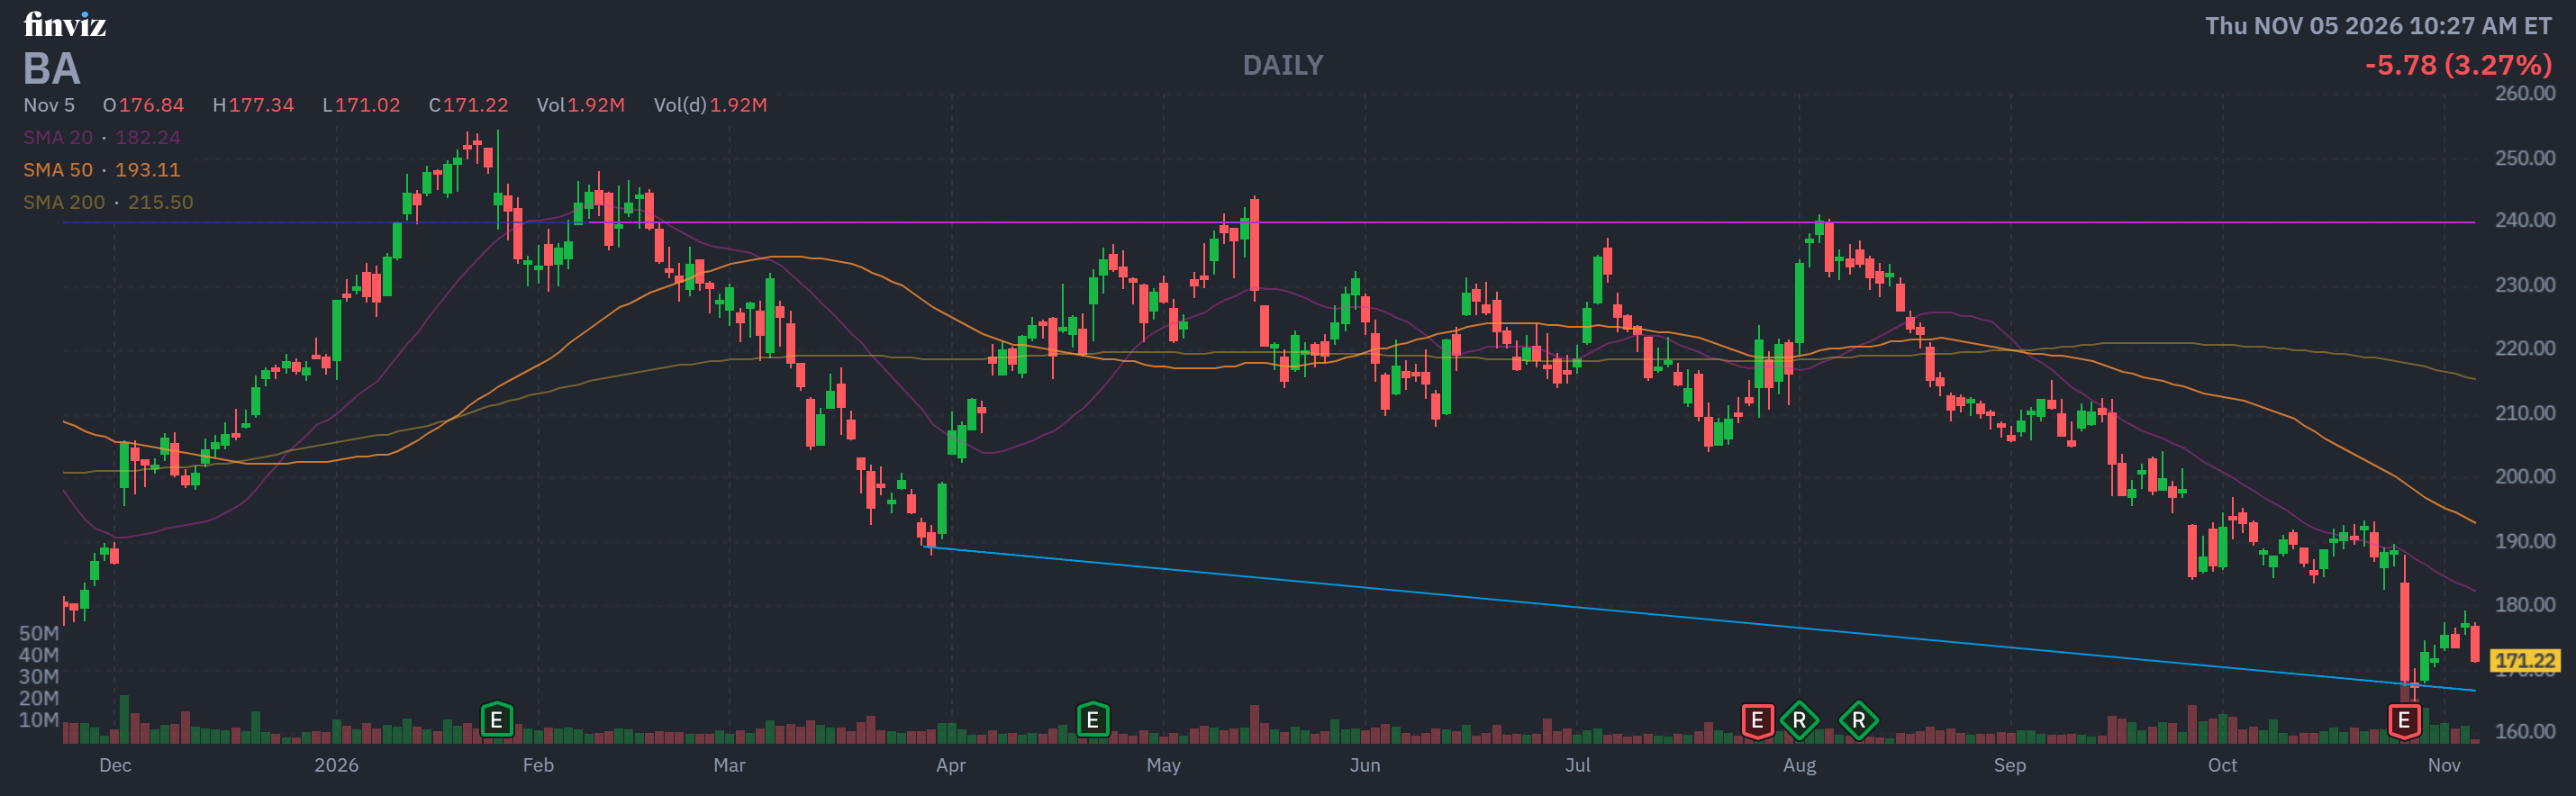
Name: Steven M. Mollenkopf
Position: Director
Transaction Date: 10-30-2026 Shares Bought: 2,950 shares an average price paid of $173.03 for Cost: $510,427
Name: Mortimer J. Buckley
Position: Director
Transaction Date: 10-30-2026 Shares Bought: 5,820 shares an average price paid of $171.55 for Cost: $998,421
Company: Boeing Co. (BA)
The Boeing Company is a leading aerospace and defense company that designs, manufactures, and services commercial airplanes, military aircraft, satellites, and space systems. Commercial Airplanes, Defense, Space & Security, and Global Services are the company’s segments, which provide goods and services to airlines, governments, and defense customers around the world. Boeing is well-known for its aircraft series, which include the 737, 777, and 787, as well as advanced defense and space technology. The corporation is a prominent player in worldwide aviation and aerospace innovation. Boeing was founded in 1916 and is headquartered in Arlington, Virginia.
Steven M. Mollenkopf has served as a Director of The Boeing Company since April 2020, when he joined the company’s Board of Directors. He was elected Independent Chair of the Board in March 2024. He did not join Boeing as an employee; his association began through his Board appointment. Previously, he spent more than 25 years at Qualcomm, where he held several leadership positions, including President and Chief Operating Officer before serving as CEO from 2014 to 2021. He currently serves as a Senior Advisor at Consello Group and as a director of Dell Technologies. He holds a Bachelor of Science degree in Electrical Engineering from Virginia Tech and a Master of Science degree in Electrical Engineering from the University of Michigan.
Mortimer J. Buckley has been a Director at Boeing Co. since January 1, 2025, after being elected to the company’s board in November 2024. He joined the board with over 30 years of leadership experience in global investment management, most notably at The Vanguard Group, where he was CEO from 2018 to 2024 and Chairman from 2019 to 2024. Buckley joins Boeing’s board of directors and serves on the Finance, Governance, and Public Policy committees. He has expertise in financial oversight, digital technologies, cybersecurity, and corporate governance. He received a BA in Economics from Harvard University and an MBA from Harvard Business School.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite lands at -1.9 (mixed/neutral, leaning bearish), built on a bullish analyst consensus (+1) and bullish insider buying (+1), dragged down by bearish cash flow quality (-1), an expensive PEG ratio (-1), negative market direction (-1), and cautious management/catalyst commentary (-0.6 and -0.3). This stock is a show-me story: the backlog and the duopoly moat are real, but the cash isn’t showing up on the cash flow statement and the production timeline keeps sliding to the right. Two directors buying in November is a genuine vote of confidence, and I wouldn’t ignore it, but a DCF landing right around the current price tells you there’s no obvious margin of safety here, you’re paying fair value for a recovery that’s still proving itself quarter by quarter. Call this a hold for patient believers in the long-term duopoly thesis, not a stock I’d chase at $173 waiting for 2027 catalysts to arrive on schedule, Boeing’s schedule has a well-documented habit of slipping.
This is educational, not advice.
Name: Brian A. Deck
Position: Director
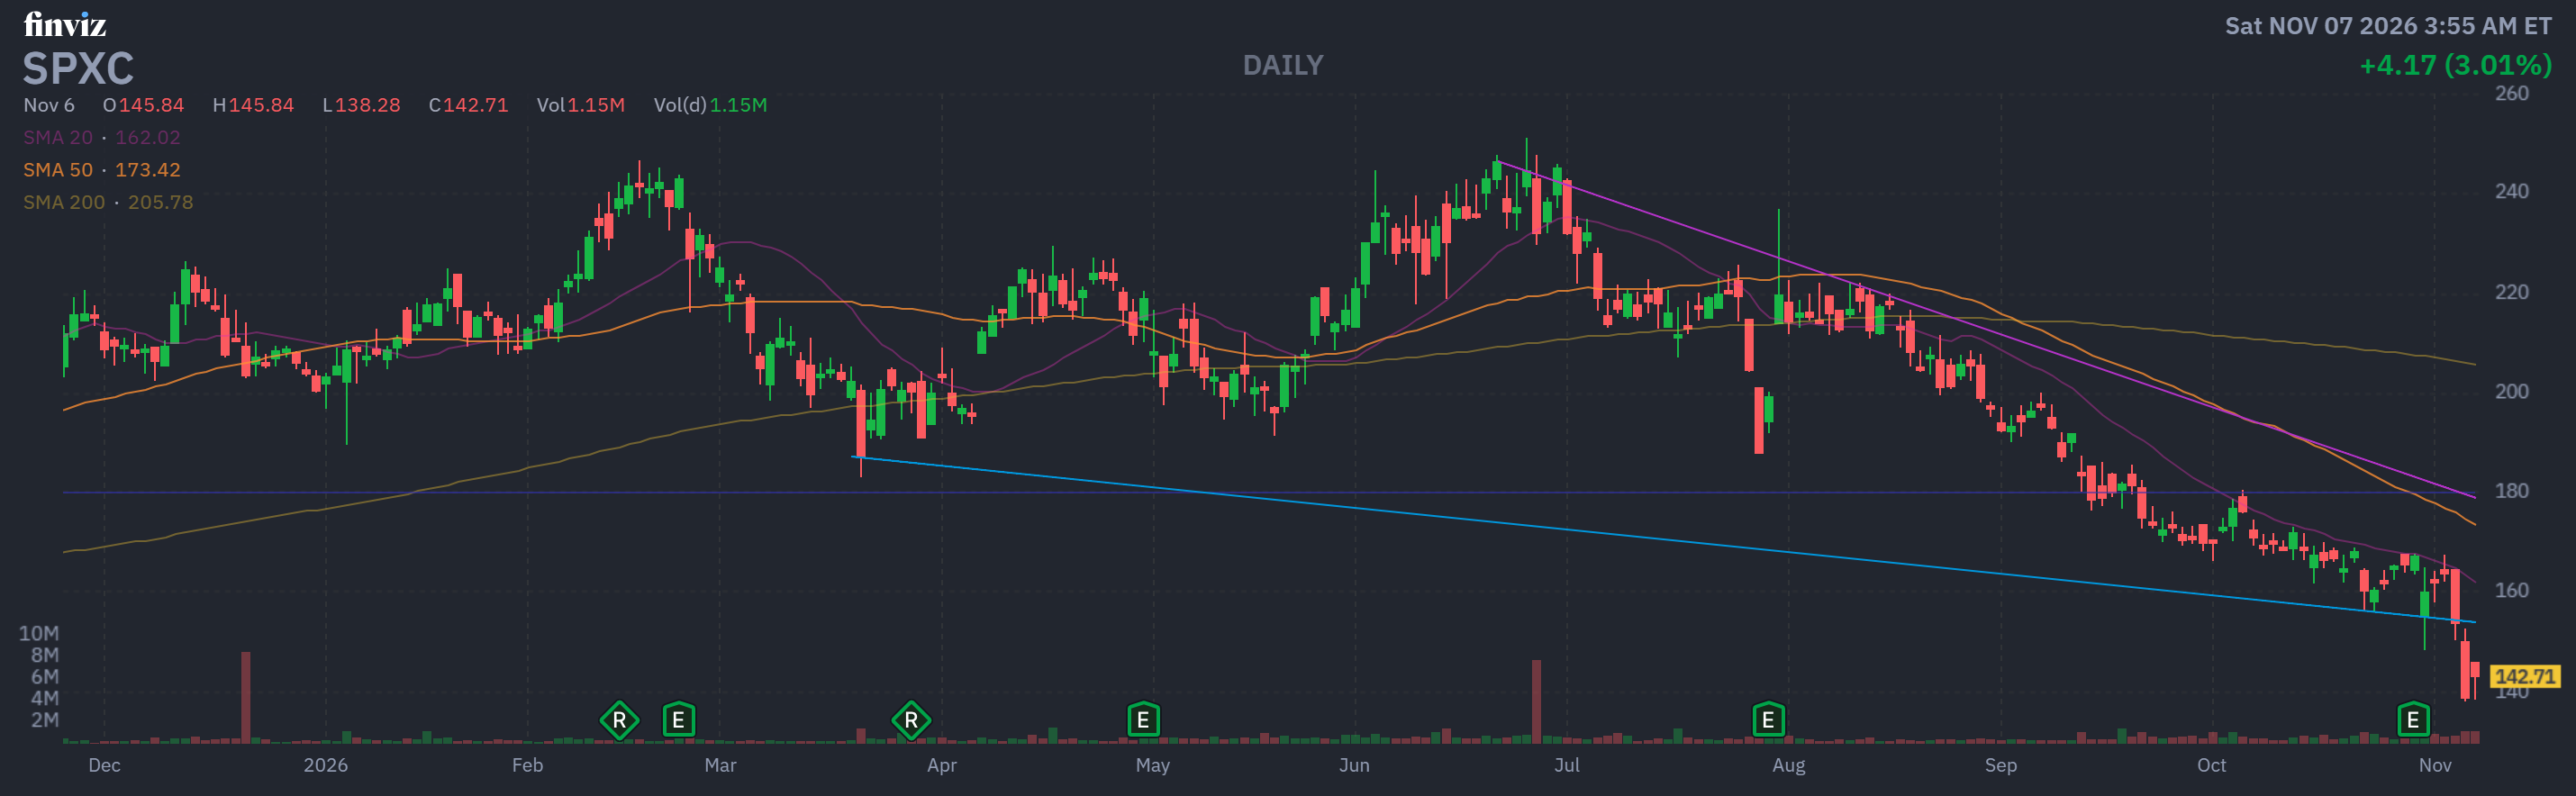
Transaction Date: 11-03-2026 Shares Bought: 3,000 shares an average price paid of $164.34 for Cost: $493,020
Company: SPX Technologies Inc. (SPXC)
SPX Technologies, Inc. is an industrial technology company that supplies engineered solutions for the heating, ventilation, and air conditioning, detection, and measurement markets worldwide. The company operates through two segments: HVAC, and Detection and Measurement. Its HVAC segment designs, manufactures, installs, and services cooling systems, air movement and handling solutions, hydronic heating equipment, and electrical heating and ventilation products for residential, commercial, industrial, and institutional markets. Its Detection and Measurement segment offers underground pipe and cable locators, inspection and rehabilitation equipment, robotic systems, transportation systems, communication technologies, and marine and aviation navigation products. The company markets its products through independent representatives, distributors, retailers, and other channels. It was formerly known as SPX Corporation before changing its name to SPX Technologies, Inc. in August 2022. SPX Technologies, Inc. is headquartered in Charlotte, North Carolina.
Brian A. Deck joined SPX Technologies Inc. as an independent member of the Board of Directors on July 27, 2026. He also serves on the Board’s Audit and Governance & Sustainability Committees. He is currently the Chief Executive Officer of JBT Marel Corporation, a position he assumed in December 2020 when the company was known as John Bean Technologies Corporation. Previously, he served as JBT’s Executive Vice President and Chief Financial Officer from 2014 to 2020 and held financial leadership positions at National Material, Ryerson, General Electric, and Bank One. He holds a bachelor’s degree in Economics from the University of Illinois at Urbana-Champaign and an MBA from DePaul University.
Insomniac Hedge Fund Guy Opinion: Perfect 10 composite score: +3.7 (constructive, on the -10 to +10 scale), driven by a Strong Buy analyst consensus with 67.8% upside to target, a cheap PEG ratio of 0.78, solid cash flow, and real insider buying into weakness. The knock against it is near-term margin compression and a market that’s currently punishing anything tied to AI infrastructure spending.
On these numbers, the case leans bullish: this reads like a quality industrial getting unfairly lumped into “AI capex is a bubble” selling pressure while actually growing revenue at 20%-plus and generating real cash. The guidance trim was about cost inflation and growth pains, not demand destruction, and the backlog says the growth story has legs into 2027. That said, this isn’t a dog, but it also isn’t a free lunch, margin execution over the next two quarters will determine whether the current price is a gift or a warning sign. That call is yours to make with your advisor.
This is educational, not advice.
Name: Doug Black
Position: CEO
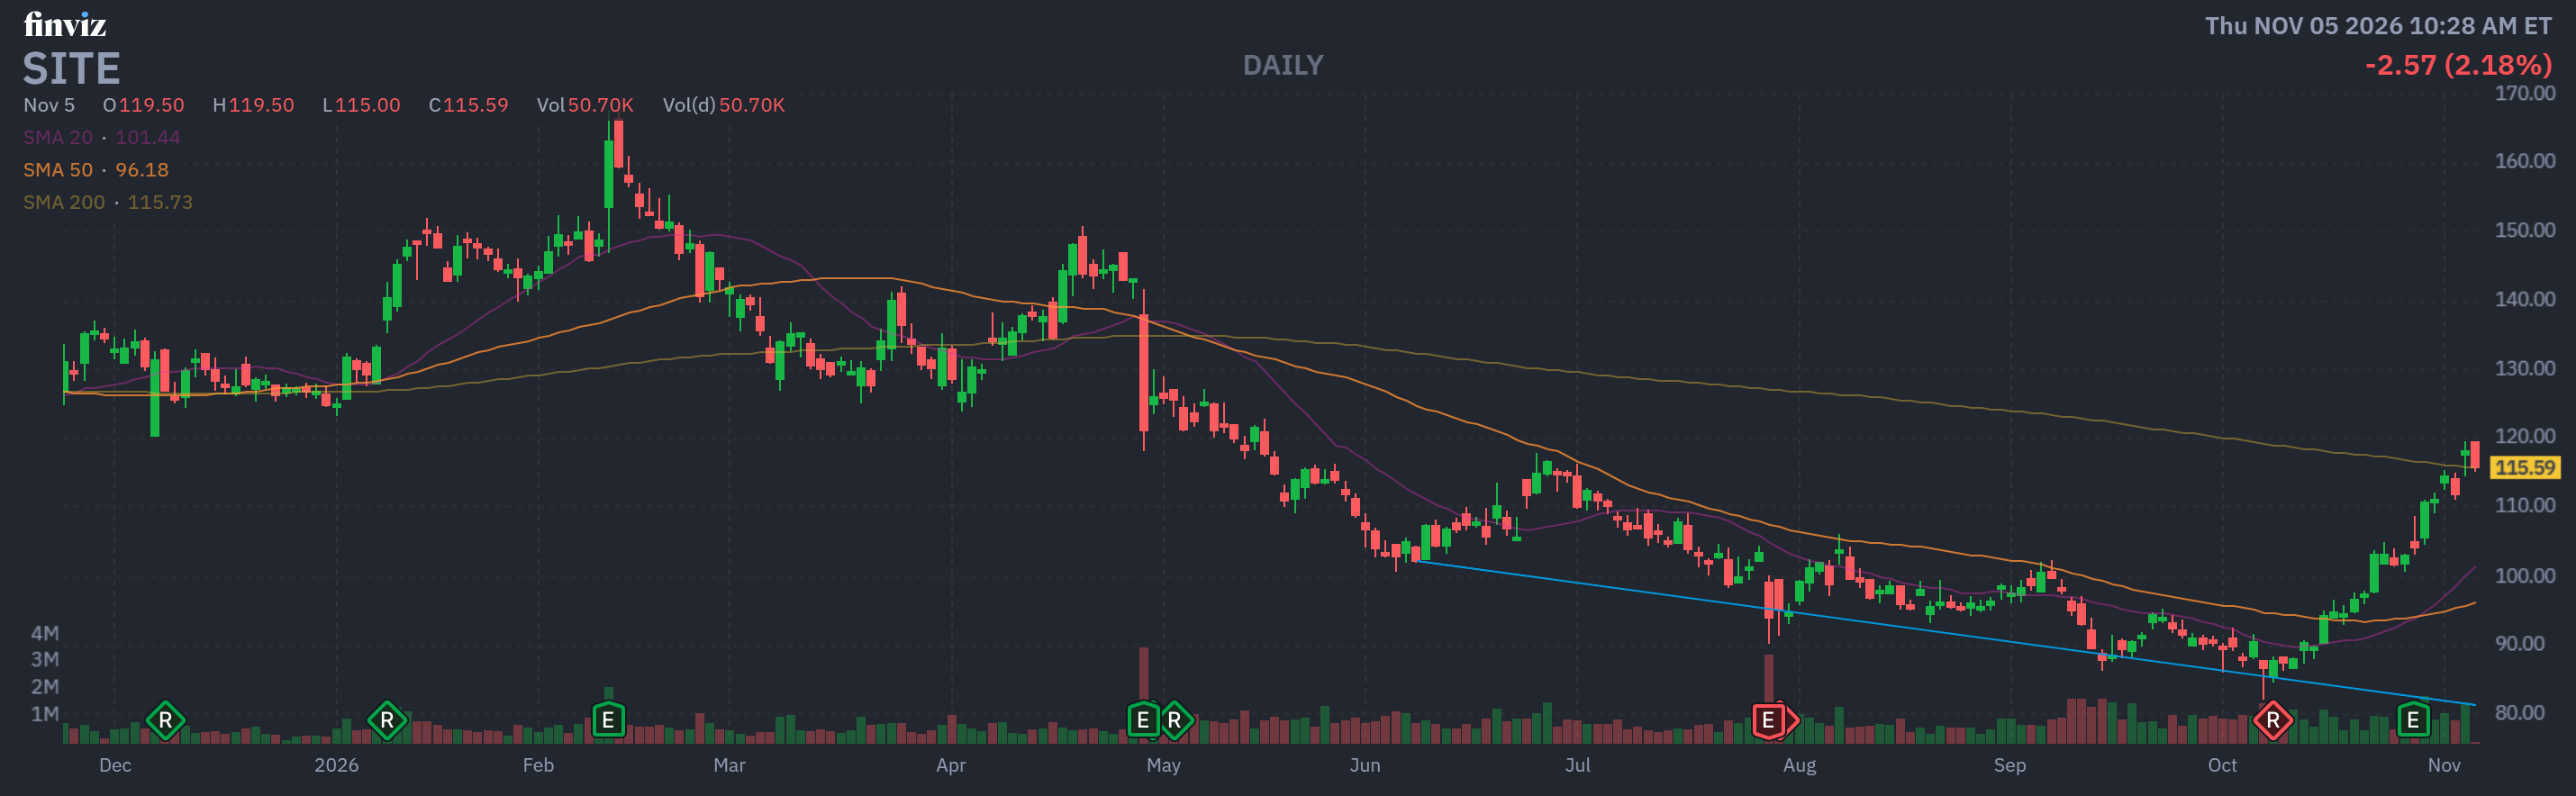
Transaction Date: 10-30-2026 Shares Bought: 9,100 shares an average price paid of $110.30 for Cost: $1,003,685
Company: SiteOne Landscape Supply Inc. (SITE)
SiteOne Landscape Supply, Inc. and its subsidiaries engage in the wholesale distribution of landscape goods in the United States and Canada. The company offers irrigation products such as controllers, valves, sprinkler heads, irrigation pipes, micro irrigation, and drip products; fertilizer, grass seed, and ice melt products; control products such as herbicides, fungicides, rodenticides, and other pesticides; hardscapes, which include pavers, natural stones, and blocks; and outdoor lighting products such as lighting fixtures, LED lamps, wires, transformers, and accessories. It markets its goods primarily to residential and commercial landscape professionals that specialize in the design, installation, and management of lawns, gardens, golf courses, and other outdoor spaces via a branch network and direct distribution. SiteOne Landscape Supply, Inc. was founded in 2001 and is based in Roswell, Georgia.
Doug Black has served as Chief Executive Officer of SiteOne Landscape Supply Inc. since April 2014, when he joined the company, and has also served as Chairman of the Board since June 2017. Before joining SiteOne, he spent 18 years at Oldcastle Inc., where he held several senior leadership roles, including President and Chief Operating Officer. Earlier in his career, Black worked at McKinsey & Company and served as a U.S. Army Engineer Officer. He holds an MBA from Duke University’s Fuqua School of Business and a B.S. in Mathematical Science/Civil Engineering from the U.S. Military Academy at West Point.
Insomniac Hedge Fund Guy Opinion: SiteOne is a well-run business in a cyclical downturn trading like a growth stock. The CEO is buying, cash conversion is strong, and customer diversification is excellent, but the DCF says fair value is closer to $95-$110 while the stock sits above $116, and organic volumes are shrinking while the company restructures to cut costs. Elevated short interest near 9-10% of float tells you the skeptics have done their homework too. This reads as a hold, not a chase: the long-term roll-up story is intact, but paying a growth multiple for a business posting negative organic volume is a bet on a residential construction recovery that hasn’t shown up yet.
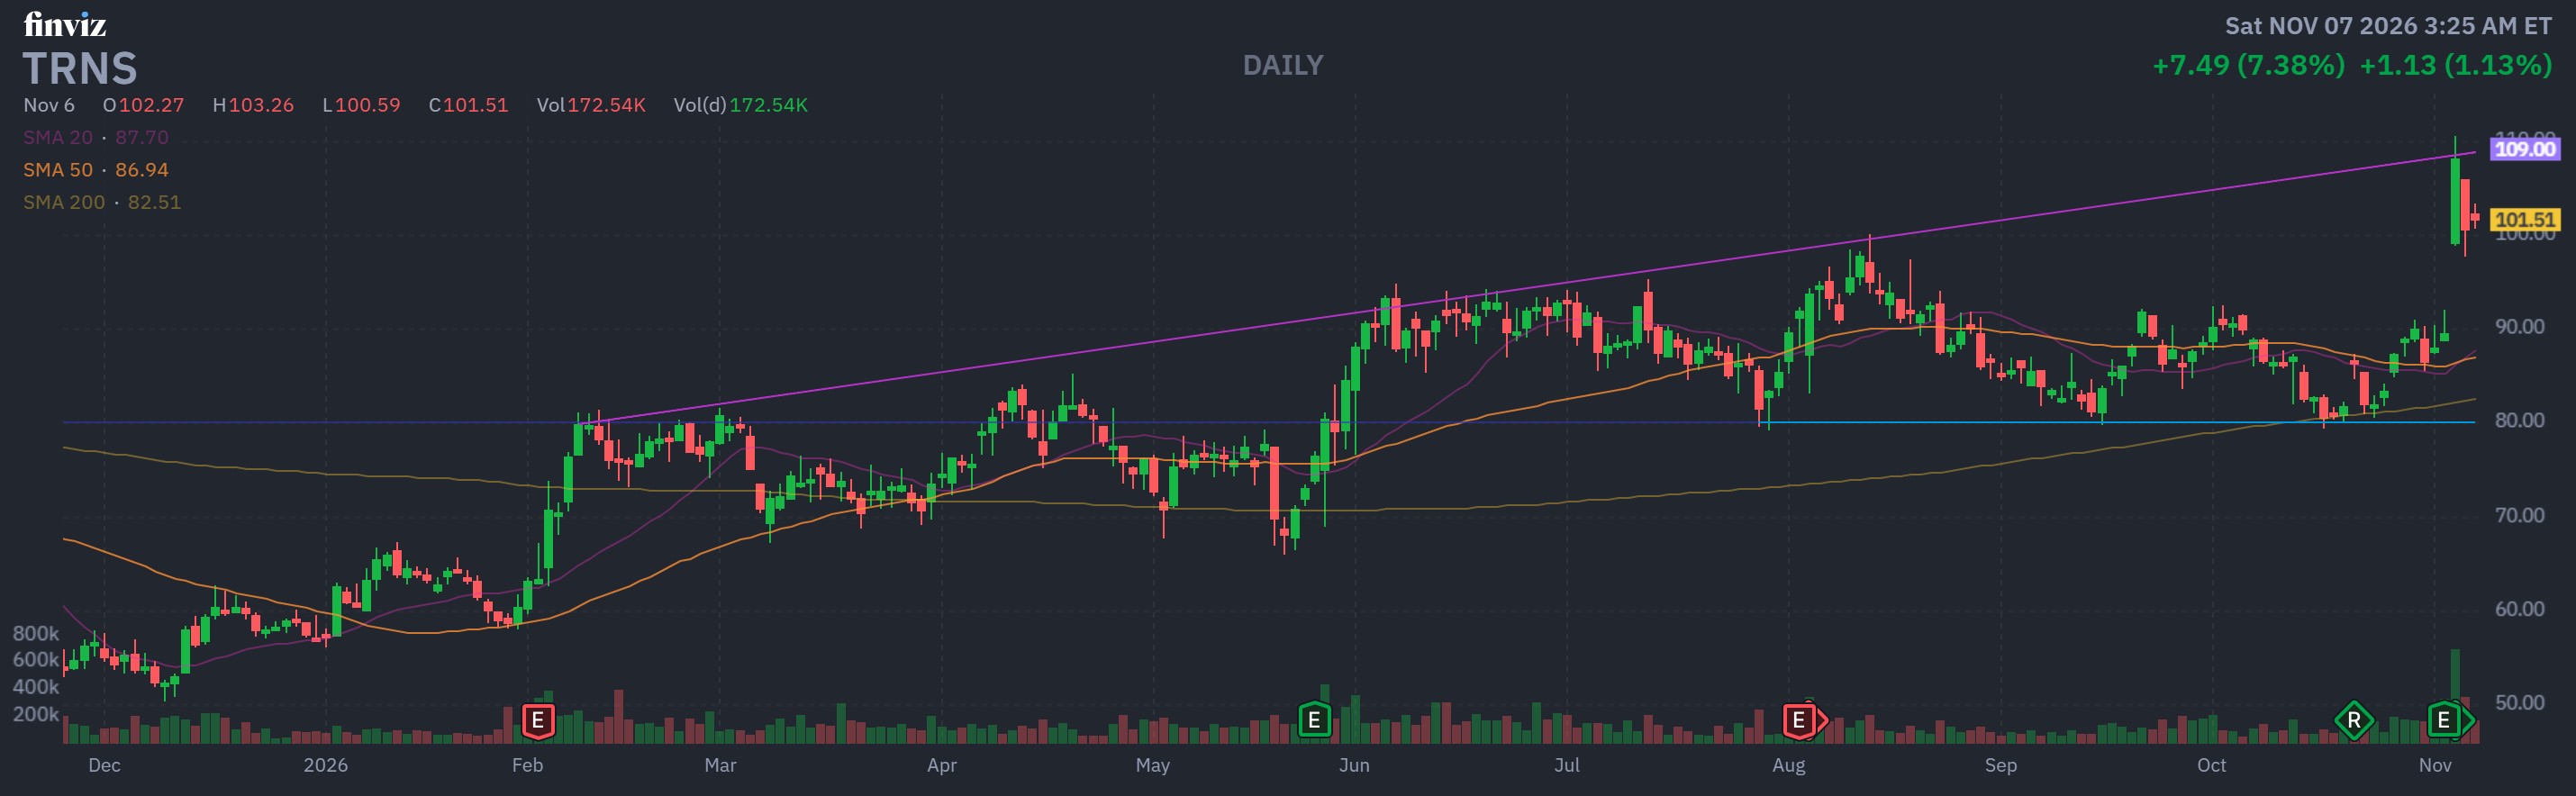
Name: Jaime A. Irick
Position: President and CEO
Transaction Date: 11-05-2026 Shares Bought: 2,275 shares an average price paid of $101 for Cost: $230,367
Company: Transcat Inc. (TRNS)
Transcat, Inc. is a provider of calibration and laboratory instrument services, as well as test and measurement equipment, across the United States, Canada, and internationally. The company operates through two segments: Service and Distribution. Its Service segment offers calibration, repair, inspection, analytical qualification, preventive maintenance, consulting, and regulatory compliance services. It also provides CalTrak, a proprietary document and asset management system, and an online customer portal for managing equipment records and service documentation. Its Distribution segment sells and rents test, measurement, and control instruments, along with equipment calibration, certification, kitting, and used equipment services. The company serves highly regulated industries, including pharmaceuticals, biotechnology, medical devices, aerospace, defense, manufacturing, energy, utilities, oil and gas, and healthcare. Transcat, Inc. was incorporated in 1964 and is headquartered in Rochester, New York.
Jaime A. Irick joined Transcat Inc. as President and Chief Executive Officer on March 29, 2026, and was appointed to the company’s Board of Directors on the same date. Before joining Transcat, he served as Chief Executive Officer of The Pittsburgh Paints Company and held senior leadership positions at PPG Industries, Brunswick Corporation, and General Electric. At GE, he held several executive roles, including President and CEO of GE Lighting Solutions/LED. He also served as a Field Artillery Officer in the U.S. Army. He holds a degree in Systems Engineering from the United States Military Academy at West Point and an MBA from Harvard Business School.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite reads +2.0 (Constructive), held back mainly by a bearish short-term chart signal and a soft market backdrop, but boosted by bullish analyst sentiment, insider buying, and strong cash flow. This is a real business with a real moat in a boring-but-necessary industry, growing double digits, throwing off cash, and just had its CEO buy stock with his own money. The problem is the price: at 185x-plus earnings and a DCF value well below the current quote, the market has already priced in years of flawless execution. I’d call this a quality compounder trading like a momentum stock, good company, expensive stock. The lean here is cautiously bullish on the business, neutral-to-cautious on the entry point: this is one to watch for a pullback toward the $85-$90 zone rather than chase at these levels.
Buyer beware, not advice.
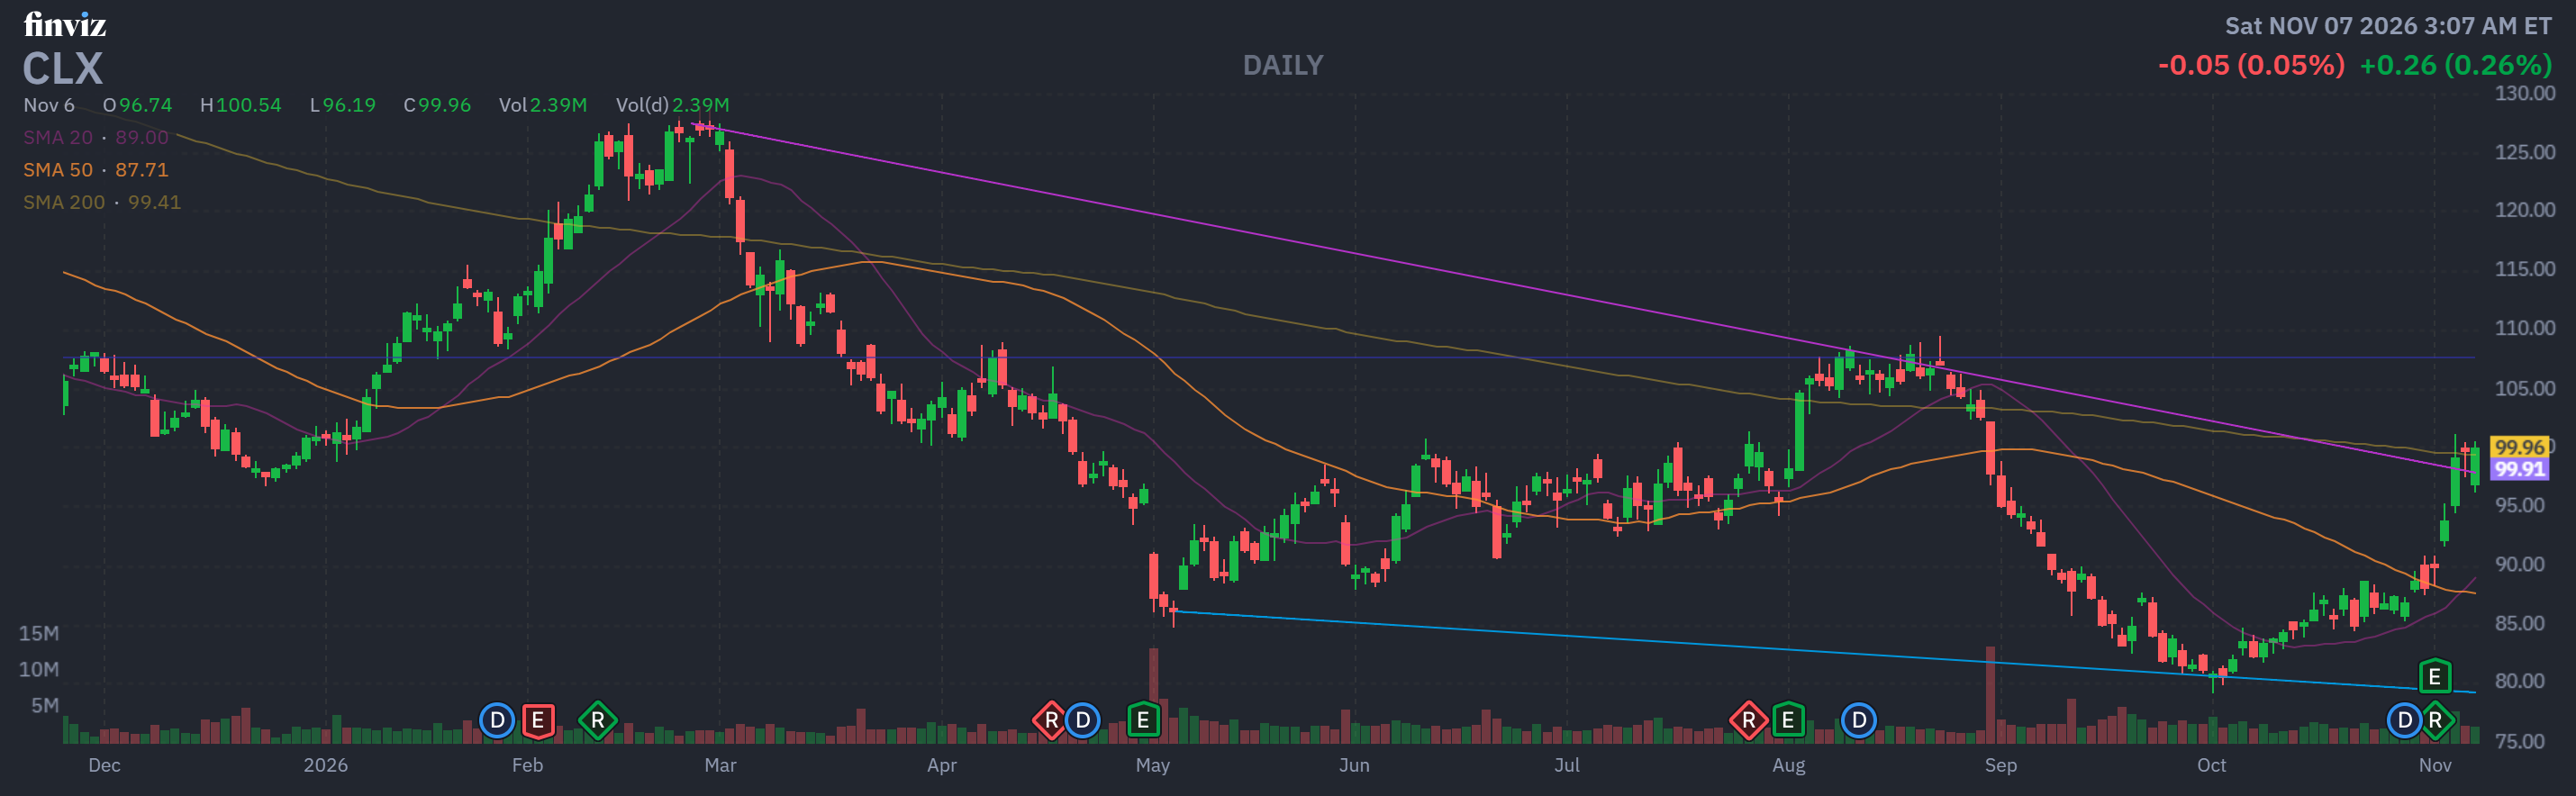
Name: Pierre R. Breber
Position: Director
Transaction Date: 11-04-2026 Shares Bought: 4,000 shares an average price paid of $100.06 for Cost: $400,251
Company: Clorox Co. (CLX)
The Clorox Company is a global manufacturer and marketer of consumer and professional products. The company operates through four segments: Health and Wellness, Household, Lifestyle, and International. Its product portfolio includes home care cleaning and disinfecting products, laundry additives, skin sanitization products, professional cleaning solutions, and food service products under brands such as Clorox, Pine-Sol, Liquid-Plumr, Formula 409, and CloroxPro. It also offers bags, wraps, cat litter, and grilling products under Glad, Fresh Step, and Kingsford, along with dressings, dips, sauces, water-filtration products, and natural personal care products under Hidden Valley, Brita, and Burt’s Bees. The company distributes its products through retail stores, wholesalers, distributors, and e-commerce channels worldwide. The Clorox Company was founded in 1913 and is headquartered in Oakland, California.
Pierre R. Breber has served as an independent Director on the Board of the Clorox Company since November 20, 2024, when he was elected to the Board. He did not join Clorox as an employee; his association began through his Board appointment. Previously, he spent more than three decades at Chevron Corporation, where he held several senior leadership positions, including Executive Vice President and Chief Financial Officer from 2019 to 2024. In May 2025, he was appointed Chair of Clorox’s Audit Committee. He also serves on the boards of Southwest Airlines and PACCAR. He holds bachelor’s and master’s degrees in Mechanical Engineering from the University of California, Berkeley, and an MBA from Cornell University.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite score on CLX comes in at +1.1 (mixed to neutral), a name with real positives (bullish cash flow, bullish insider buying, bullish sector tailwind) offset by a bearish analyst consensus and a bearish market-direction read. The earnings beat was genuine and GOJO is a real growth lever, but the stock has already rallied to capture that story, and my DCF pegs fair value below the current price. This is a hold, not a chase: a fine defensive name for a diversified portfolio, but not a compelling new buy at today’s price with a 17.98 P/E, declining year-over-year profitability, and short sellers circling at 8.53% of float. Let it prove the margin recovery before paying up further.
My take, not advice.
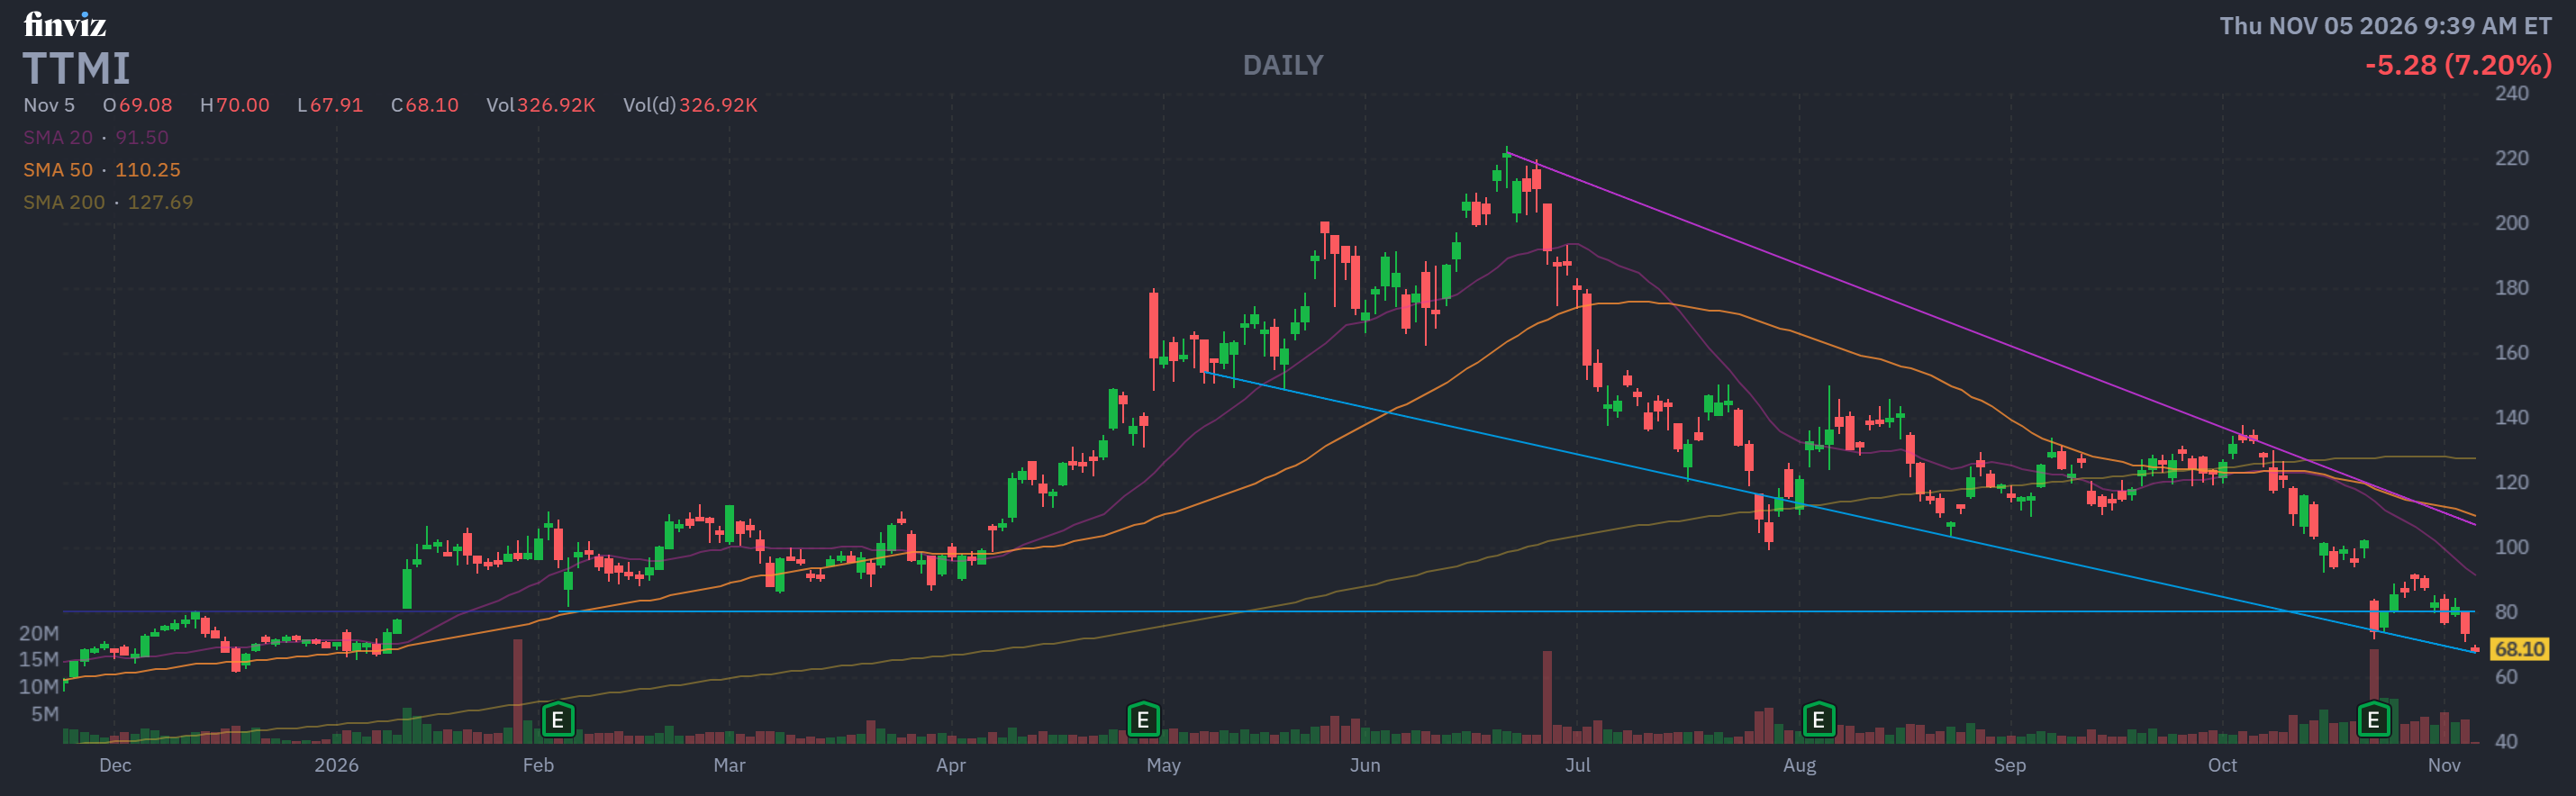
Name: Wajid Ali
Position: Director
Transaction Date: 10-28-2026 Shares Bought: 10,000 shares an average price paid of $90.25 for Cost: $902,461
Transaction Date: 11-05-2026 Shares Bought: 10,000 shares an average price paid of $63.15 for Cost: $631,541
Name: Edwin Roks
Position: President and CEO
Transaction Date: 10-28-2026 Shares Bought: 5,000 shares an average price paid of $88.07 for Cost: $440,350
Company: TTM Technologies Inc. (TTMI)
TTM Technologies, Inc. is a global technology company that specializes in mission systems, radio frequency components, microwave assemblies, printed circuit boards, and advanced substrates. It operates in three segments: aerospace and defense, commercial, and RF and specialty components. The company offers designed systems, RF and microwave assemblies, ceramic components, multi-chip modules, beamforming networks, and PCB design and testing services. Its technologies are useful for applications such as aircraft radar, marine surveillance, counter-drone systems, communications, air traffic management, and advanced air mobility. TTM serves the aerospace and defense, data centers, automotive, medical, industrial, and networking areas, serving OEMs, government agencies, electronics makers, and distributors globally. TTM Technologies, Inc., founded in 1978, is headquartered in Santa Ana, California.
Wajid Ali has served as a Director on the Board of TTM Technologies Inc. since May 9, 2024, when he was appointed as an independent director. He did not join TTM as an employee; his relationship with the company began through his Board appointment. He is the Chief Financial Officer of Lumentum Holdings Inc., overseeing its financial operations, and previously held senior finance leadership roles at Synaptics, Teledyne Technologies, and DALSA Corporation. He also held financial management positions at AMD and ATI. Ali holds a Bachelor of Arts and a Master of Arts in Economics from York University, an MBA from the Schulich School of Business at York University, and CPA and CMA designations.
Edwin Roks joined TTM Technologies Inc. as President and Chief Executive Officer on September 2, 2025, succeeding Thomas T. Edman. On the same date, he was also appointed to the company’s Board of Directors as a Class II director. Before joining TTM, Roks served as Chief Executive Officer of Teledyne Technologies from January 2024 to April 2025 and held several senior leadership positions there, including President of Teledyne Digital Imaging. Earlier in his career, he worked at Philips Research Laboratories and Philips Semiconductor. He holds a Ph.D. in Electronics and Semiconductor Physics from the University of Twente, a Master’s degree in Electrical Engineering from Eindhoven University of Technology, and completed an Executive MBA program at INSEAD.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite reads +3.3 (constructive), with bullish readings on analyst sentiment, insider activity, cash flow quality, and the PEG ratio, offset by bearish readings on market direction and sector outlook, both macro-driven, not company-specific. Strip away the sector-wide tech correction dragging the stock from $223 to the $66 range, and what’s left is a company putting up 60% revenue growth, expanding margins, a CEO buying his own stock, and a valuation that looks cheap on every growth-adjusted metric I can run. Light short interest confirms the bears aren’t convinced this is a broken story either. The case here leans bullish: this reads like a quality AI-infrastructure supplier caught in a sector-wide downdraft rather than a company with a cracked thesis, though customer concentration and the overall cyclicality of AI capex spending are the real risks to watch. As always, that call is yours to make with your advisor, this is one name worth putting on the homework list, not blindly chasing.
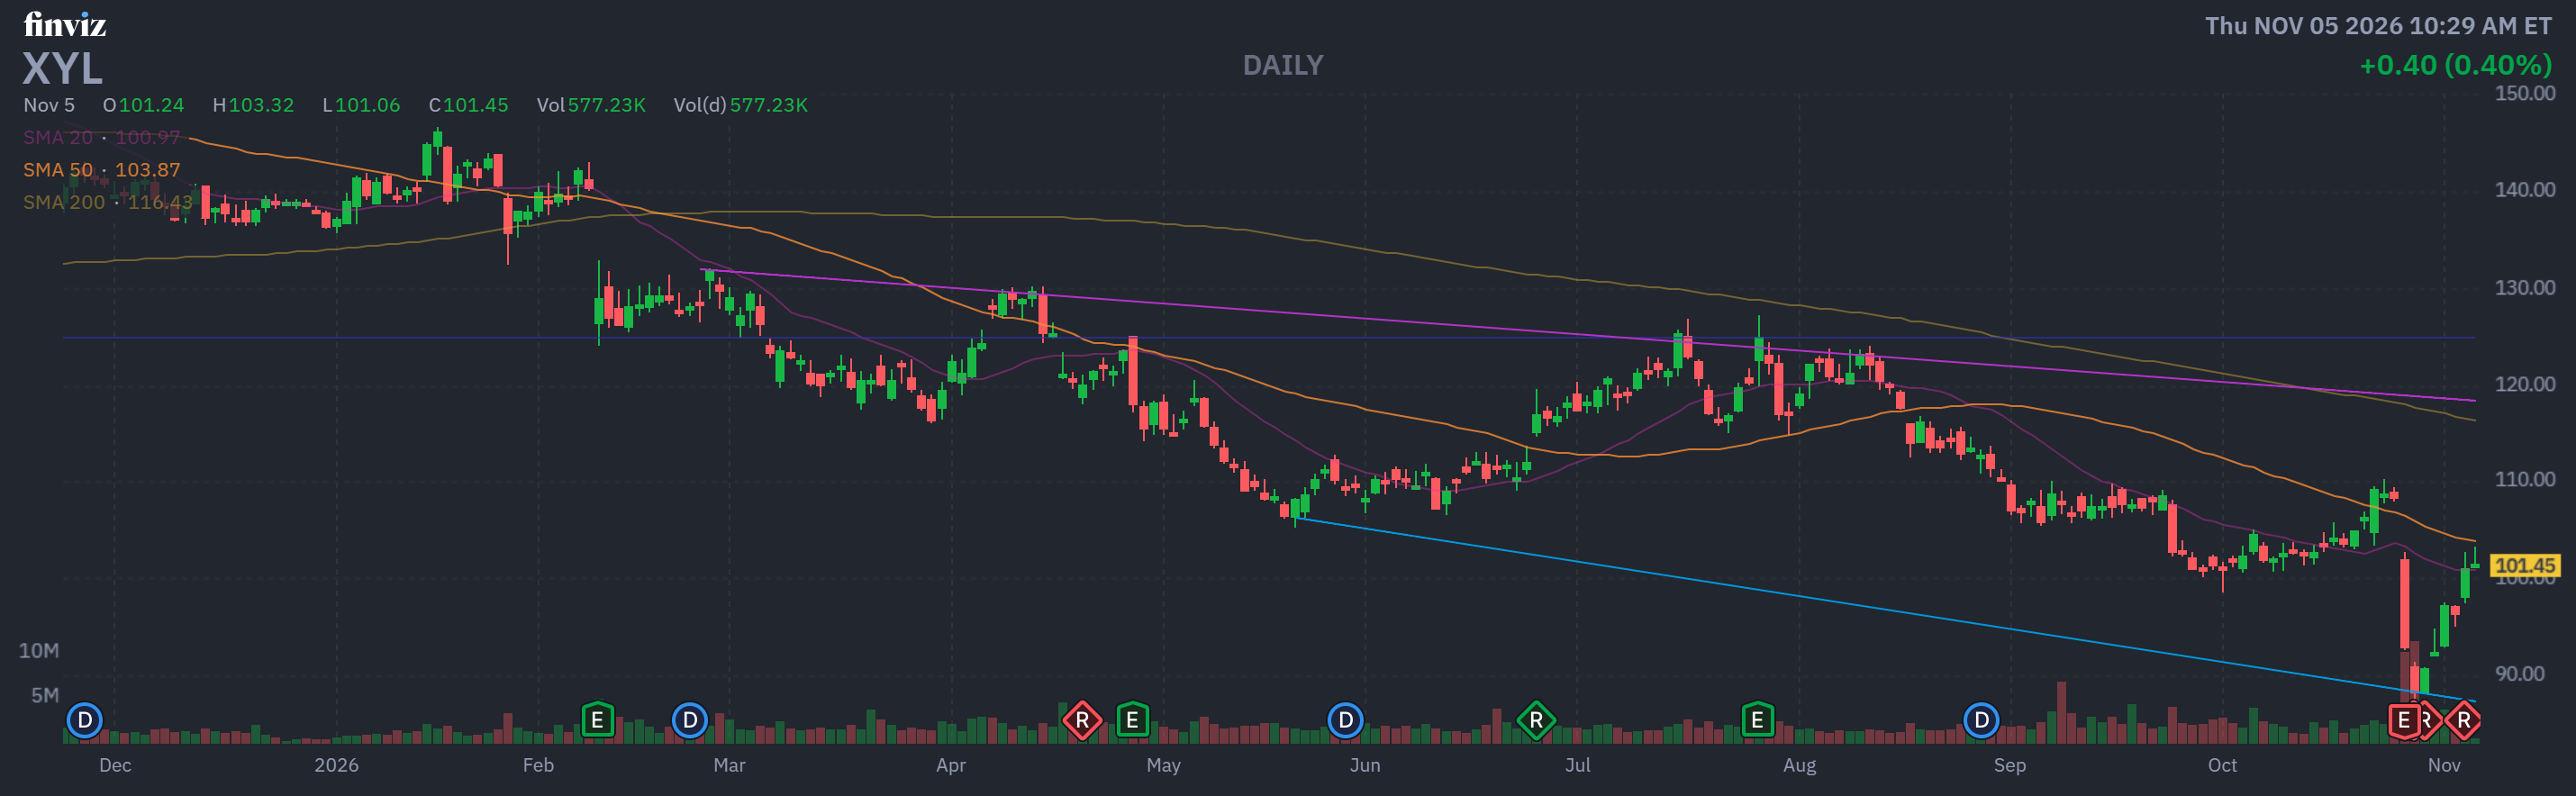
Name: D. Christian Koch
Position: Director
Transaction Date: 10-29-2026 Shares Bought: 11,000 shares an average price paid of $89.60 for Cost: $985,600
Company: Xylem Inc. (XYL)
Xylem Inc. is a global water technology company that designs, manufactures, and services engineered products and solutions for utility, industrial, residential, and commercial applications. The company operates through four segments: Water Infrastructure, Applied Water, Measurement and Control Solutions, and Water Solutions and Services. Its products and services include water, wastewater, and stormwater pumps, filtration and treatment systems, valves, heat exchangers, smart meters, communication devices, sensors, software, data analytics, remote monitoring, and water management solutions. It also provides maintenance, wastewater treatment, environmental remediation, dewatering equipment rentals, and infrastructure services through brands such as Flygt, Goulds Water Technology, Sensus, Godwin, and Xylem Vue. The company was formerly known as ITT WCO, Inc., before changing its name to Xylem Inc. in July 2011. Xylem Inc. was incorporated in 2011 and is headquartered in Washington, District of Columbia.
D. Christian Koch joined Xylem Inc. as an independent Director on August 13, 2026, when he was appointed to the company’s Board of Directors. He joined Xylem in a board capacity rather than as an employee. Koch brings more than 30 years of experience in global industrial businesses and currently serves as Chairman, President and CEO of Carlisle Companies Incorporated, a position he has held since 2016. He joined Carlisle in 2008 and previously held leadership roles at Graco Inc. and H.B. Fuller. He holds a bachelor’s degree from Macalester College and an MBA from the University of Minnesota.
Insomniac Hedge Fund Guy Opinion: XYL just took its lumps, and the market reaction looks roughly proportionate to the news, not overdone, not a gift. My DCF says fair value is close to where it’s trading, the Perfect 10 composite leans mildly bullish on analyst sentiment and cash flow, and a director buying shares into the selloff is a real signal worth noting. But margins trail peers, growth is pedestrian, and management just proved its forecasting isn’t bulletproof. This isn’t a stock to chase on a dip-buy narrative, it’s a hold-and-watch situation: let the next couple of quarters show whether the metering slowdown was a blip or a trend before treating this as a bargain. That call is yours to make with your advisor.
Given the earnings-driven volatility here, this is exactly the kind of setup where an EVS (earnings volatility strategy) play around the next print could be worth a look, big earnings moves often produce the largest percentage swings of the year for a stock like this. Happy to walk through that if you want it.
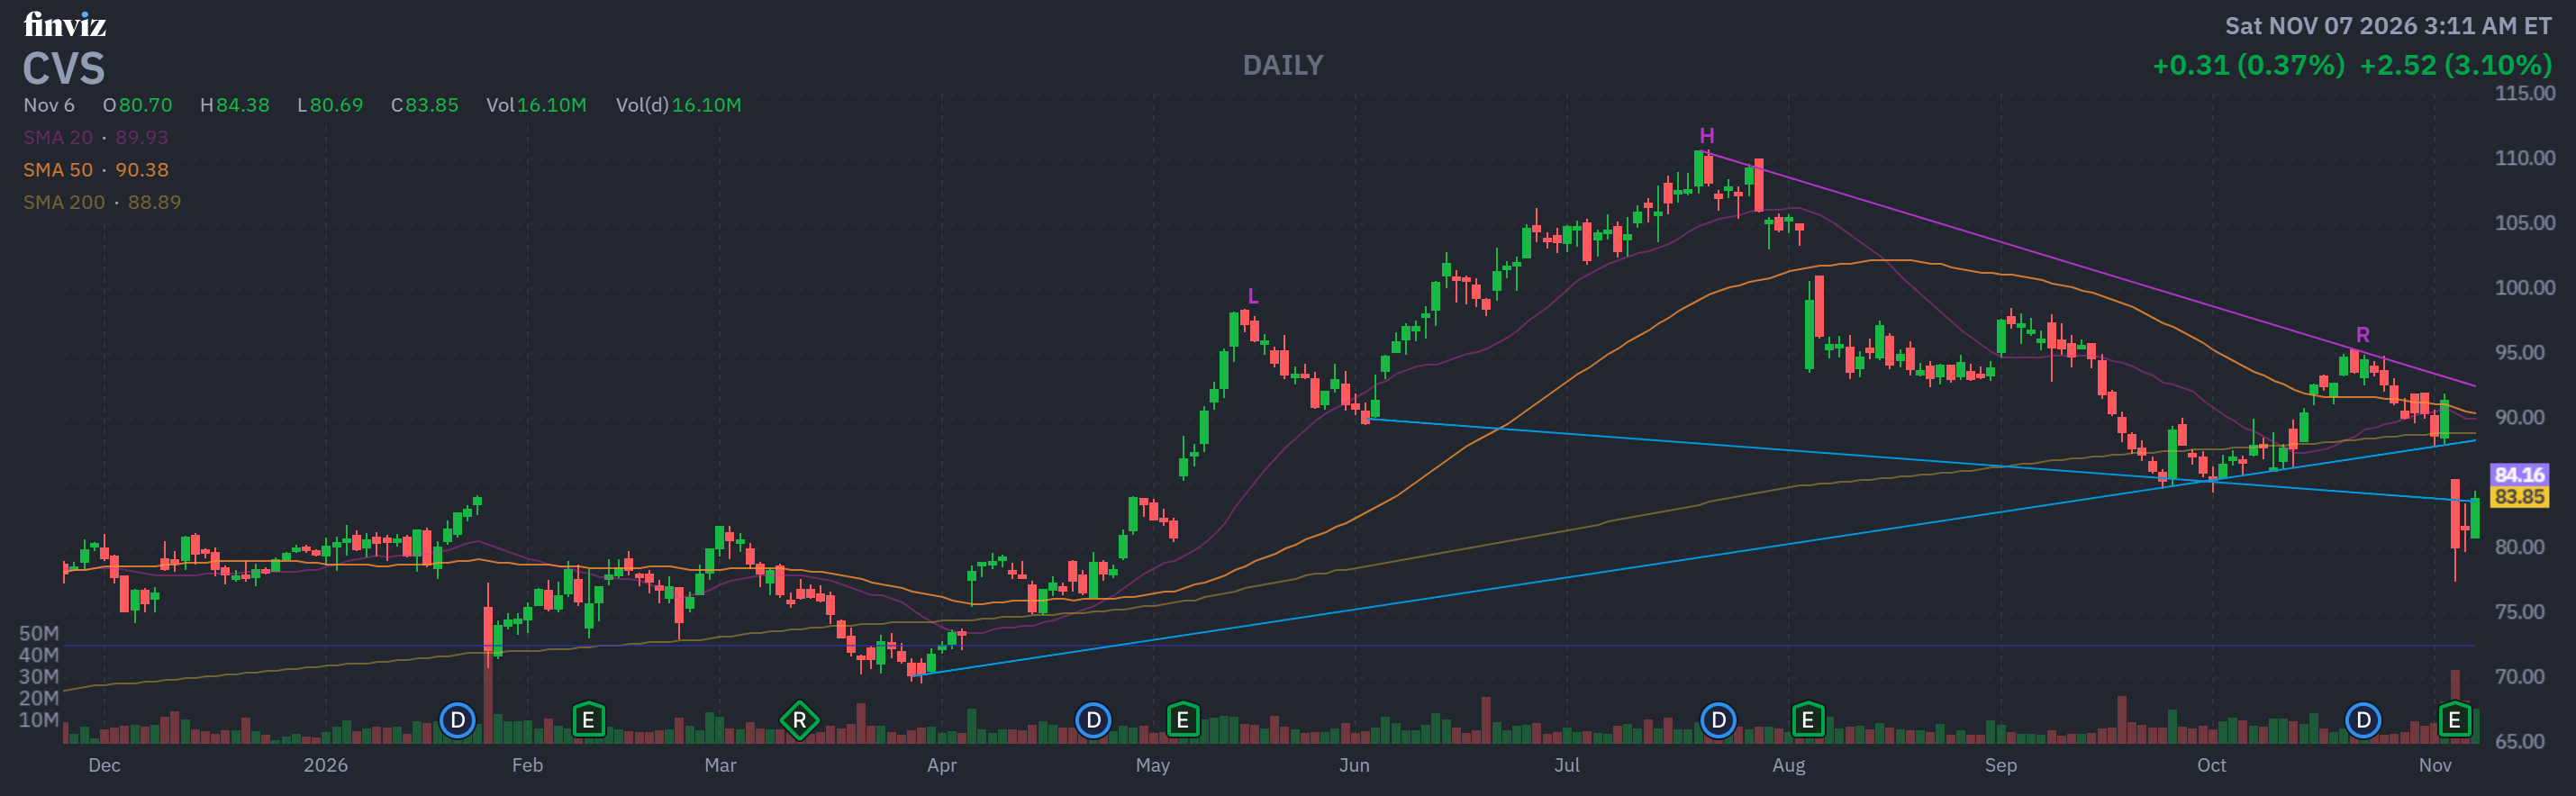
Name: Prem S. Shah
Position: EVP and Group President
Transaction Date: 11-06-2026 Shares Bought: 23,855 shares an average price paid of $83.89 for Cost: $2,001,315
Company: CVS HEALTH Corp (CVS)
CVS Health Corporation is a healthcare company that provides health insurance, pharmacy benefit management, pharmacy services, and consumer wellness products across the United States. The company operates through three segments: Health Care Benefits, Health Services, and Pharmacy & Consumer Wellness. Its offerings include medical, dental, behavioral health, Medicare Advantage, Medicare Supplement, Medicaid, and prescription drug plans. It also provides pharmacy benefit management, formulary management, specialty and mail-order pharmacy services, clinical and disease management, and healthcare administration solutions. Through its retail and specialty pharmacies, the company sells prescription and over-the-counter medications, health and beauty products, and personal care items. It also provides pharmacy consulting, infusion, and enteral nutrition services to care facilities. The company was formerly known as CVS Caremark Corporation before changing its name to CVS Health Corporation in September 2014. CVS Health Corporation was founded in 1963 and is headquartered in Woonsocket, Rhode Island.
Prem S. Shah has been the Executive Vice President and Group President of CVS Health Corporation since November 2024. He joined CVS Health in 2013 and has held several leadership positions across its pharmacy benefit management, specialty pharmacy, and retail pharmacy businesses. Before his current appointment, he served as Executive Vice President and Chief Pharmacy Officer and President of Pharmacy & Consumer Wellness, overseeing the company’s omnichannel pharmacy strategy. Previously, he held senior management positions at ICORE Healthcare and WellCare Health Plans. He holds a Doctorate of Pharmacy from the University of Florida.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite score on CVS reads +5.6 (constructive, leaning solidly bullish), with bullish reads on analyst sentiment, insider activity, cash flow, PEG ratio, and valuation. The stock dropped 12.5% on a quarter that beat estimates and came with raised guidance, that’s not a market rejecting the fundamentals, that’s a market rejecting uncertainty around a two-year corporate transition. At a PE under 10, a PEG under 0.2, growing operating cash flow, light short interest, and a DCF value north of $100 against an $84 stock price, the numbers lean bullish on this one. The risk is real (execution on a messy multi-year breakup is never guaranteed), but at this price the market is paying you to wait and find out. That decision is yours to make with your advisor, particularly around how a pending corporate split affects cost basis and tax treatment down the line.
This is educational, not advice.
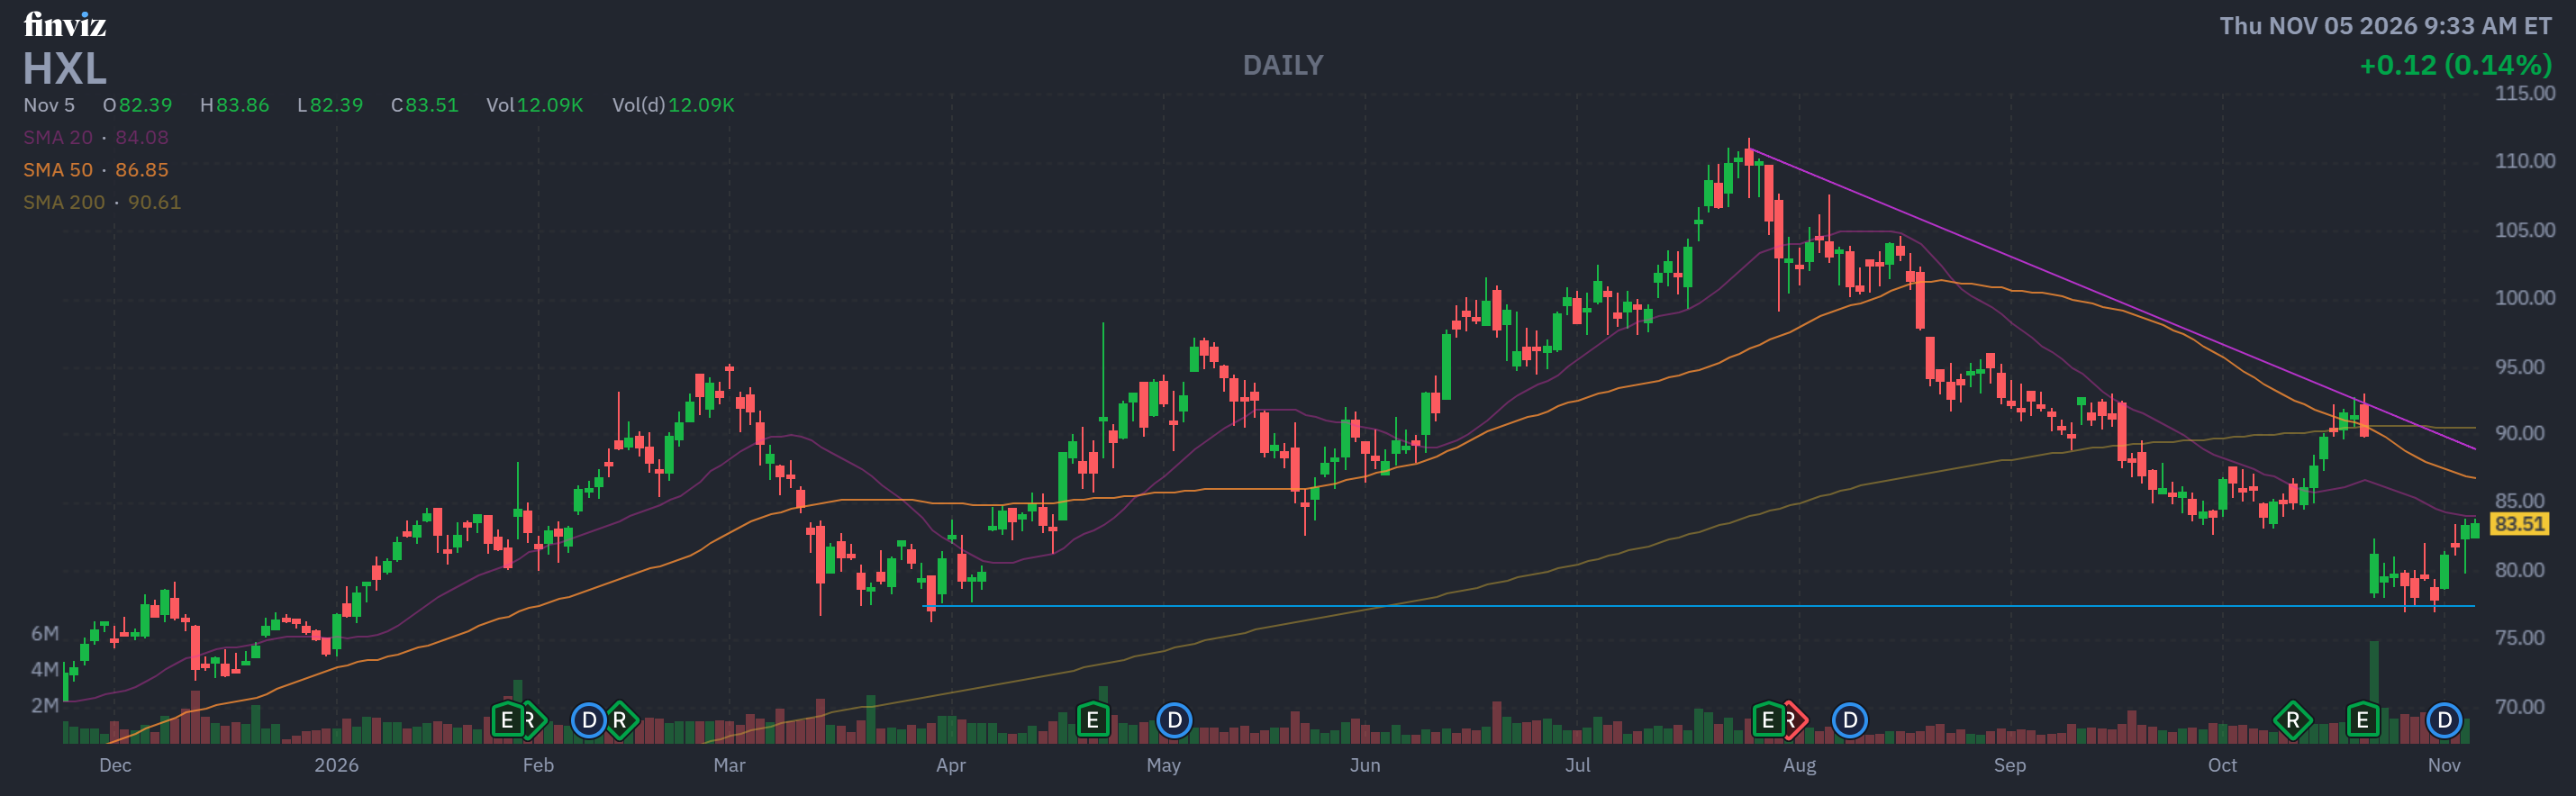
Name: Neal J. Keating
Position: Director
Transaction Date: 10-26-2026 Shares Bought: 3,000 shares an average price paid of $80.67 for Cost: $242,010
Company: Hexcel Corp. (HXL)
Hexcel Corporation develops, manufactures, and markets advanced lightweight composite materials and technologies for aerospace, defense, space, and industrial applications. The company operates through two segments: Composite Materials and Engineered Products. It offers carbon fibers, fabrics, reinforcements, prepregs, honeycomb structures, resins, structural adhesives, laminates, and composite components used in aircraft, rotorcraft, transportation, recreational products, and other industrial applications. Its Engineered Products segment manufactures aircraft structures and components, including wing panels, fairings, flight deck panels, rotorcraft blades, and engine nacelle components. The company also provides electromagnetic interference control materials, dielectric absorber foams, magnetic absorbers, and thermoplastics for commercial and defense applications. Hexcel Corporation was founded in 1946 and is headquartered in Stamford, Connecticut.
Neal J. Keating joined the Board of Directors of Hexcel Corporation on March 3, 2026, and was appointed to its Audit Committee on the same date. He joined Hexcel in a board leadership capacity rather than as an employee. Keating is an experienced aerospace and industrial executive who previously served as Chairman, President and CEO of Kaman Corporation from 2008 to 2020, followed by Executive Chairman until 2021. He also held senior leadership positions at GKN Aerospace and Hughes Supply and has served on the board of Hubbell Incorporated since 2010. He earned a Bachelor of Science degree in Electrical Engineering from the University of Illinois and an MBA from the University of Chicago.
Insomniac Hedge Fund Guy Opinion: Perfect 10 score: +2.5 (constructive, a middle-of-the-road bullish lean), driven by a bullish PEG ratio, bullish cash flow quality, and a bullish insider-buying signal, offset by neutral valuation and a bearish overall market backdrop. The fundamentals are improving (margins up, leverage down, a director buying with real money), but the stock is trading right around fair value on my DCF, and the customer concentration risk is not going away. This isn’t a stock sitting in bargain bin, it’s a quality operator in a cyclical, concentrated business trading at a full price. On these numbers the case leans modestly bullish for patient holders riding the aerospace build-rate cycle, but it is not a screaming buy at 37x earnings with two customers controlling your destiny. I’m on the sidelines if you’re interested.
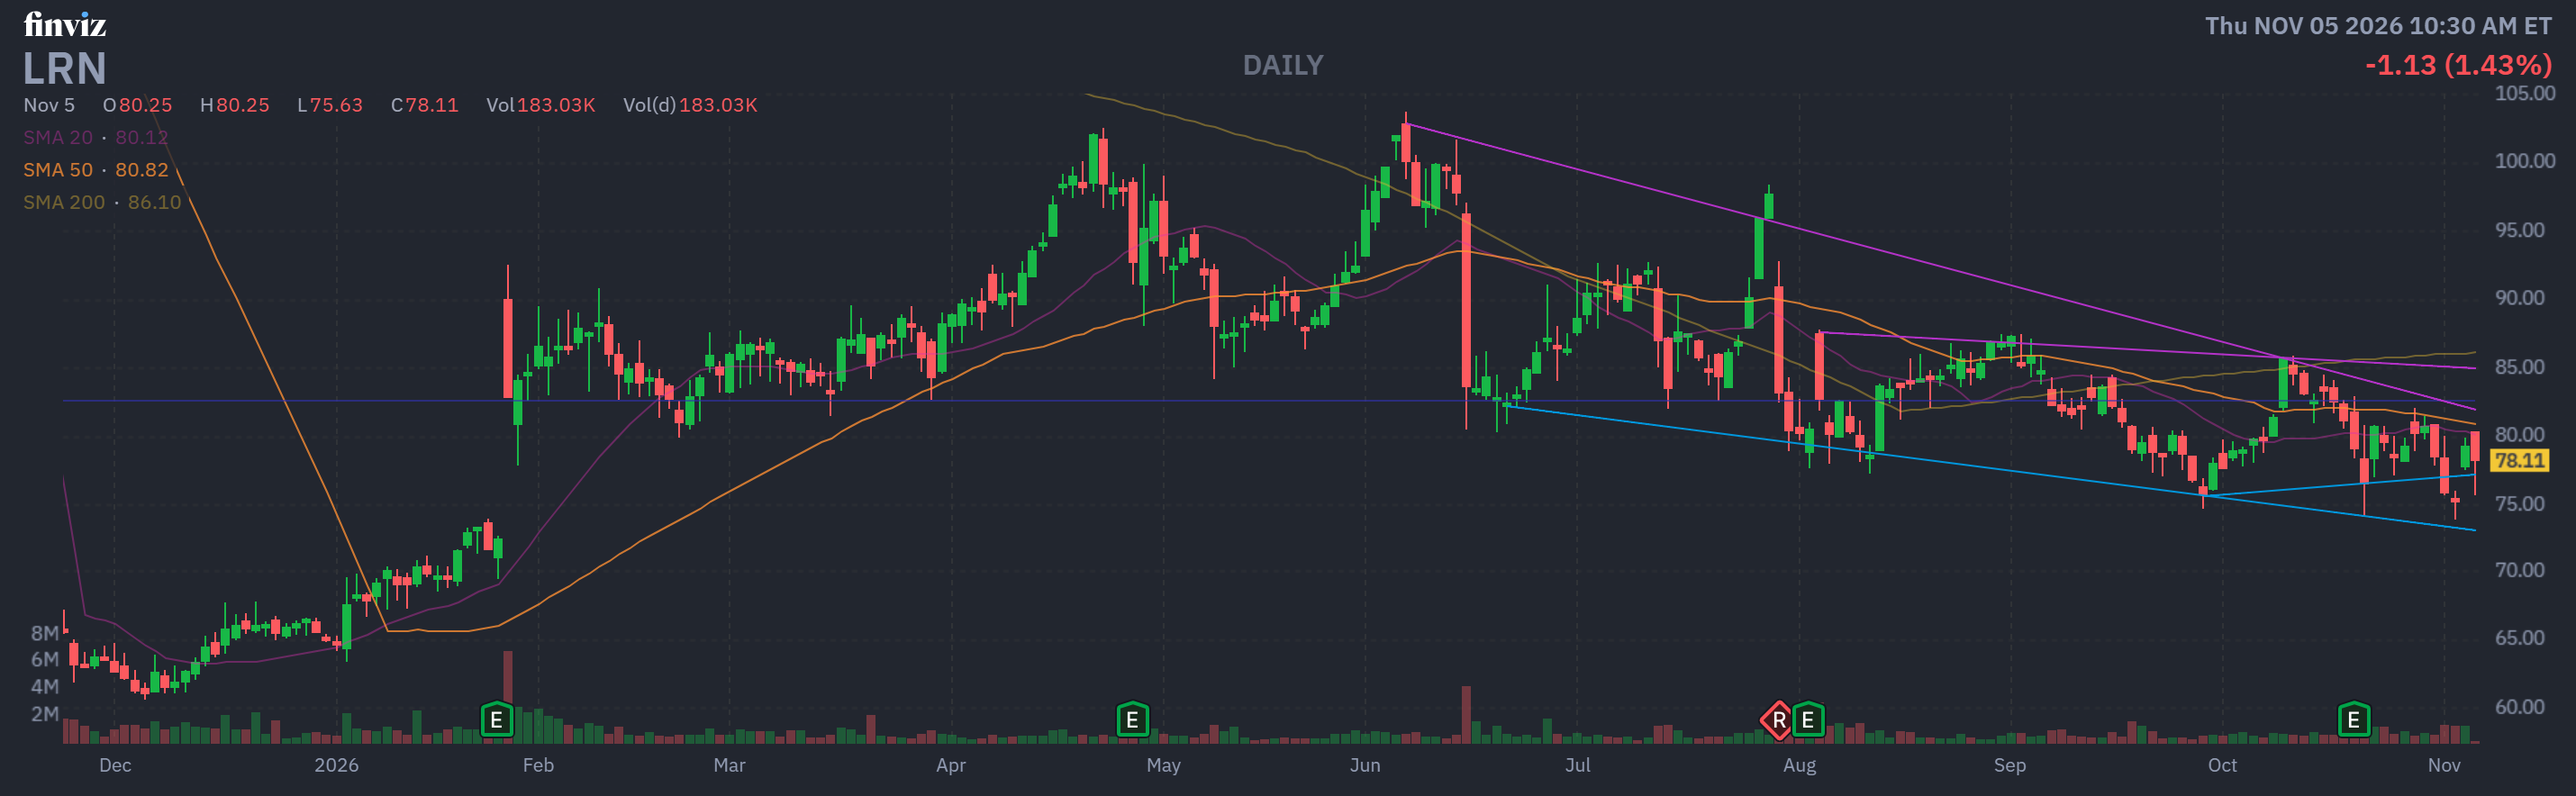
Name: Brian A. Shepherd
Position: Director
Transaction Date: 11-02-2026 Shares Bought: 22,000 shares an average price paid of $75.90 for Cost: $1,669,737
Company: Stride Inc. (LRN)
Stride, Inc. is an education technology company that provides online learning platforms, proprietary and third-party curricula, software systems, and educational services across the United States. Its offerings include online coursework in software engineering, healthcare, and medical fields, along with electives and instructional support. The company provides an integrated educational platform featuring content management, learning management, student information systems, data analytics, and student support tools. It also offers teacher recruitment and training, instructional oversight, professional development, marketing and enrollment assistance, assessment management, administrative support, and technology services. Its solutions serve virtual schools, traditional school districts, public and private schools, charter boards, employers, government agencies, and individual consumers. The company was formerly known as K12 Inc. before changing its name to Stride, Inc. in December 2020. Stride, Inc. was incorporated in 1999 and is headquartered in Reston, Virginia.
Brian A. Shepherd has served as a Director on the Board of Stride Inc. since July 29, 2026, when he was appointed as an independent director. He did not join Stride as an employee; his association with the company began through his Board appointment. Previously, he served as President and Chief Executive Officer of CSG Systems International from 2021 until its acquisition by NEC Corporation in 2026. Before becoming CEO, he was Executive Vice President and Group President at CSG from 2017 to 2021. Earlier in his career, he held executive positions at TeleTech, Amdocs, DST Innovis, and McKinsey & Company. He holds a Bachelor of Arts in Economics from Wabash College and an MBA from Harvard Business School.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite reads +4.5 (constructive): bullish signals on valuation, PEG, cash flow, insider activity, and sector tailwinds, offset by bearish marks on broad market direction and the litigation-related management discussion dimension. The stock is cheap, cash-rich, and has two directors buying with real conviction right after a beat-and-shrug earnings reaction. The lawsuit and decelerating growth are legitimate reasons the market is demanding a discount, but at 10.6x earnings with a sub-0.5 PEG and a DCF value well north of the current price, the risk-reward leans bullish here, this looks more like a market mispricing a profitable, buyback-friendly compounder than a broken business.
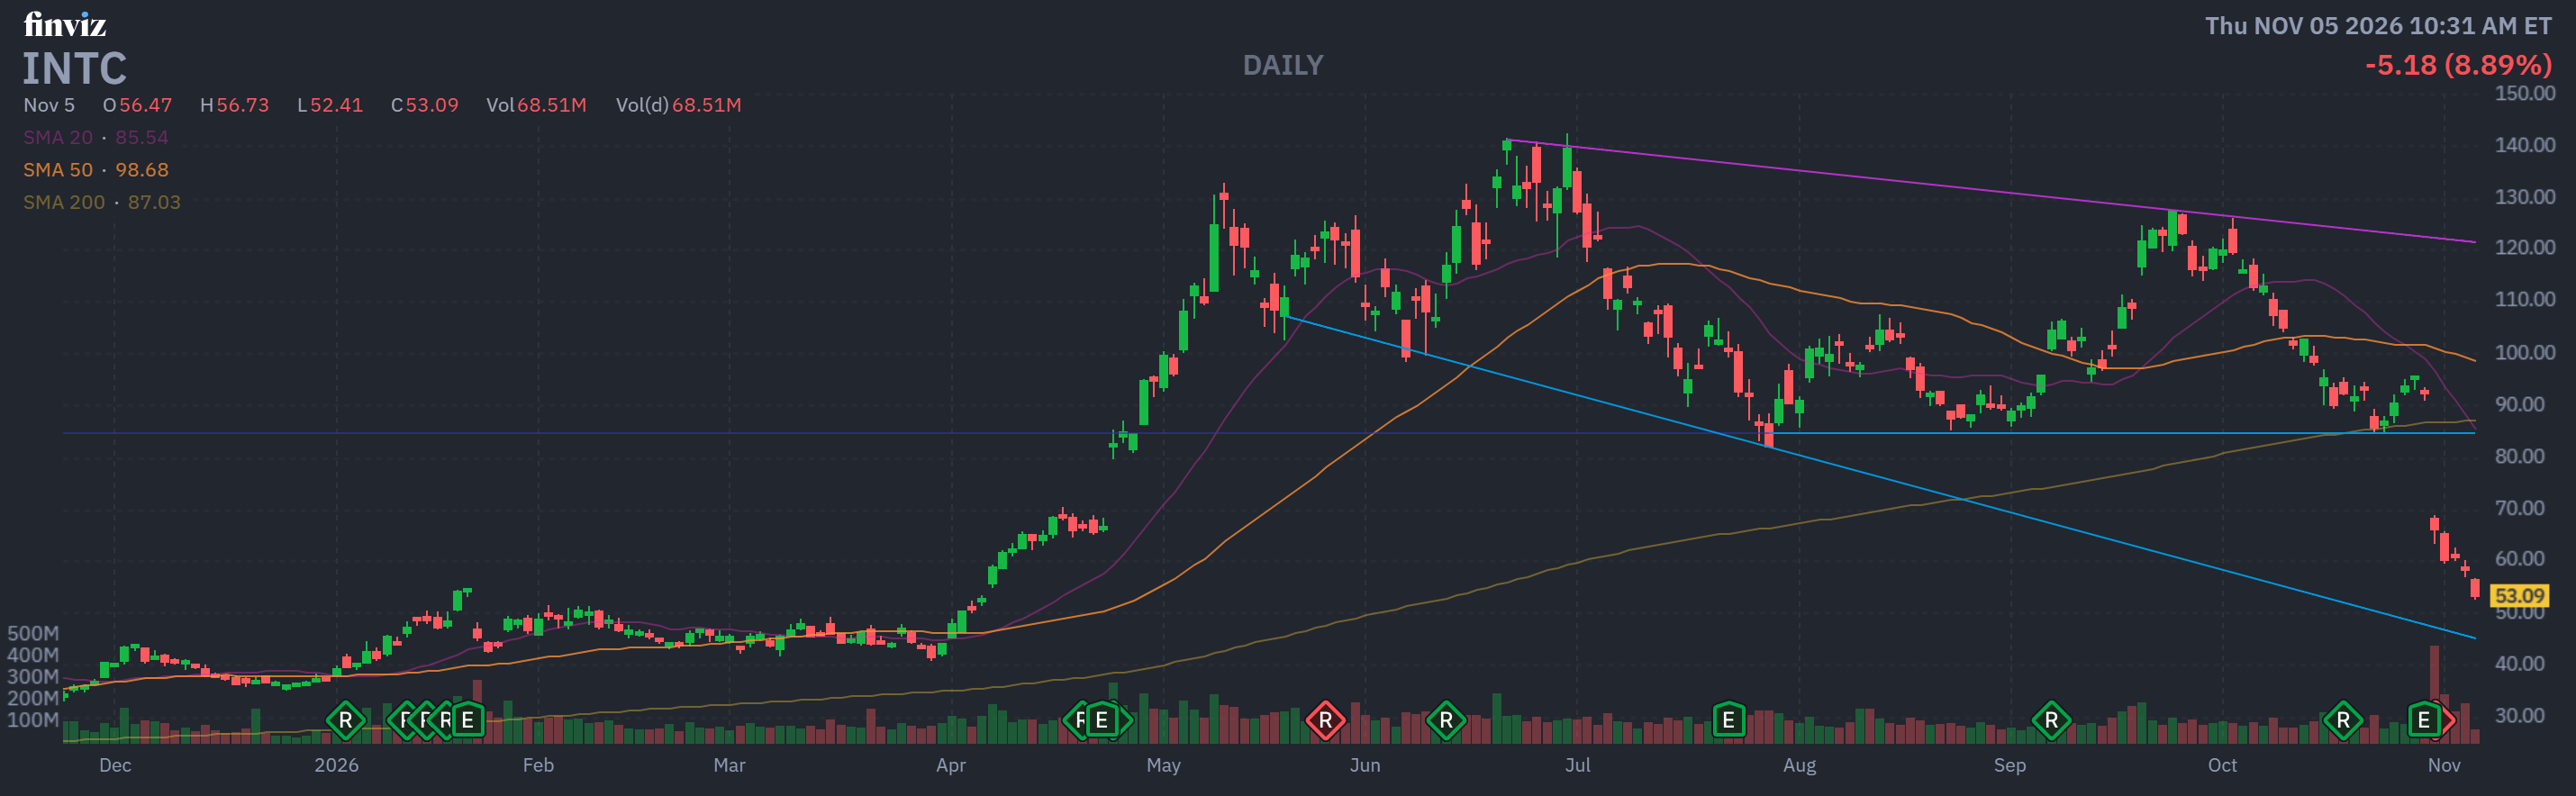
Name: Lip Bu Tan
Position: CEO
Transaction Date: 11-02-2026 Shares Bought: 150,000 shares an average price paid of $64.73 for Cost: $9,709,680
Company: Intel Corp (INTC)
Intel Corporation designs, develops, manufactures, markets, sells, and provides computers and related end products and services in the United States, Ireland, Israel, and across the world. It also provides driving assistance and self-driving technologies, as well as developing and manufacturing multi-beam mask writing instruments. The company’s goods are sold thru sales organizations, distributors, resellers, retailers, and OEM partners. Its customers include original equipment manufacturers, original design manufacturers, cloud service providers, and other manufacturers and service providers. Intel Corporation has formed a strategic partnership with Infosys Limited to create a multi-layer AI fabric that combines infrastructure, models, data, apps, and processes into a modular and agent-ready ecosystem. The company was established in 1968 and is based in Santa Clara, California.
Lip-Bu Tan joined Intel Corporation as Chief Executive Officer on March 18, 2025, after being appointed by the Board on March 12, 2025. He also rejoined Intel’s Board of Directors upon assuming the CEO role, having previously served as a director from September 2022 to August 2024. Tan is a highly respected technology executive and investor with more than 20 years of semiconductor and software industry experience. Before joining Intel, he served as CEO of Cadence Design Systems from 2009 to 2021, leading a major transformation that significantly increased the company’s growth and market value. He holds a Bachelor of Science in Physics from Nanyang Technological University, a Master of Science in Nuclear Engineering from the Massachusetts Institute of Technology, and an MBA from the University of San Francisco.
Insomniac Hedge Fund Guy Opinion: Intel is a show-me story trading on hope, not results. The data center growth is real, the insider buying is a genuine signal worth watching, and the strategic reshoring narrative isn’t hollow. But the company is still unprofitable, still hasn’t landed a marquee foundry customer, and just delivered guidance that badly missed expectations. My DCF puts fair value roughly in line with today’s price, not at a discount, so there’s no clear margin of safety here. This is a hold at best for existing shareholders riding the turnaround thesis, and a show-me-first situation for anyone considering a new position: wait for an 18A customer win or a return to profitability before treating this as anything more than a speculative bet on a comeback that hasn’t happened yet. That decision is yours to make with your financial advisor.
If China moves on Taiwan, the multiple will be infinite but TMSC is rapidly hedging its bets in Arizona.
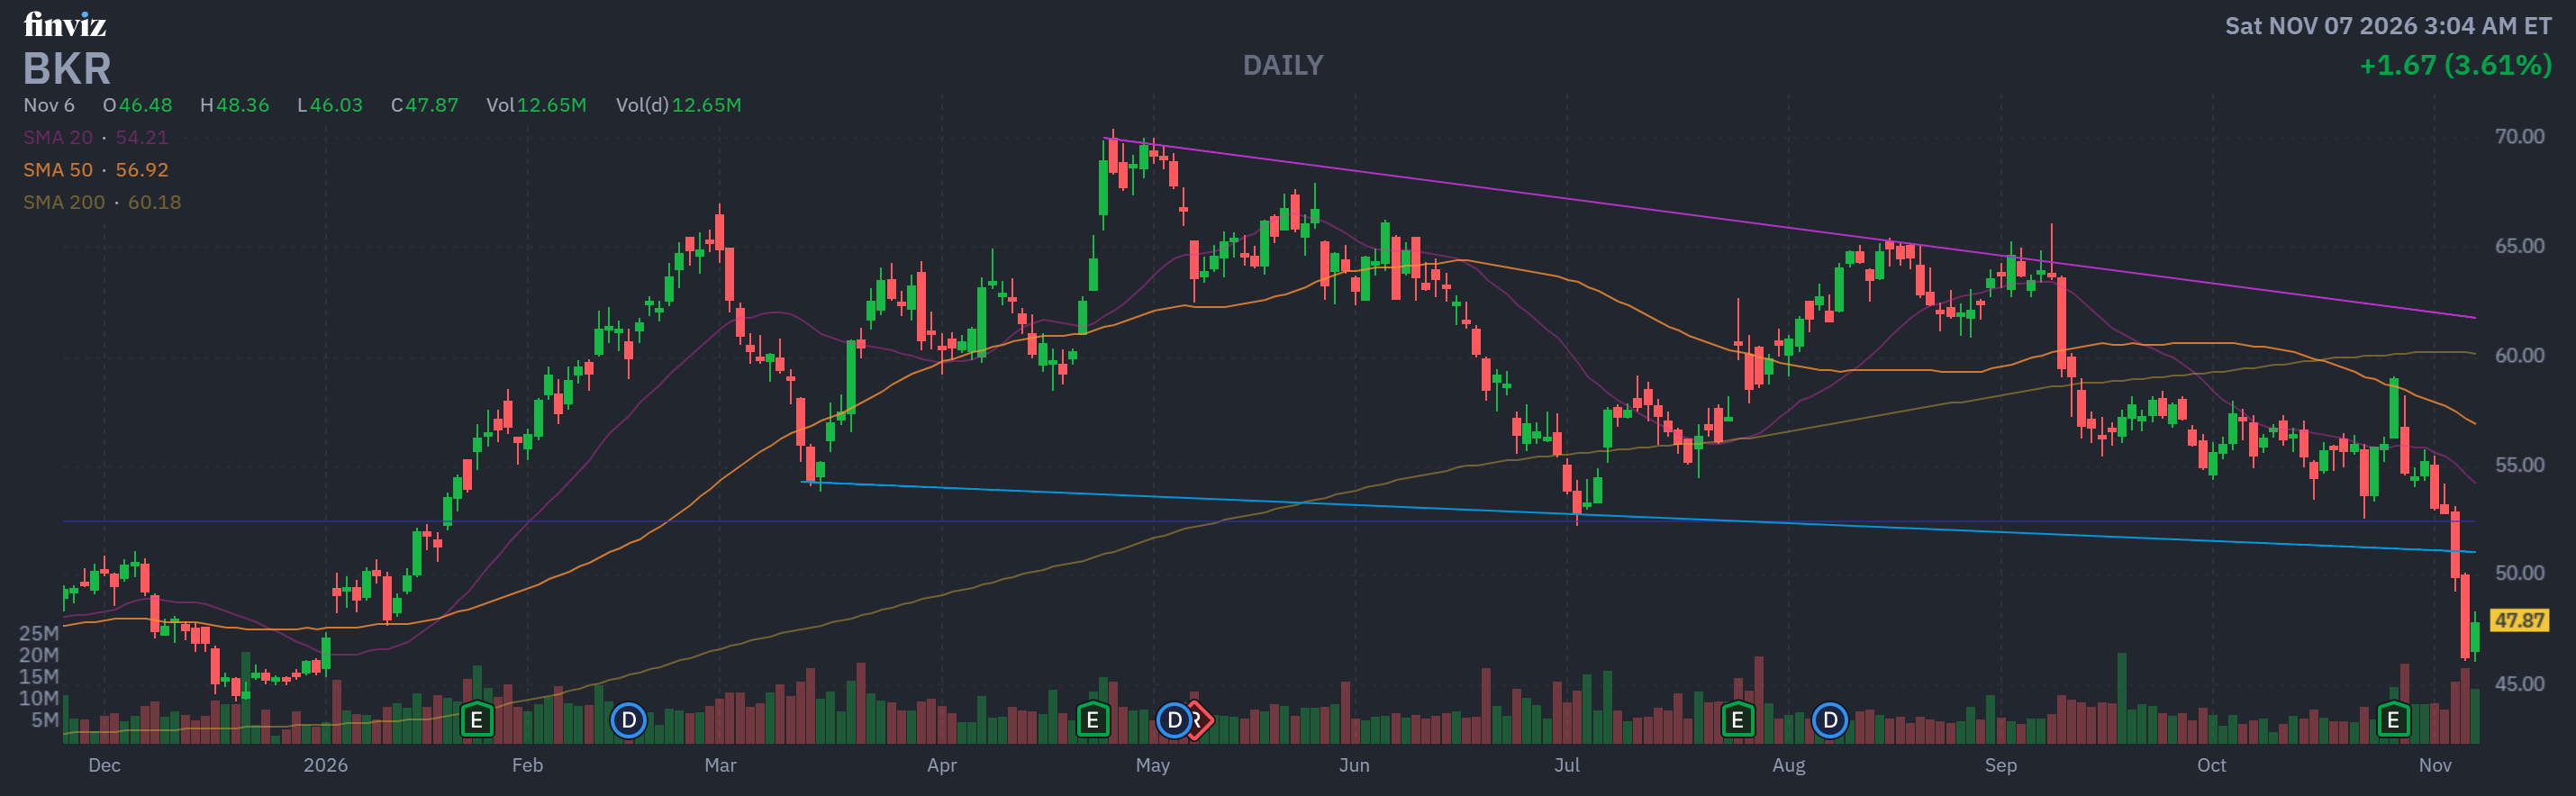
Name: John G. Rice
Position: Director
Transaction Date: 11-03-2026 Shares Bought: 10,000 shares an average price paid of $53.10 for Cost: $531,000
Company: Baker Hughes Co. (BKR)
Baker Hughes Company is an energy technology company that provides products, technologies, and services across the energy and industrial value chain. The company operates through two segments: Oilfield Services & Equipment, and Industrial & Energy Technology. Its Oilfield Services & Equipment segment offers exploration, drilling, completion, intervention, production, subsea, artificial lift, wireline, pressure pumping, and well services, along with drilling equipment, fluids, and oilfield chemicals for onshore and offshore operations. Its Industrial & Energy Technology segment provides gas technology equipment, compression and power-generation solutions, aftermarket services, non-destructive testing, flow control and safety systems, gear transmission systems, asset optimization software, vibration monitoring technologies, and climate technology solutions. The company was formerly known as Baker Hughes, a GE company before changing its name to Baker Hughes Company in October 2019. Baker Hughes Company was incorporated in 2016 and is headquartered in Houston, Texas.
John G. Rice has served as a Director of Baker Hughes Company since 2017, when he joined the company’s Board following the formation of Baker Hughes, a GE company. He did not join Baker Hughes as an employee; his association began through his Board appointment. He was appointed Lead Independent Director effective May 1, 2025. Previously, he spent approximately four decades at General Electric, holding several senior leadership positions, including Vice Chairman, President and CEO of GE Energy, and CEO of GE’s Global Growth Organization. He also served as Non-Executive Chairman of GE Gas Power. He holds a Bachelor of Arts degree in Economics from Hamilton College.
Insomniac Hedge Fund Guy Opinion: Baker Hughes is a company in genuine transition, trading like one that hasn’t gotten credit for it yet. The market punished a legitimate earnings beat because it’s nervous about integration costs, but the underlying story, record IET backlog, data-center power tailwinds, disciplined portfolio pruning, and cash flow that actually backs up the earnings, points toward upside from here. The Perfect 10 composite score lands at +3.3 (constructive, on the -10 to +10 scale), with bullish reads on analyst sentiment, insider activity, sector outlook, and cash flow, offset by a neutral valuation and a bearish broader market backdrop. A DCF in the high $50s to low $60s against a stock sitting under $48 says there’s a gap worth paying attention to. On this evidence, the case leans bullish: BKR looks like a name the market is mispricing on short-term noise while the long-term industrial story quietly improves.
Oil services stocks trade in a group- it’s hard to change that.
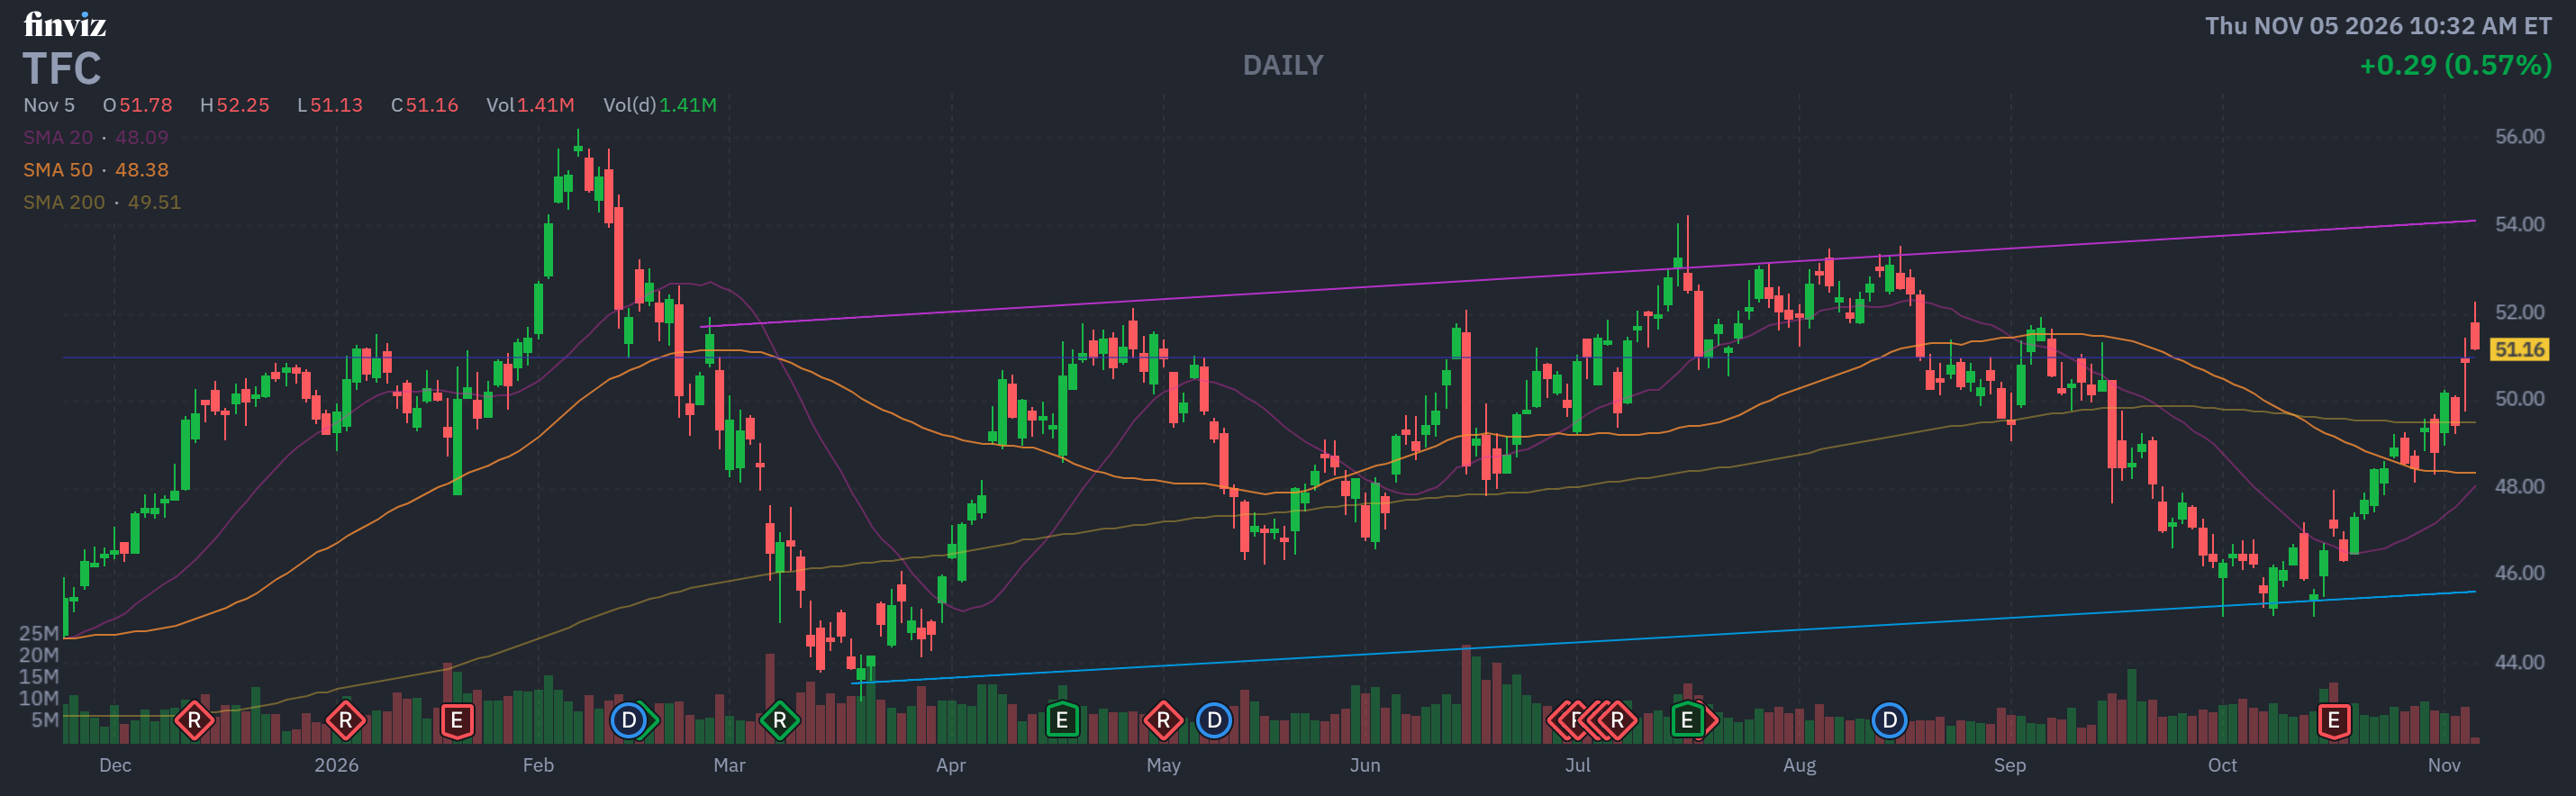
Name: Michael P. Lyons
Position: President and CEO
Transaction Date: 10-28-2026 Shares Bought: 25,000 shares an average price paid of $48.36 for Cost: $1,209,050
Company: Truist Financial Corp. (TFC)
Truist Financial Corporation is a financial services company that provides banking, lending, investment, and trust services across the Southeastern and Mid-Atlantic United States. The company operates through two segments: Consumer and Small Business Banking, and wholesale banking. Its services include checking and savings accounts, certificates of deposit, credit cards, mortgage and commercial lending, asset management, investment banking, wealth management, private banking, treasury services, insurance premium finance, mobile and online banking, and payment solutions. It was formerly known as BB&T Corporation before changing its name to Truist Financial Corporation in December 2019. Truist Financial Corporation was founded in 1872 and is headquartered in Charlotte, North Carolina.
Michael P. Lyons joined Truist Financial Corporation as President and Chief Executive Officer on September 1, 2026, succeeding William H. Rogers Jr. On the same date, he also joined the company’s Board of Directors. He brings more than three decades of experience in financial services, having previously served as CEO of Fiserv from May 2025 to June 2026 and as President of The PNC Financial Services Group from February 2024 to January 2025. Earlier in his career, he held senior leadership positions at Bank of America, Morgan Stanley, and Maverick Capital. He earned a bachelor’s degree from the University of Pennsylvania.
Insomniac Hedge Fund Guy Opinion: Perfect 10 score: +2.2 (Constructive). This isn’t a screaming buy, but it’s not a dog either. Truist is a cheap, cash-flow-honest regional bank mid-restructuring, trading below a reasonable DCF estimate, sitting on a sector tailwind, and backed by a CEO who just put real money where his mouth is. The case leans modestly bullish on valuation and insider conviction, tempered by a flat analyst consensus, overbought short-term technicals, and a management team still more focused on subtraction than growth. That call on timing and sizing is yours to make with your advisor.
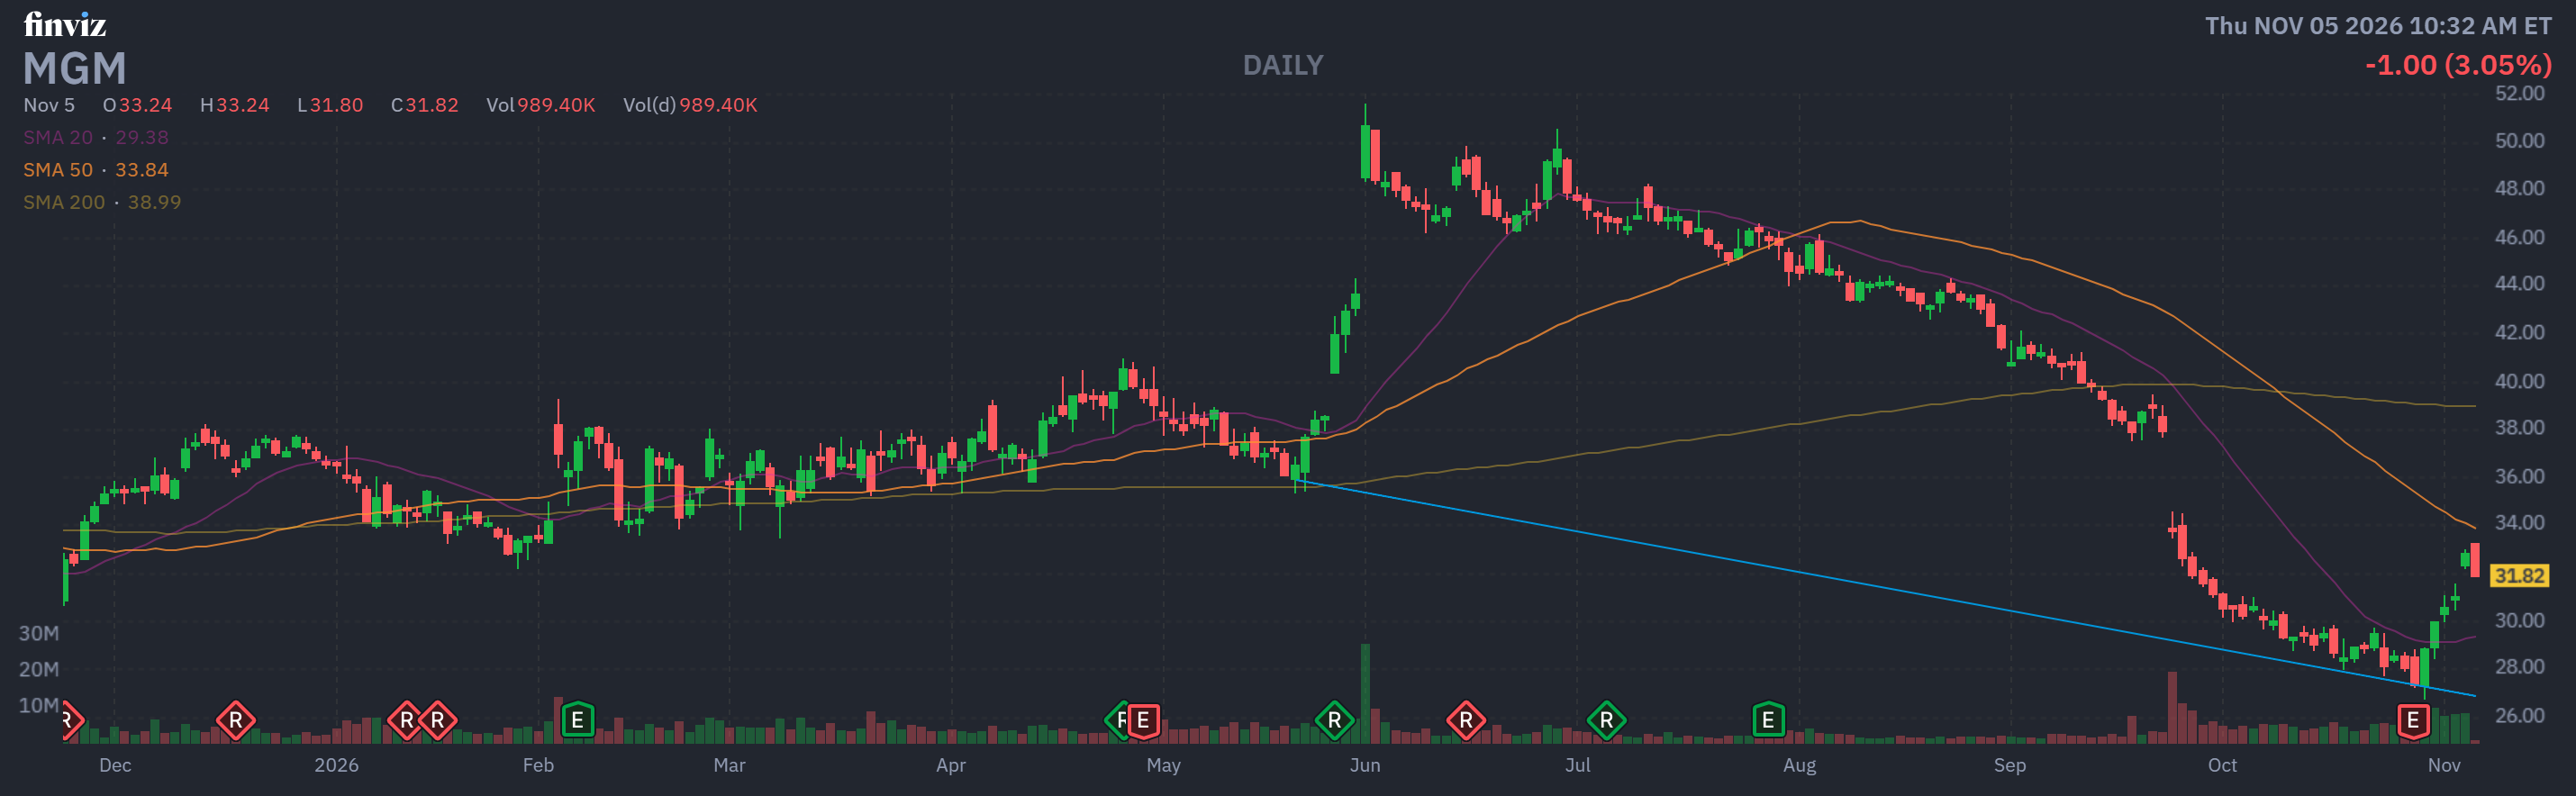
Name: Keith A. Meister
Position: Director
Transaction Date: 10-30-2026 Shares Bought: 1,745,592 shares an average price paid of $29.64 for Cost: $51,740,827
Company: MGM Resorts International (MGM)
MGM Resorts International, through its subsidiaries, operates as a gaming and entertainment company in the United States, China, and internationally. It operates through four segments: Las Vegas Strip Resorts, Regional Operations, MGM China, and MGM Digital. The company operates casino resorts that offer gaming, hotel, convention, dining, entertainment, retail, and other resort amenities, as well as online/digital games through its online platforms. Its casino operations include slots and table games, as well as live dealer, online sports betting, and iGaming through BetMGM. The company was formerly known as MGM MIRAGE and changed its name to MGM Resorts International in June 2010. MGM Resorts International was incorporated in 1986 and is based in Las Vegas, Nevada.
Keith A. Meister has served as a Director on the Board of MGM Resorts International since January 18, 2019, when he was appointed as an independent director. He did not join MGM as an employee; his association with the company began through his Board appointment. Meister is the Founder, Managing Partner and Chief Investment Officer of Corvex Management LP, an investment firm he established in 2010. Previously, he served as Chief Executive Officer and Vice Chairman of Icahn Enterprises, where he worked from 2003 to 2010. He brings extensive experience in investment management, corporate governance and shareholder value creation. He graduated cum laude from Harvard College with an A.B. degree in Government.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite reads +2.5 (constructive, leaning bullish), driven by bullish signals on cash flow, the PEG ratio, and insider buying, offset by bearish broader market direction and a neutral read on valuation. This is a battered, event-driven stock: the takeover premium is gone, Vegas room rates are soft, and earnings quality took a real hit this quarter. But the cash flow is clean, insiders are putting serious money to work, BetMGM and Macau are both growing, and the DCF suggests the current price is roughly fair to modestly cheap. On these numbers the case leans toward a cautious buy for investors with patience for the Strip’s slow-growth phase, not a stock to chase on hype, but also not one to abandon on the post-buyout hangover.
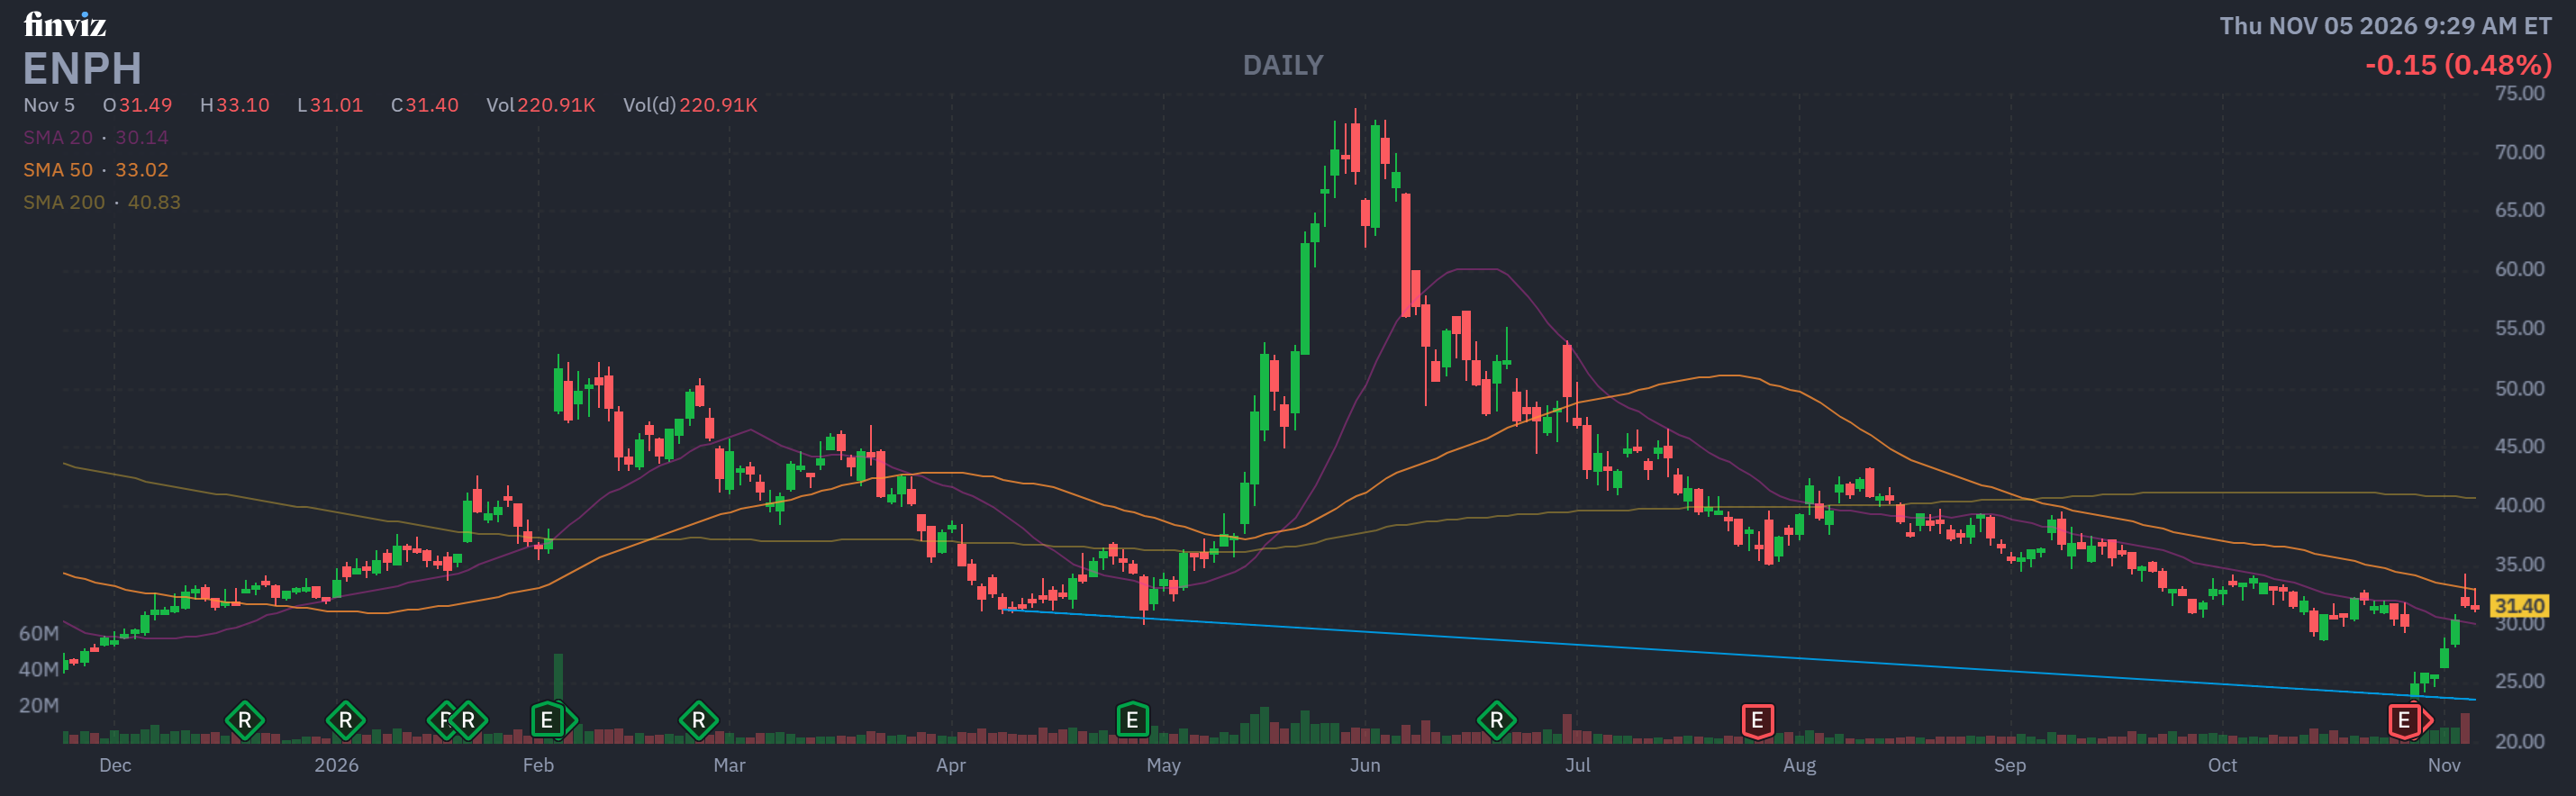
Name: Badrinarayanan Kothandaraman
Position: President & CEO
Transaction Date: 11-02-2026 Shares Bought: 10,000 shares an average price paid of $26.75 for Cost: $267,514
Company: Enphase Energy Inc. (ENPH)
Enphase Energy, Inc. is a global energy technology company that designs, develops, manufactures, and sells home energy solutions for the solar photovoltaic industry. The company offers semiconductor-based microinverters that convert solar energy at the individual module level and integrate with proprietary networking and software technologies for energy monitoring and control. Its products include microinverters, IQ Batteries, IQ PowerPack 1500, IQ Combiner, IQ Gateway, IQ Energy Router, cloud-based monitoring services, and electric vehicle charging solutions. It also provides solar design, proposal, permitting, installation, appointment generation, and Enphase Care services. The company sells its solutions to solar distributors, installers, original equipment manufacturers, strategic partners, and homeowners. Enphase Energy, Inc. was incorporated in 2006 and is headquartered in Fremont, California.
Badrinarayanan Kothandaraman has served as President and Chief Executive Officer of Enphase Energy Inc. since September 2017. He joined the company in April 2017 as Chief Operating Officer and was appointed President and CEO, along with membership on the Board of Directors, in September 2017. Before joining Enphase, he spent more than two decades at Cypress Semiconductor, where he held several senior leadership positions, including Executive Vice President of its Data Communications Division. He holds a Bachelor of Technology degree from the Indian Institute of Technology Madras and a Master of Science degree in Materials Science from the University of California, Berkeley.
Insomniac Hedge Fund Guy Opinion: Enphase is a technically superior product in a demand environment that’s working against it, trading at a price that already reflects a lot of that pain but not all of it. Margins are good, management has a real track record, and the DCF suggests fair value isn’t far above the current price. But a flat five-year revenue trend, a cash-flow quality problem, heavy customer concentration, and short interest near a quarter of the float tell me this is a show-me story, not a conviction buy. My lean: hold what you have, don’t chase it here, and if core demand (not safe-harbor shipments) shows two consecutive quarters of actual growth, revisit. That decision is yours to make with your advisor.
Given that 24% short interest and a stock that gaps double digits on earnings surprises, this is a textbook candidate for an earnings volatility play around the next print, happy to walk through that strategy if you want it.
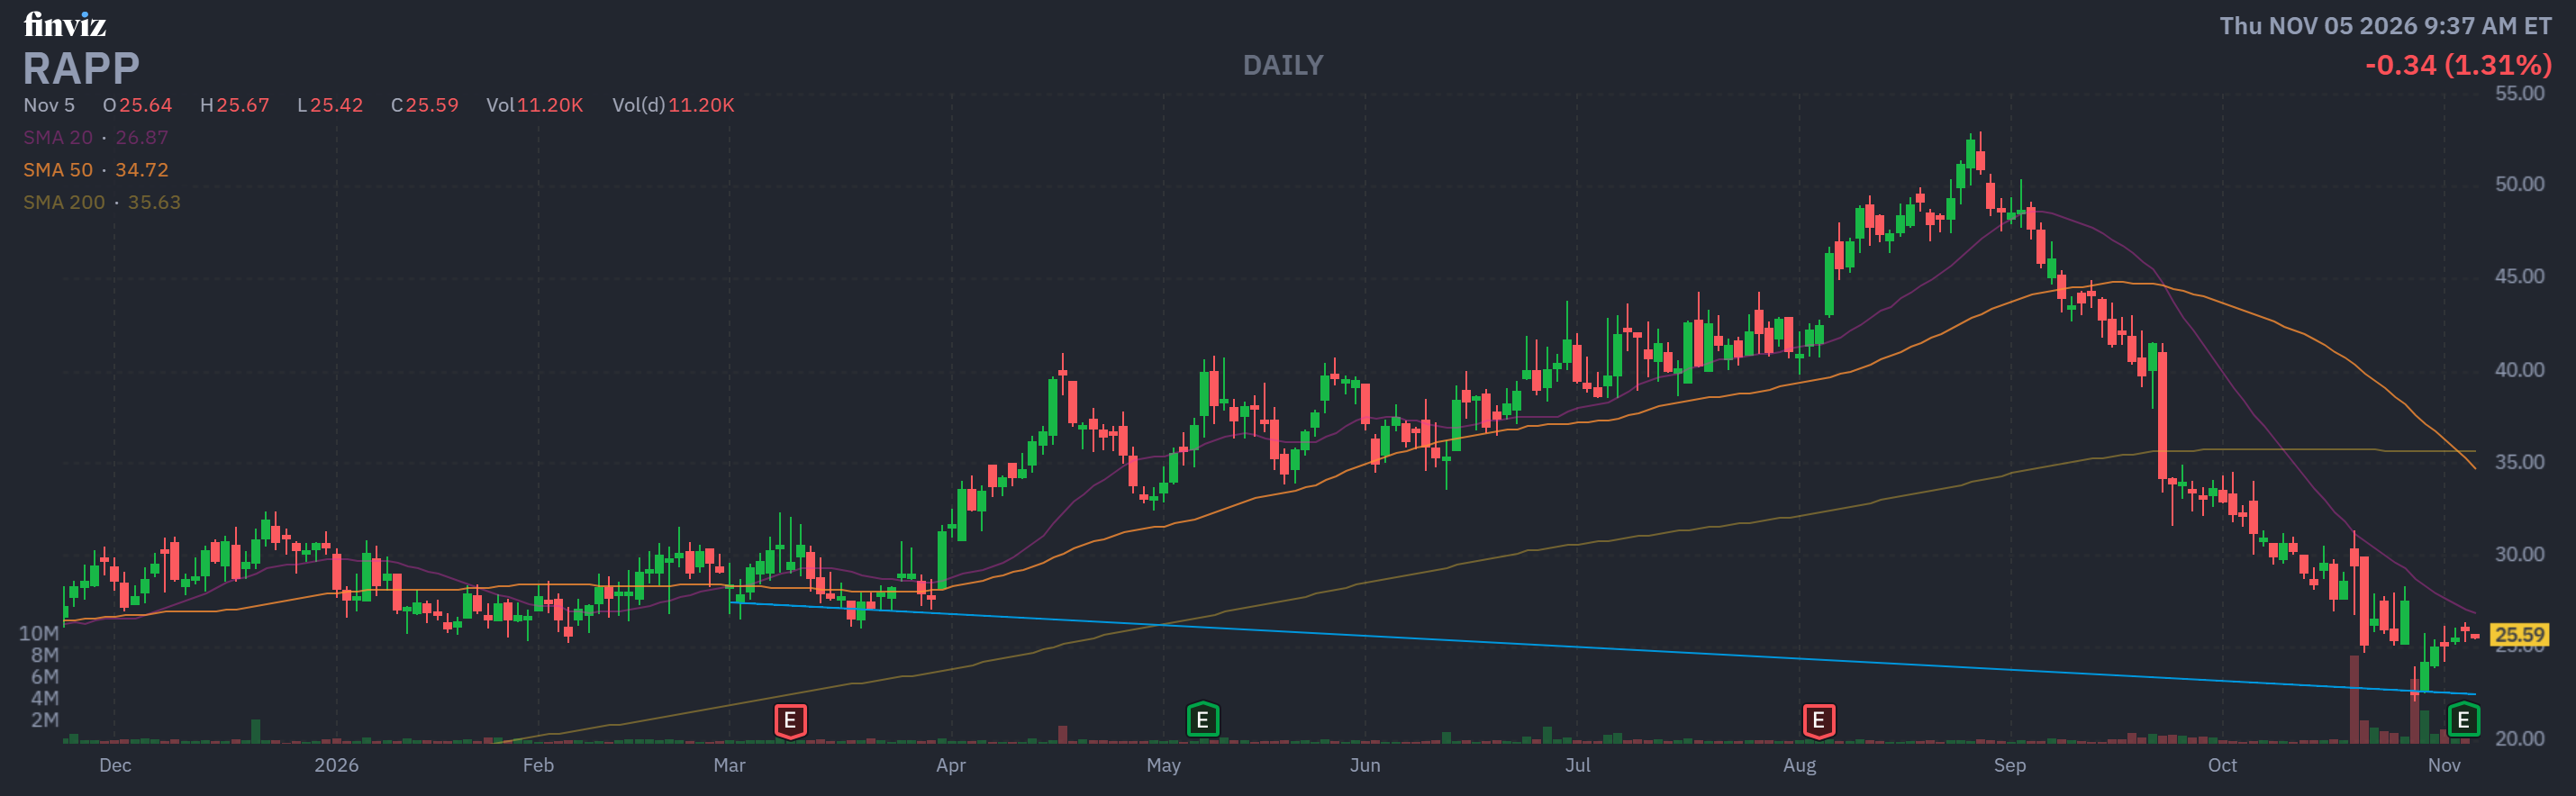
Name: John Maraganore
Position: Director
Transaction Date: 10-22-2026 Shares Bought: 9,411 shares an average price paid of $26.45 for Cost: $248,891
Name: James Healy
Position: Director
Transaction Date: 10-28-2026 Shares Bought: 969,480 shares an average price paid of $21.00 for Cost: $20,359,080
Company: Rapport Therapeutics Inc. (RAPP)
Rapport Therapeutics, Inc. is a clinical-stage biopharmaceutical company focused on discovering and developing small-molecule medicines for patients with central nervous system disorders. The company’s lead product candidate, RAP-219, is an investigational medicine designed to target specific AMPA receptors for the treatment of focal epilepsy and other neurological conditions, including peripheral neuropathic pain and bipolar disorder. It also develops nicotinic acetylcholine receptor programs targeting chronic pain, migraine, and hearing and vestibular disorders. The company was formerly known as Precision Neuroscience NewCo, Inc. before changing its name to Rapport Therapeutics, Inc. in October 2022. Rapport Therapeutics, Inc. was incorporated in 2022 and is headquartered in Boston, Massachusetts.
John Maraganore has served as a Director on the Board of Rapport Therapeutics Inc. since March 2024. He joined the company’s Board of Directors to contribute his extensive experience in biotechnology, pharmaceutical innovation, and corporate leadership. Maraganore previously served as the founding Chief Executive Officer of Alnylam Pharmaceuticals from 2002 to 2021, helping establish the company as a leader in RNA interference therapeutics. He currently serves as a Venture Partner at ARCH Venture Partners and Atlas Venture and advises life sciences businesses. He holds a Bachelor of Arts in Biological Sciences and both a Master of Science and a Ph.D. in Biochemistry and Molecular Biology from the University of Chicago.
James I. Healy has served as a Director on the Board of Rapport Therapeutics Inc. since August 2023, when he was appointed alongside the company’s Series B funding announcement. He did not join Rapport as an employee; his association began through his Board appointment. He has served as Managing Partner of Sofinnova Investments since June 2000, investing in and supporting biotechnology and healthcare companies. He previously held positions at Bayer and Sanderling Ventures and has extensive experience serving on biotechnology company boards. He holds bachelor’s degrees in Molecular Biology and Scandinavian Studies from the University of California, Berkeley, as well as an M.D. and Ph.D. in Immunology from Stanford University School of Medicine.
Insomniac Hedge Fund Guy Opinion: RAPP is a high-risk, binary science bet wrapped in a well-funded balance sheet. The cash runway buys time, the Phase 2 data is genuinely encouraging, and insiders are putting real money where their mouths are. But there is no revenue, no profit, and no moat until Phase 3 reads out, probably not until 2027 or later. On the numbers, this leans speculative-bullish for investors who can stomach binary clinical risk and multi-year dilution, not a stock for anyone who needs cash flow or certainty. Size any position like the lottery ticket it is, and do your own homework on the trial data before you touch it.
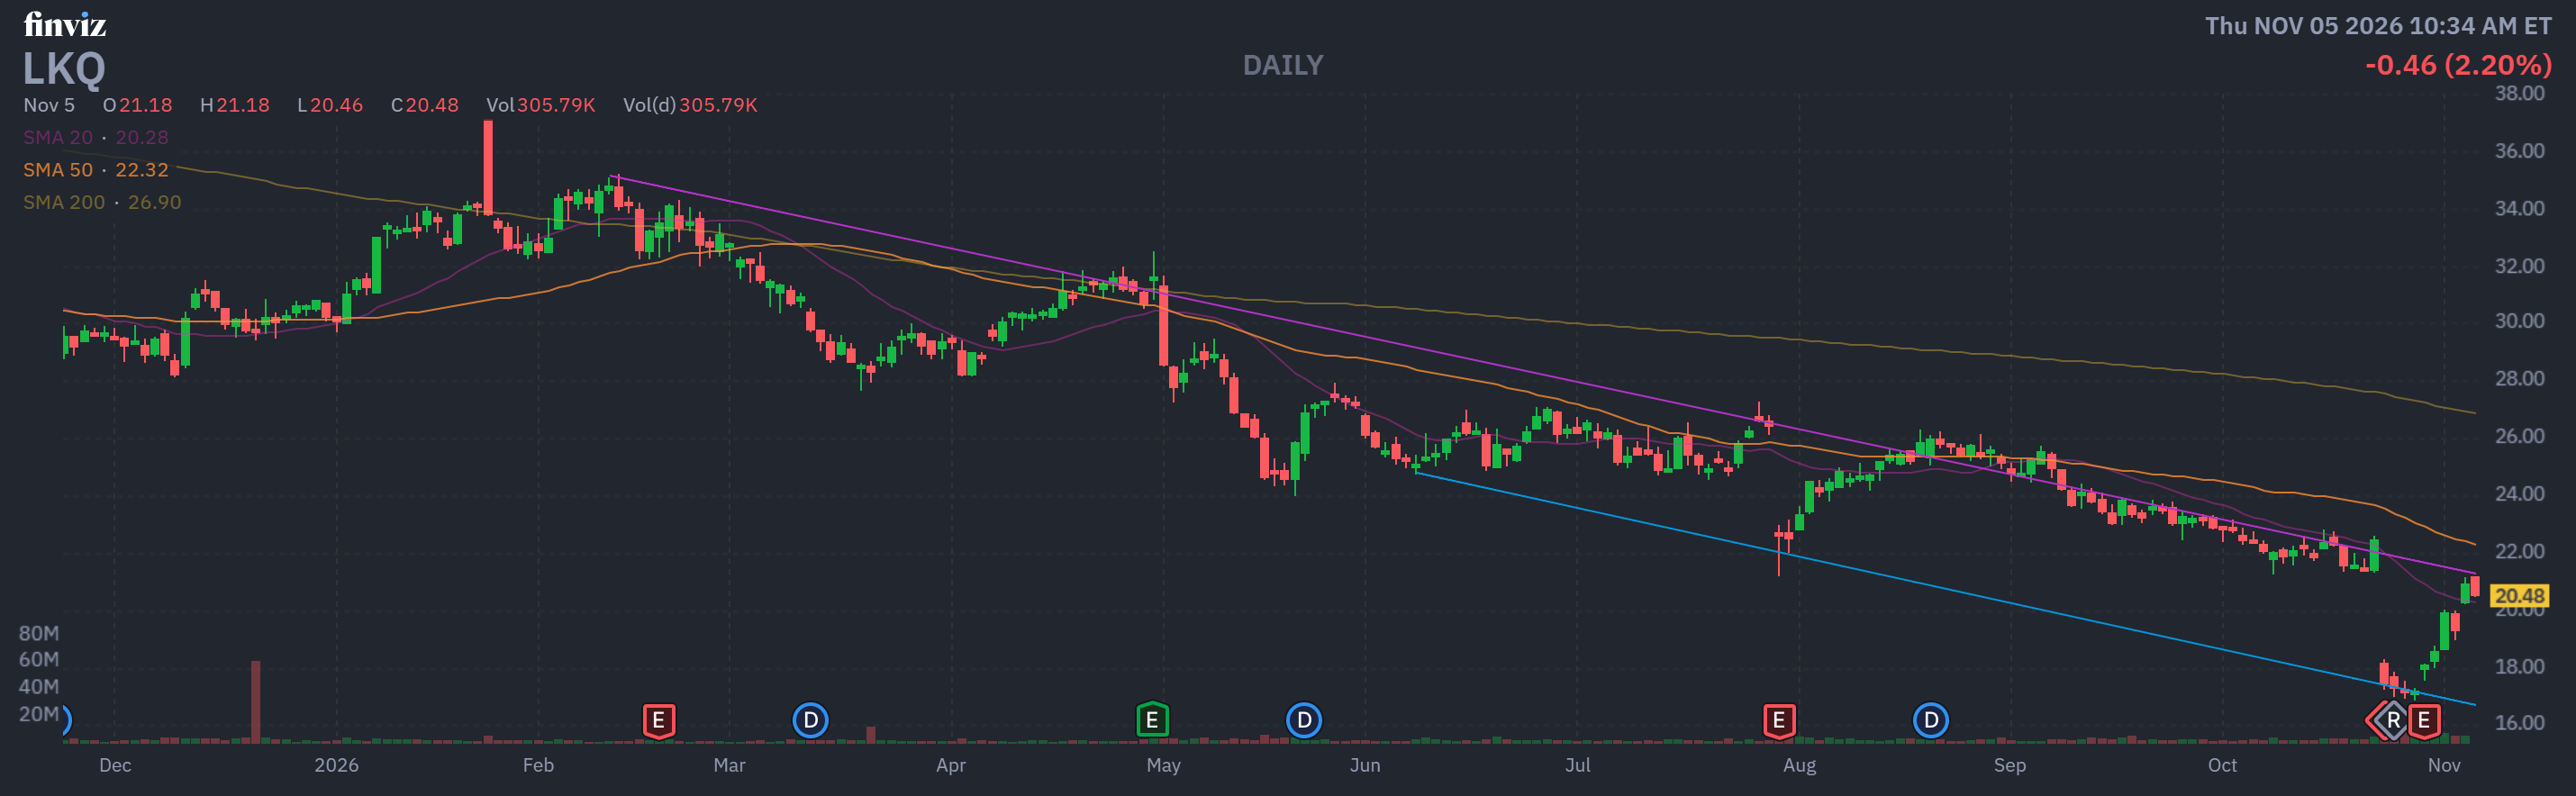
Name: Gove Sue
Position: Director
Transaction Date: 11-04-2026 Shares Bought: 9,795 shares an average price paid of $20.53 for Cost: $201,085
Name: Michael Scott Powell
Position: Director
Transaction Date: 11-02-2026 Shares Bought: 10,000 shares an average price paid of $19.15 for Cost: $191,500
Name: Andrew C. Clarke
Position: Director
Transaction Date: 10-30-2026 Shares Bought: 21,800 shares an average price paid of $18.35 for Cost: $400,030
Company: LKQ Corp (LKQ)
LKQ Corporation is a global distributor of replacement parts, components, and systems used in vehicle repair and maintenance, as well as specialty vehicle aftermarket products and accessories. The company operates through four segments: Wholesale-North America, Europe, Specialty, and Self Service. Its product portfolio includes automotive body panels, bumper covers, lights, paint and refinishing supplies, mechanical parts, engines, transmissions, brake systems, steering and suspension products, filters, batteries, and automotive fluids. It also distributes recycled vehicle parts, precious metals, recreational vehicle appliances, towing hitches, truck accessories, marine electronics, wheels, and tires. The company serves collision and mechanical repair shops, vehicle dealerships, and retail customers across North America and Europe. LKQ Corporation was incorporated in 1998 and is headquartered in Antioch, Tennessee.
Sue Gove joined LKQ Corporation as an independent Director and member of the Board of Directors on February 5, 2025. She is an experienced business executive with extensive leadership experience in retail, finance, and corporate governance. She has served as Founder and President of Excelsior Advisors, LLC, a retail consulting firm, since 2014. Previously, she held senior executive positions at Bed Bath & Beyond, Golfsmith International, Vitamin World, and Zale Corporation, including serving as President and CEO of Bed Bath & Beyond. She holds a Bachelor of Business Administration degree in Accounting from the University of Texas at Austin’s McCombs School of Business.
Michael Scott Powell has served as a Director on the Board of LKQ Corporation since February 5, 2025, when he was appointed as an independent director. He did not join LKQ as an employee; his association with the company began through his Board appointment. Powell previously spent more than two decades at Progressive Corporation, where he held several leadership positions, most recently serving as Claims Process General Manager from 2022 to 2024. He also serves as an advisory board member of The Crawford Group, the parent company of Enterprise Holdings. He holds a Bachelor of Science degree in Business Administration from Morningside University and an MBA from Drake University.
Andrew C. Clarke has served as a Director on the Board of LKQ Corporation since July 22, 2024, when he was appointed as an independent director. He did not join LKQ as an employee; his association with the company began through his Board appointment. Clarke brings more than 20 years of experience in the transportation and logistics industries. He previously served as Chief Financial Officer of C.H. Robinson from 2015 to 2019, Chief Executive Officer of Panther Expedited Services from 2007 to 2013, and held senior financial leadership positions at Forward Air Corporation. He holds a Bachelor of Science in Business Administration from Washington University in St. Louis and an MBA from the University of Chicago Booth School of Business.
Insomniac Hedge Fund Guy Opinion: This is a company in the penalty box for a real, self-inflicted European stumble, not a structurally broken business. The cash flow is genuine, the valuation already prices in a lot of pessimism, and a management shake-up plus outside restructuring help gives a credible, if unproven, path to repair. On these numbers the case leans constructive, closer to a contrarian buy than a value trap, but this is a “show me” stock until the new CEO delivers a clean quarter. That decision is yours to make with your advisor, weighing your own risk tolerance against a name that still has real execution risk on the table.
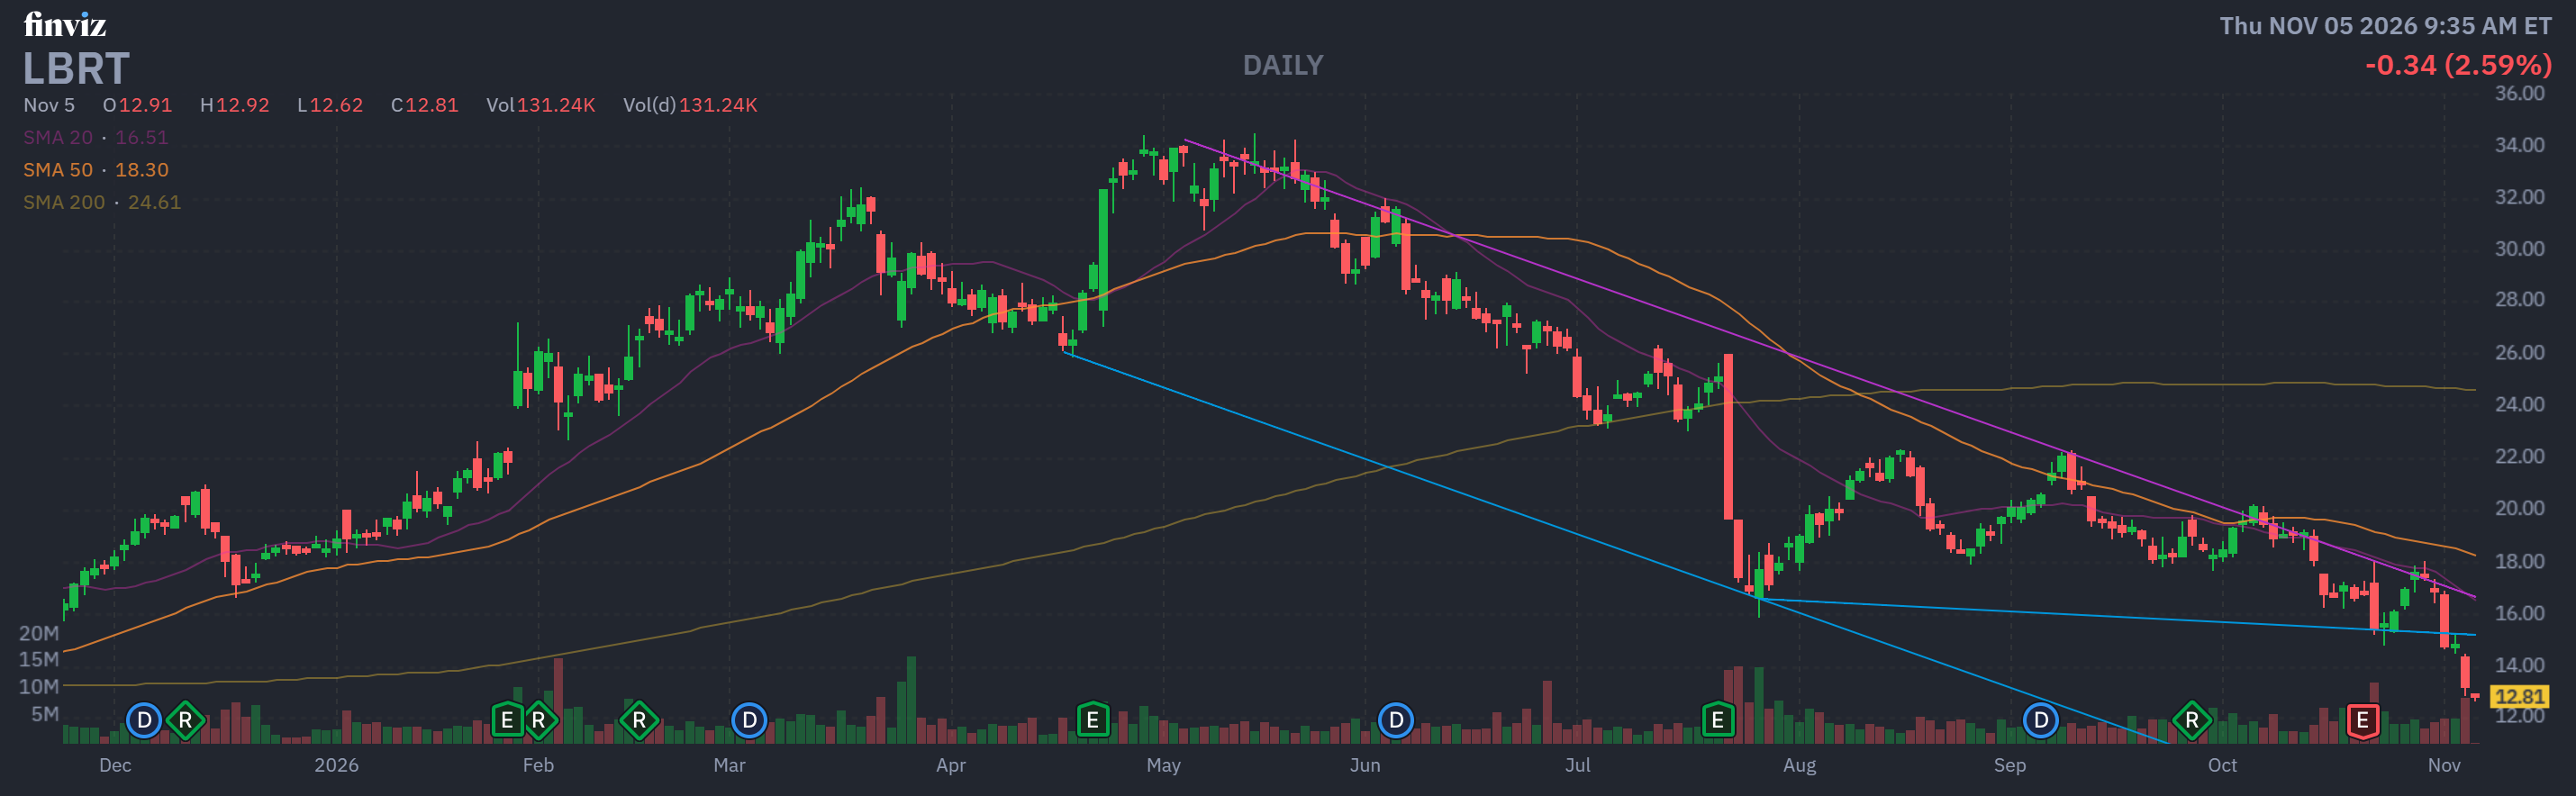
Name: Ken Babcock
Position: Director
Transaction Date: 10-26-2026 Shares Bought: 14,500 shares an average price paid of $15.40 for Cost: $223,300
Name: Ron Gusek
Position: CEO and President
Transaction Date: 11-03-2026 Shares Bought: 25,000 shares an average price paid of $15.09 for Cost: $377,335
Company: Liberty Energy Inc. (LBRT)
Liberty Energy Inc., a provider of integrated energy services and technology, offers hydraulic fracturing services and related technologies to North American onshore oil, gas, and enhanced geothermal exploration and production firms. It provides wireline services, proppant delivery solutions, field gas processing and treatment, compressed natural gas distribution, data analytics, and related commodities such as sand mine operations and technology, proppant handling equipment, and logistics software. The company was previously known as Liberty Oilfield Services Inc., but it changed its name to Liberty Energy Inc. in April 2022. Liberty Energy Inc. was founded in 2011 and is based in Denver, Colorado.
Ken Babcock has served as a Director on the Board of Liberty Energy Inc. since 2018. He joined the Board as an independent director, bringing extensive experience in the oilfield services and energy technology industries. Babcock has held several senior leadership positions, including Chief Executive Officer of Abaco Energy Technologies until its acquisition in January 2026, President and CEO of Titan Specialties from 2008 to 2011, and President and CEO of International Logging from 2005 to 2008. Earlier in his career, he held roles at Baker Hughes INTEQ and Noble Technology Services. He holds a Bachelor of Science degree in Geology from Florida State University.
Ron Gusek joined Liberty Energy Inc. in 2014 as Vice President of Technology and Development. He has served as President since November 2016 and was appointed Chief Executive Officer and a member of the Board of Directors in February 2025. With nearly three decades of experience in the oil and gas industry, he has held previous leadership positions at Sanjel Corporation, Zodiac Exploration, and Pinnacle Technologies, focusing primarily on hydraulic fracturing and technology development. He holds a Bachelor of Science degree in Mechanical Engineering from the University of Alberta.
Insomniac Hedge Fund Guy Opinion: On the numbers, this one leans bullish: cheap multiples (6.68x EV/EBITDA, roughly book value), strong cash conversion, a tailwind sector, a credible second growth leg in data-center power, and a DCF plus analyst consensus both pointing well above the current price. But the market isn’t pricing it that way right now, two years of revenue decline, a surprise net loss, and 11.4% short interest tell you the bears have a real case too: this is a cyclical, capital-intensive business at the mercy of oil and gas activity levels, not a company with pricing power. My read: the valuation gap is real, but this is a show-me story, the power pivot needs to land contracts, not just announcements, before the re-rating happens. That call is yours to make with your advisor, but if you’re underwriting this one, underwrite the power business delivering, not the fracking business alone.
With this kind of short interest and a stock sitting near 52-week lows going into year-end catalysts (the December power deal target, the dividend payment), this is also a textbook candidate for an earnings volatility strategy play around the next print, small fortunes get made or lost on earnings day for names like this.
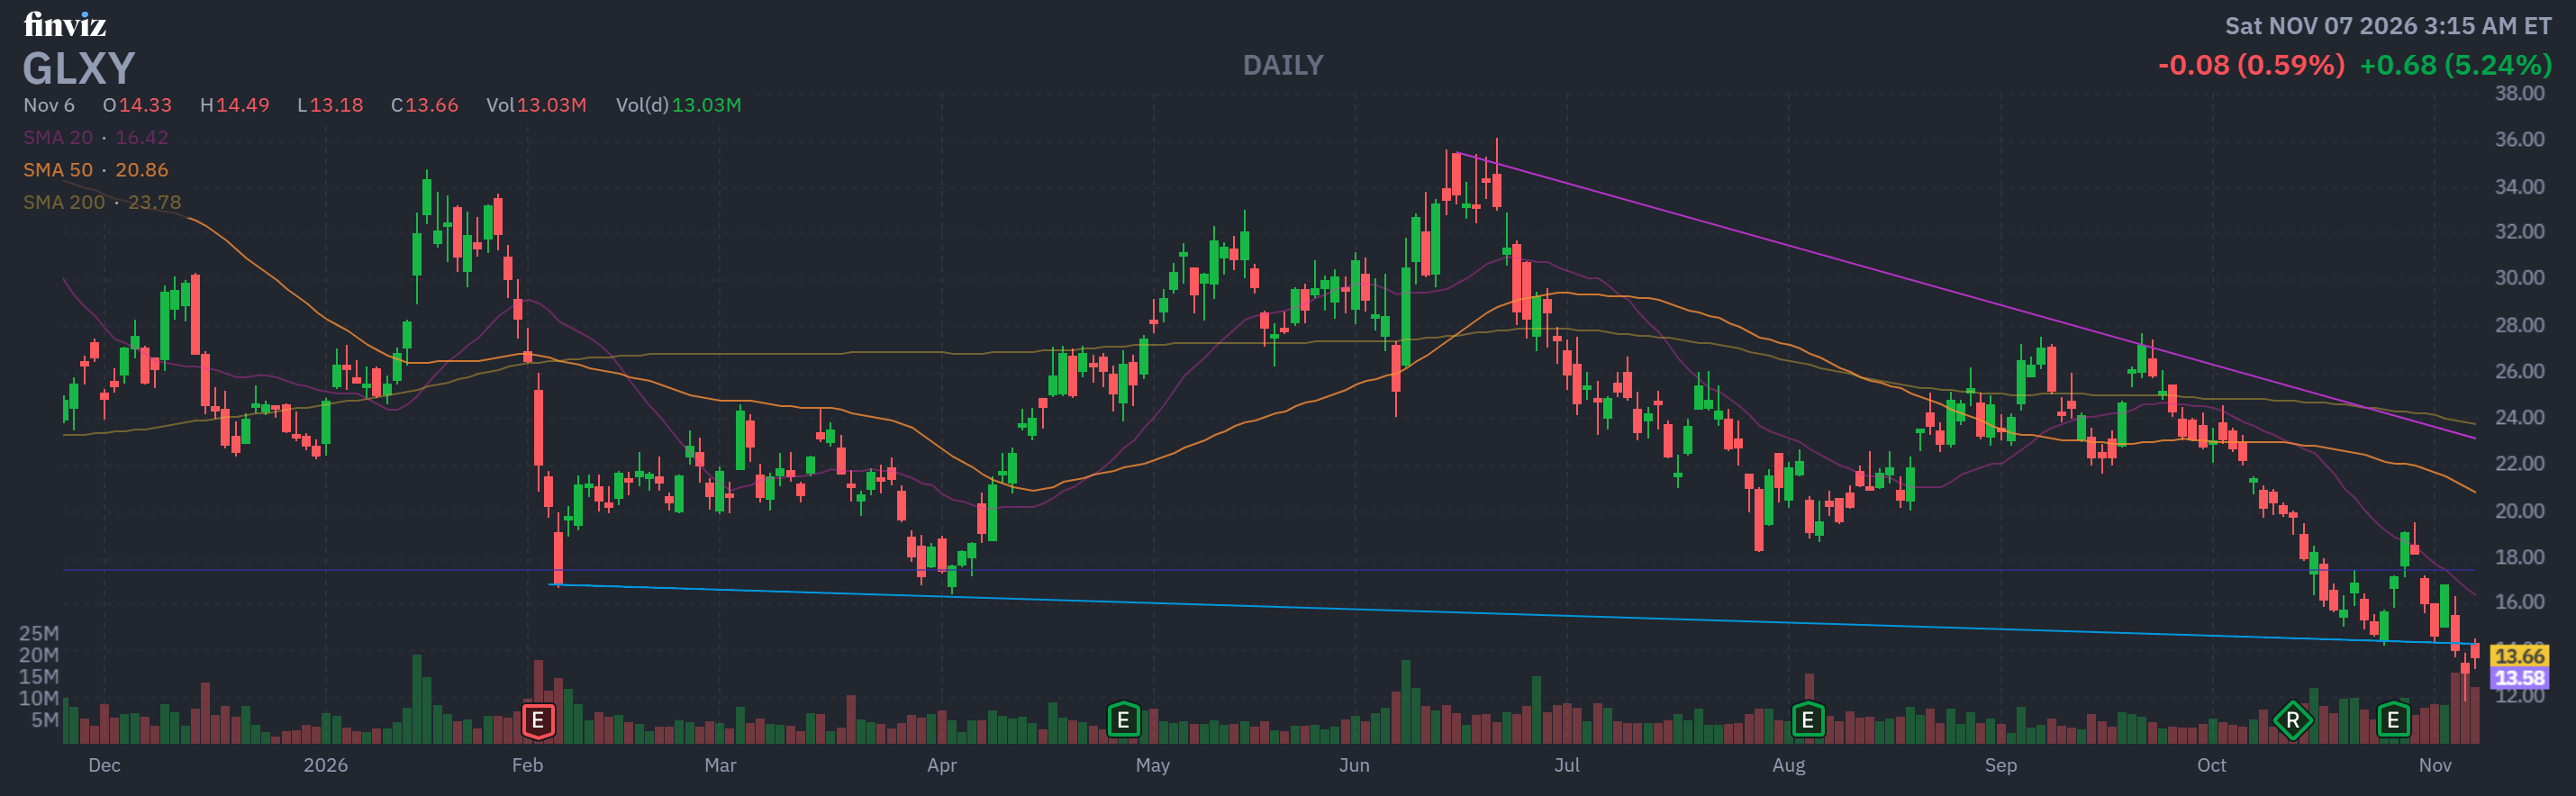
Name: Michael Novogratz
Position: Chief Executive Officer
10% Owner
Transaction Date: 11-05-2026 Shares Bought: 760,000 shares an average price paid of $12.98 for Cost: $9,864,346
Company: Galaxy Digital Inc. (GLXY)
Galaxy Digital Inc. operates in the digital asset and data center infrastructure markets. The company’s digital assets platform provides institutional users with trading, advisory, asset management, staking, self-custody, and tokenization capabilities. In addition, the firm invests in and operates data center infrastructure to enable AI and high-performance computing, addressing the growing demand for scalable energy and compute solutions in the United States. The company was founded in 2018 and is based in New York, with offices around North America, Europe, the Middle East, and Asia.
Michael Novogratz is the Founder and Chief Executive Officer of Galaxy Digital Inc., a position he has held since December 2017, when he founded the company. He has served as a member of Galaxy Digital’s Board of Directors since May 2025, following the company’s corporate reorganization. He previously spent 11 years at Goldman Sachs, where he became a partner, before joining Fortress Investment Group in 2002, where he served as Partner and President. He is also reported as a 10% owner in SEC insider filings. He holds a bachelor’s degree in Economics from Princeton University and served as a helicopter pilot in the U.S. Army.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 score lands at +2.8, a constructive but not screaming composite, built on bullish analyst sentiment, bullish insider activity, bullish sector tailwinds and valuation, offset by a bearish market backdrop and bearish cash flow. Here’s the real tension: trailing profitability is ugly, but the forward story (Helios, GalaxyOne, a CEO buying shares with his own cash) is genuinely interesting, and the DCF, the EV/EBITDA multiple, and the 161% gap to the average analyst target all point the same direction. On these numbers, the case leans bullish for investors who can stomach crypto-cycle volatility and a possible further leg down before the squeeze setup plays out, this is not a widows-and-orphans stock. That decision is yours to make with your advisor.
Given the elevated short interest and the binary nature of the next earnings print, this is a textbook candidate for an earnings volatility strategy, big percentage moves tend to cluster around crypto-sensitive earnings dates. Happy to walk through that if there’s interest.
This is educational, not advice.
Name: Timothy Steven Johnson
Position: Chief Executive Officer
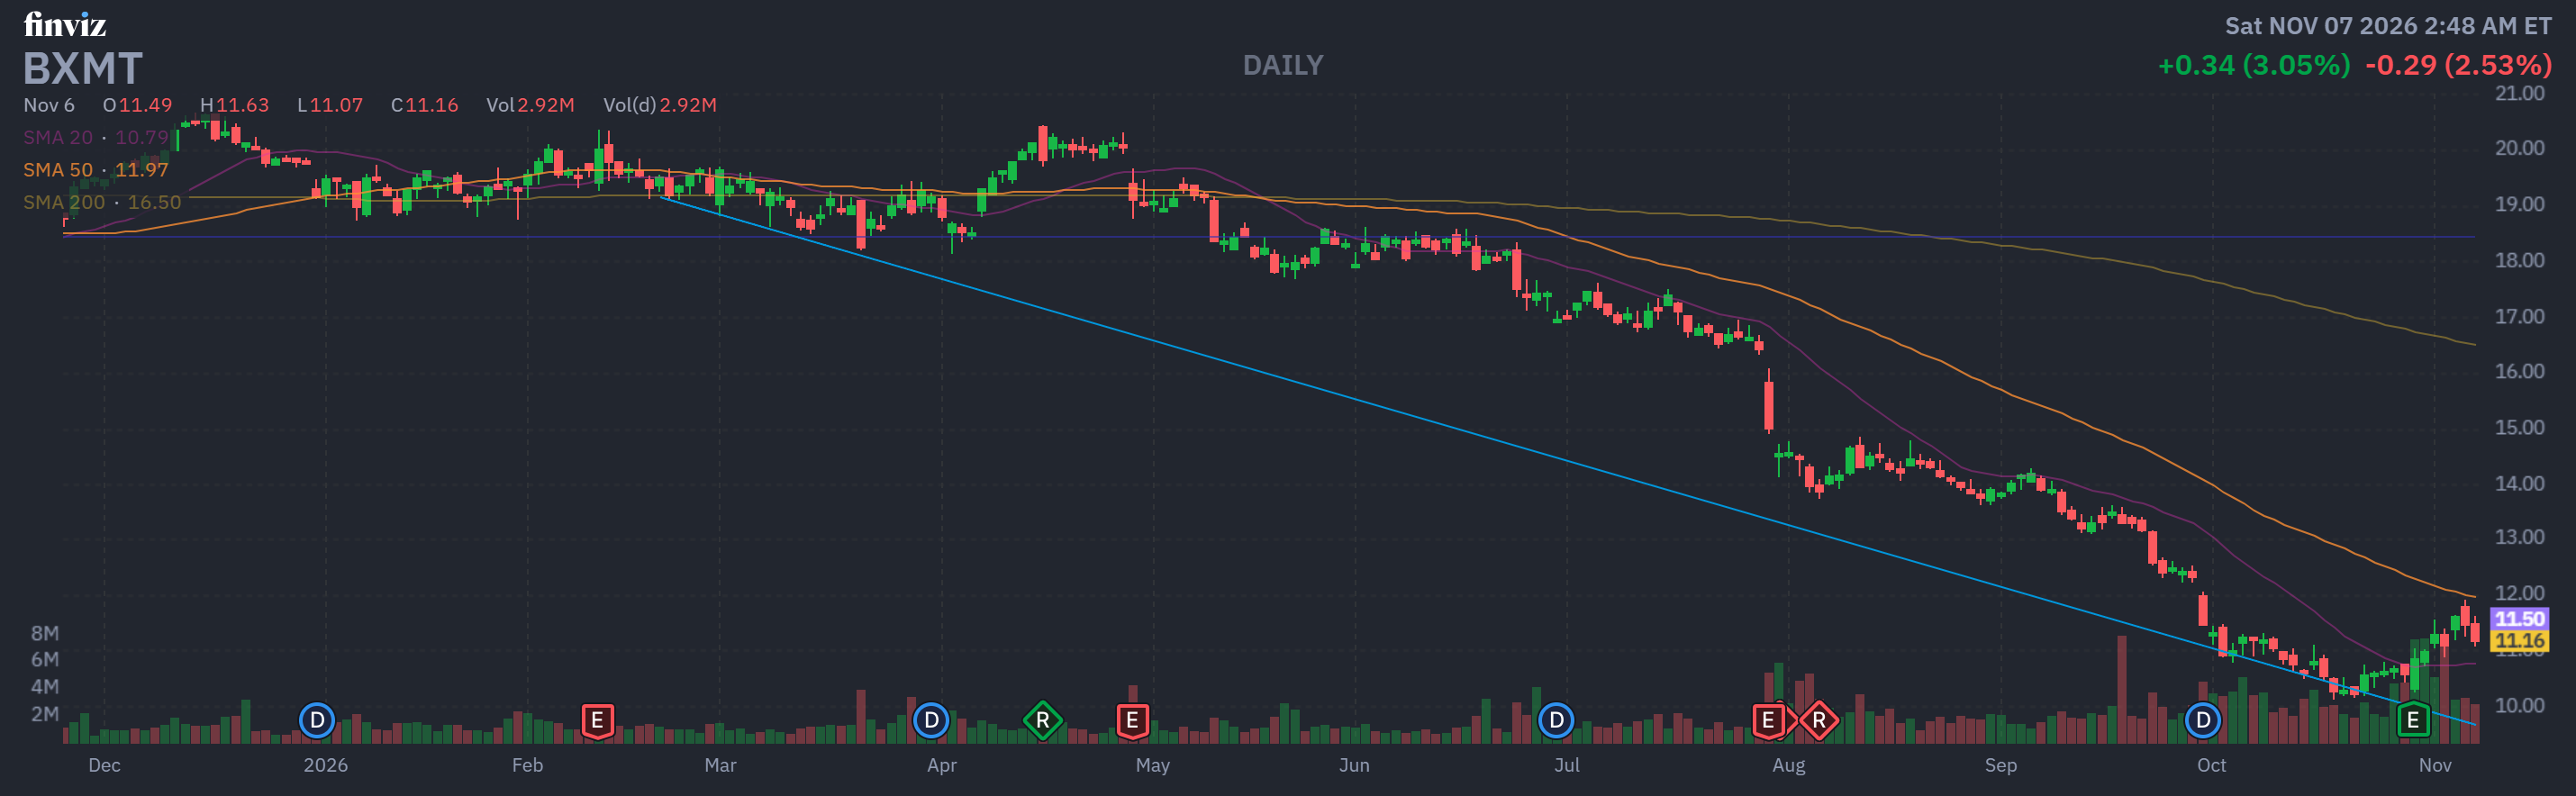
Transaction Date: 11-04-2026 Shares Bought: 90,000 shares an average price paid of $11.50 for Cost: $1,035,351
Name: Henry N. Nassau
Position: Director
Transaction Date: 11-04-2026 Shares Bought: 10,000 shares an average price paid of $11.43 for Cost: $114,291
Company: Blackstone Mortgage Trust Inc. (BXMT)
Blackstone Mortgage Trust, Inc. is a real estate financing business that originates, buys, and manages loans and other debt or credit-oriented investments backed by or related to commercial real estate. The company’s investment portfolio comprises of senior floating rate mortgage loans backed by a first-priority mortgage on commercial real estate assets. It operates in the United States, the United Kingdom, Ireland, Australia, Spain, Sweden, Canada, the rest of Europe, and beyond. It is classified as a real estate investment trust for federal income tax purposes. The company was previously known as Capital Trust, Inc., but changed its name to Blackstone Mortgage Trust, Inc. in May 2013. Blackstone Mortgage Trust, Inc. was founded in 1998 and is located in New York, NY.
Timothy Steven Johnson has been associated with Blackstone Mortgage Trust Inc. since the company’s inception and joined Blackstone Inc. in 2011. He was appointed to the Blackstone Mortgage Trust Inc. Board of Directors in 2023 and became Chair of the Board in 2024. He was appointed Chief Executive Officer of Blackstone Mortgage Trust Inc. effective November 10, 2025, while continuing as Board Chair. He also serves as Global Head of Blackstone Real Estate Debt Strategies, overseeing the firm’s commercial and residential real estate debt investment strategies. Previously, he co-founded BroadPeak Funding and worked in Lehman Brothers’ Global Commercial Real Estate Group. He graduated cum laude with a Bachelor of Arts in Mathematics from the College of the Holy Cross.
Henry N. Nassau has served as a Director on the Board of Blackstone Mortgage Trust Inc. since 2003. He joined the company’s Board as an independent director and has continued serving in that capacity. He is a partner at Dechert LLP, where he has worked since September 2003, and previously served as the firm’s Chief Executive Officer from July 2016 to July 2023. Earlier, he held senior legal and executive positions at Internet Capital Group, including Chief Operating Officer and General Counsel. His professional experience includes corporate law, mergers and acquisitions, securities, and private equity. He graduated cum laude from the University of Pennsylvania and earned his Juris Doctor magna cum laude from Penn State University.
Insomniac Hedge Fund Guy Opinion: This is a wounded animal that’s finally treating its own wounds. The credit cleanup, dividend reset, and loan sales are the right moves, and the stock is statistically cheap at 0.66x book with a Street target implying 36% upside. But “cheap” and “done falling” are different claims, book value just dropped 12% in a quarter and the dividend just got cut more than a third. I lean constructive here on valuation and the aggressive self-correction, but this is a credit-recovery story, not a growth story, and it needs a couple of clean quarters without fresh reserve surprises before the discount closes. Whether to buy, hold, or stay away is a call to make with your own advisor given your income needs and risk tolerance, this isn’t a stock for anyone who can’t stomach more volatility while the cleanup finishes.
Name: Peter Boneparth
Position: Director
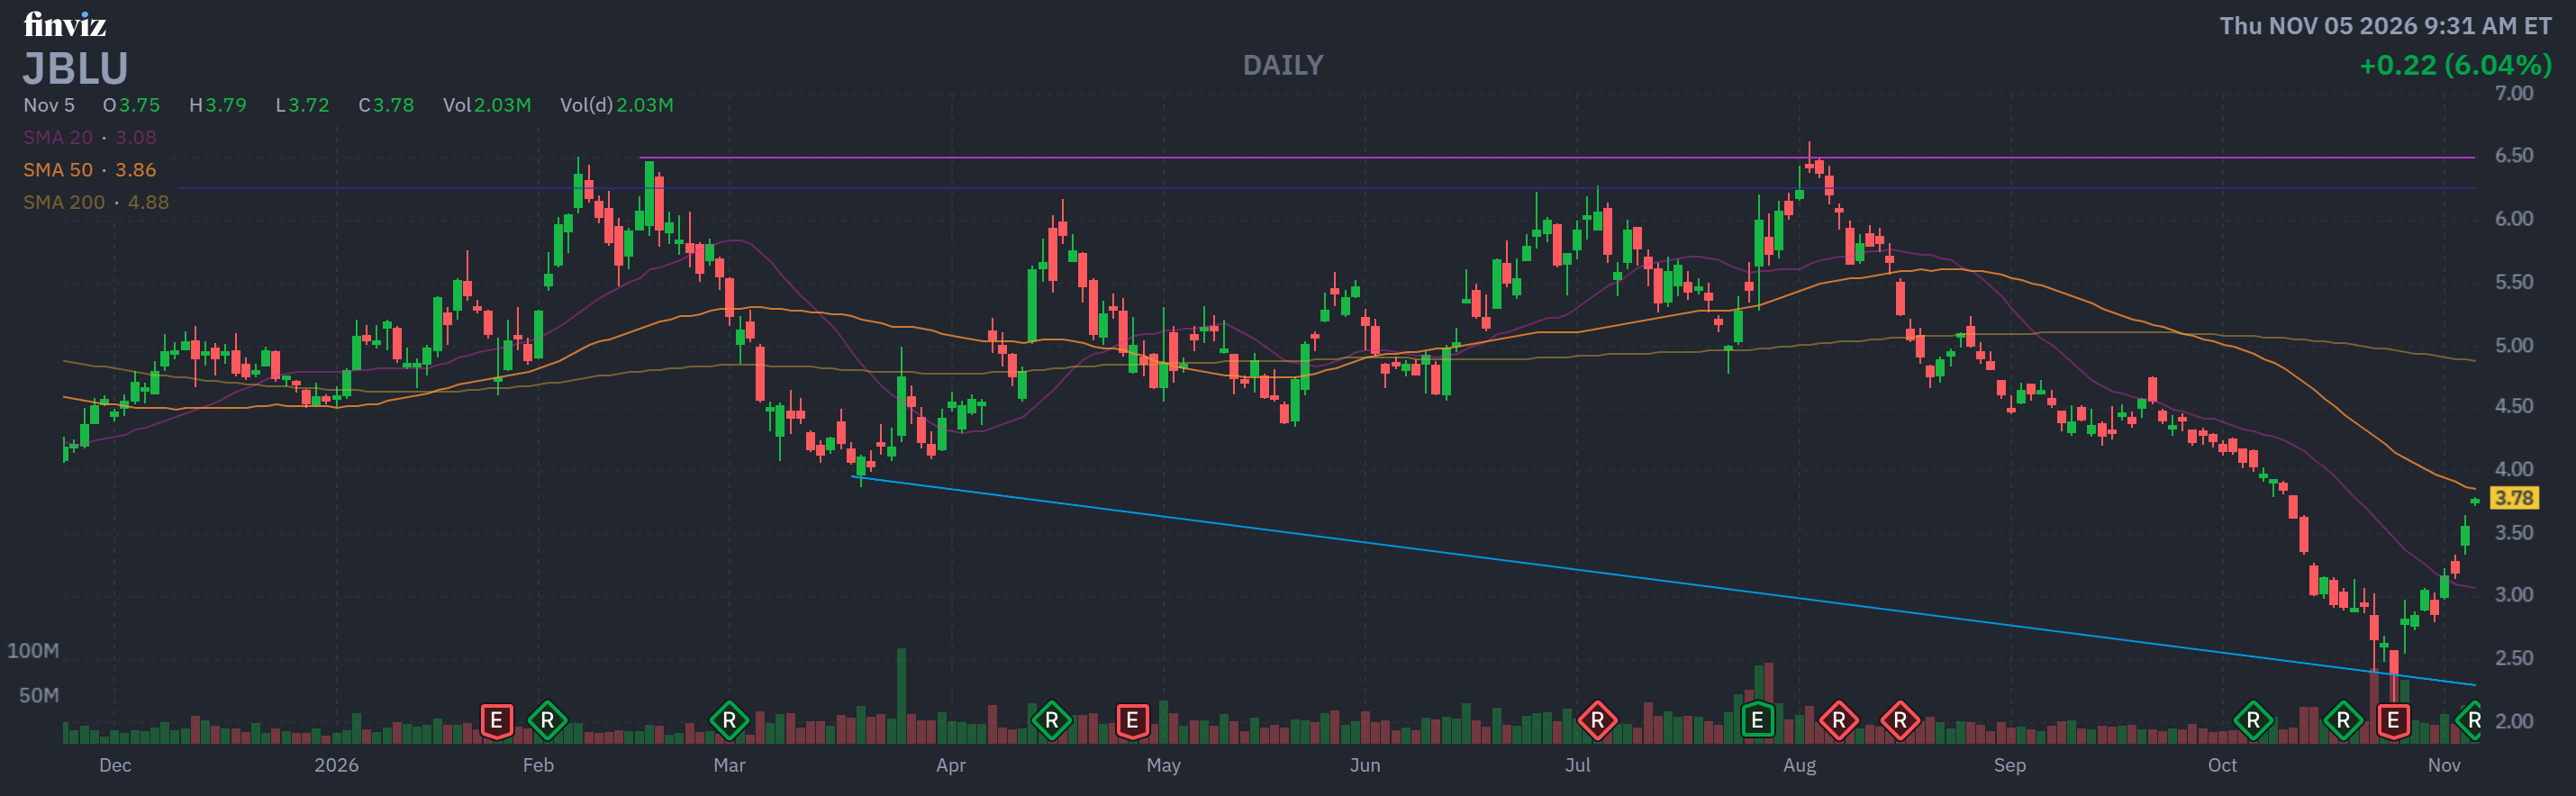
Transaction Date: 10-29-2026 Shares Bought: 100,000 shares an average price paid of $3.00 for Cost: $300,000
Company: Jetblue Airways Corp (JBLU)
JetBlue Airways Corporation is an airline that operates passenger flights within the United States and around the world. The company’s fleet includes Airbus A220, A320, A320 Restyled, A321, A321 with Mint, A321neo, A321neo with Mint, and A321neoLR with Mint aircraft. It serves almost 100 destinations in the United States, the Caribbean, Latin America, Canada, and Europe. The company also manages airport lounges and offers vacation services. JetBlue Airways Corporation was established in 1998 and is based in Long Island City, New York.
Peter Boneparth has served as a Director on the Board of JetBlue Airways Corporation since December 16, 2008, when he was appointed as an independent director. He joined the company through his Board appointment rather than as an employee and became Chairman of the Board in May 2020. Previously, he served as President and CEO of Jones Apparel Group from 2002 to 2007 and held senior positions in investment banking and private equity. He also served as a director of Kohl’s Corporation. He earned a Bachelor of Arts degree from Harvard College and a Juris Doctor degree from Harvard Law School.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite score lands at -0.6 (mixed to neutral), with insider buying (+1, bullish) and PEG ratio (+1, bullish) offset by weak cash flow (-1, bearish) and soft analyst sentiment (-1, bearish). This is a battered stock enjoying a fuel-price relief rally and a confidence-boosting insider buy, not a company that has fixed its fundamentals. Revenue is shrinking, cash is burning, and the entire bull case rests on a 2027-2028 turnaround plan management hasn’t delivered yet. The 30%-plus short interest means squeezes are real and can be sharp, but squeezes aren’t investment theses. This is a speculative trade on turnaround execution and oil prices, not a buy-and-hold case on the numbers in front of us today, that call is yours to make with your advisor given your own risk tolerance and time horizon.
Given the elevated volatility here, this is a textbook candidate for an earnings volatility strategy (EVS), the pricing around JetBlue’s next earnings date is already reflecting outsized moves. Happy to walk through that setup if there’s interest.
This blog is solely for educational purposes and the author’s own amusement. IT IS NOT INVESTMENT ADVICE. Think of the blog as part of my personal investment journal that I am willing to share with the DIY investor. We could be long, short, or have no position at all in any of the stocks mentioned and express no written or implied obligation to disclose any of that. Nothing contained here constitutes a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal, and past performance is not indicative of future results.
“The insomniac hedge fund guy” is a moniker Harvey Sax, the portfolio manager for The Insiders Fund” has used from time to time on email, blog ,and social media posts. While Mr. Sax is the portfolio manager of The Insiders Fund, these posts are not communications from, nor endorsed by, Alpha Wealth Funds, LLC or any of its managed funds. References to Alpha Wealth Funds or its affiliates are for identification only and do not imply sponsorship or approval.
All company names, logos, and trademarks belong to their respective owners. The use of company logos is solely for descriptive and illustrative purposes under fair use. Any information provided is based on publicly available data and should not be considered financial, investment, or legal advice. Readers should conduct their own research or consult with a professional before making any investment decisions. Insiders sell the stock for many reasons, but they generally buy for just one – to make money. You’ve always heard the best information is inside information. Everyone with any stock market experience pays close attention to what insiders are doing. After all, who knows a business better than the people running it? Officers, directors, and 10% owners are required to inform the public through a Form 4 Filing of any transaction, buy, sell, exercise, or any other within 48 hours of doing so.
This info is available for free from the SEC’s Web site, Edgar, although we subscribe to SECForm4 as they provide a way to manage and make sense of the vast realms of data. I’ve tried a lot of vendors. SECForm4 is one of the smaller ones, but I like supporting Frank. He is not arrogant. He’s helpful and has great prices. He also trades on his own data, so I like people that eat what they kill. The bar is different from selling because the natural state of management is to be a seller. This is because most companies provide significant amounts of management compensation packages as stock and options. Therefore, we analyze unusual patterns with selling, such as insiders selling 25 percent or more of their holdings or multiple insiders selling near 52-week lows. Another red flag is large planned sale programs that start without warning. Unfortunately, the public information disclosure requirements about these programs, referred to as Rule 10b5-1, are horrendously poor. Also, planned sales that pop up out of nowhere are basically sales and are seeking cover under this corporate welfare loophole.
I also generally ignore 10 percent shareholders as they tend to be OPM (other people’s money) and perhaps not the smart money on which we are trying to read the tea leaves. I say generally because some 10% shareholders are great investor, think Warren Buffett and others. Of course, insiders can also be wrong about their Company’s prospects. Don’t let anyone fool you into believing they never make mistakes. Do your own analysis. They can easily be wrong, and in many cases, maybe most cases, have no more idea what the future may hold than you or me. In short, you can lose money following them. We have, and we curse aloud; what were they thinking!
We like Fly on the Wall for keeping up with what events might be happening, analysts’ comments, and whatever else could be moving the stock. Dow Jones news service is an essential tool, but many services pick up their feed like they do Bloomberg. My assistant probes the 10k for a reasonable description of the business. I’ve found that to be the most accurate and succinct place to find out what a business actually does.
For more, please visit out website at https://insomniachedge.com/