This week’s market action sent a clear signal: the equal-weighted index (RSP) rose 2% while the S&P 500 dipped 0.57%, signaling a rotation out of tech and into everything else.
However, I am skeptical about the sustainability of this trend, as market internals remain weak and insiders continue to sit on the sidelines. Even as the blackout period lifts, animal spirits have yet to materialize. The market is currently punishing hyper-scalers for spending their free cash flow—and then some—on an unprecedented data center buildout. One has to wonder if this spending is driven by genuine demand or is merely a high-stakes corporate vanity project.
Alphabet suffered its worst day as a public company after Q3 earnings highlighted disappointing monetization, with the high-margin “golden goose” of search taking a back seat to capital-intensive cloud investments. A nearly 15% swoon over two days might have been mitigated had the company utilized its SpaceX stake to fund these AI ambitions.
Intel fared even worse, killing its stock price with a dismal outlook for the critical PC sales quarter, citing high memory prices. While Amazon fared better than its peers, the broader AI trade is becoming increasingly difficult to navigate. As a result, it is more critical than ever to scour the tea leaves left behind by corporate insiders.
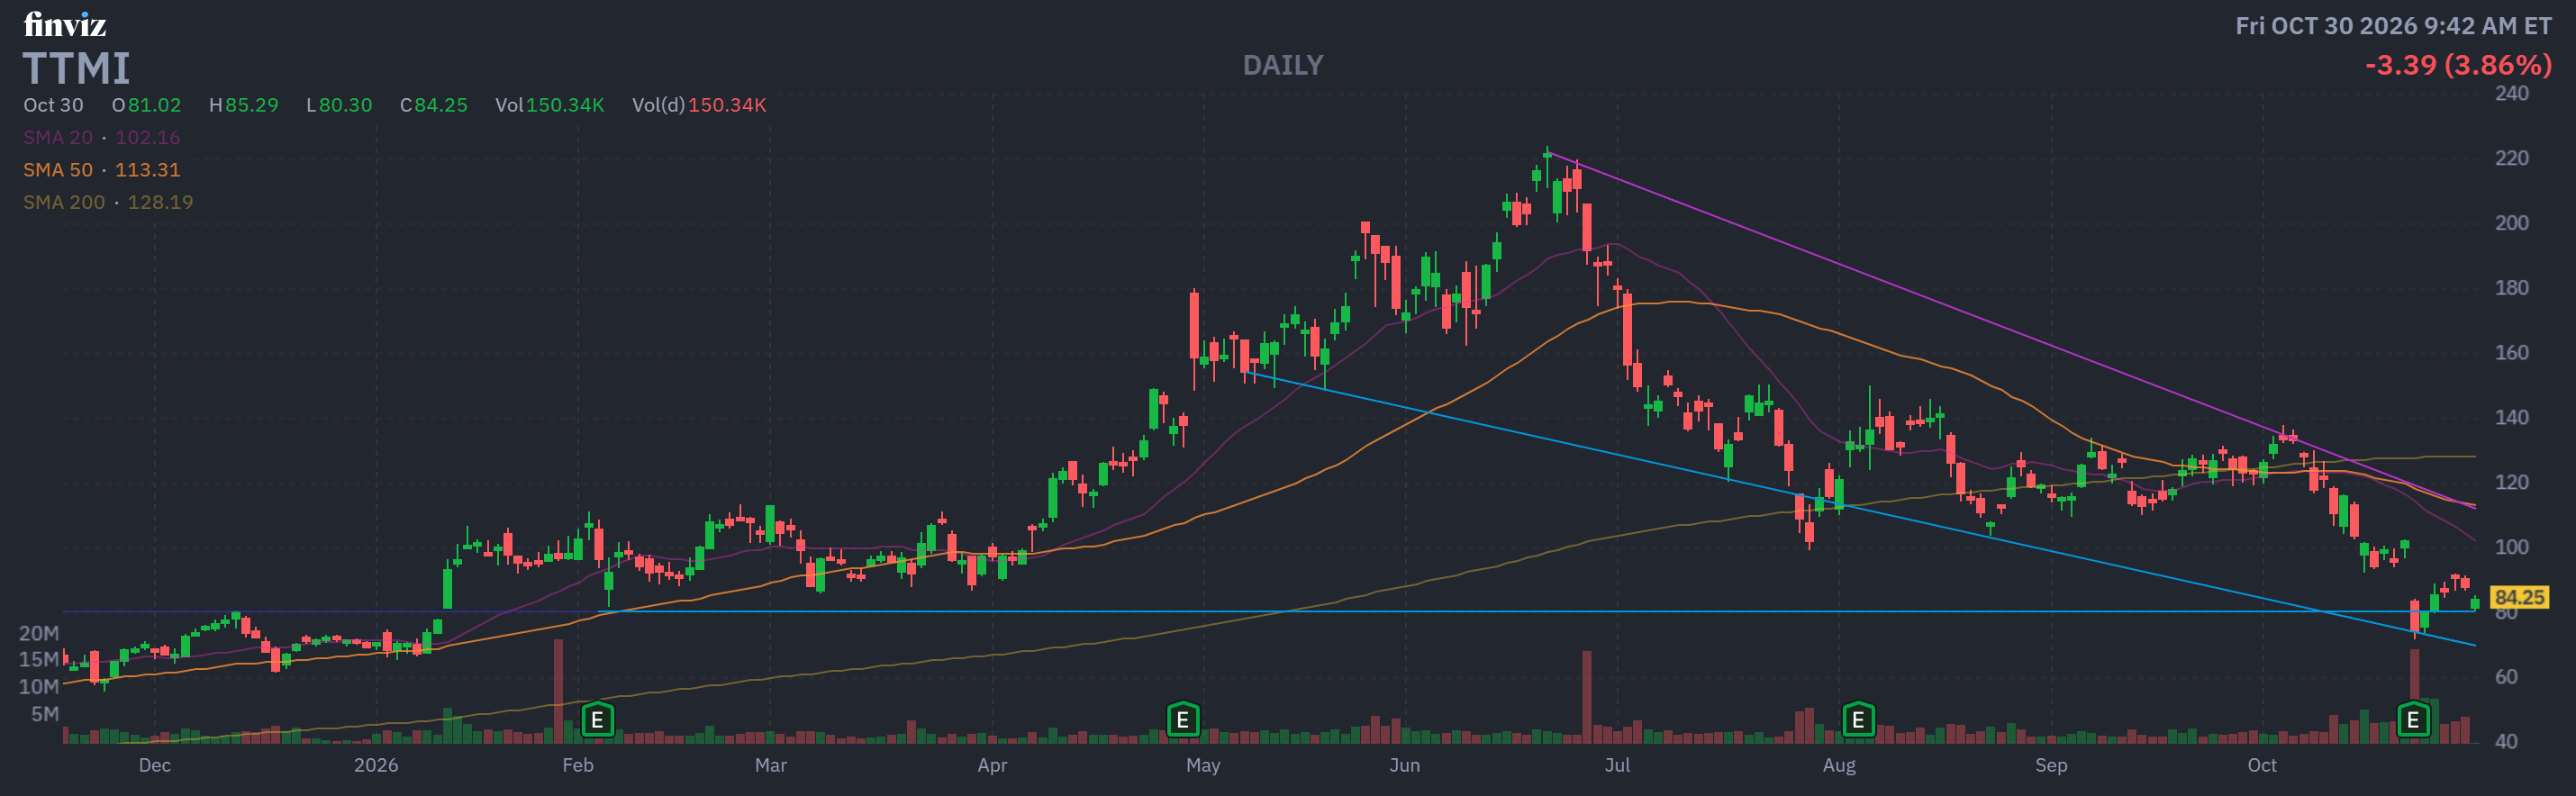
Name: Wajid Ali
Position: Director
Transaction Date: 10-28-2026 Shares Bought: 10,000 shares an average price paid of $90.25 for Cost: $902,461
Name: Edwin Roks
Position: President and CEO
Transaction Date: 10-28-2026 Shares Bought: 5,000 shares an average price paid of $88.07 for Cost: $440,350
Company: TTM Technologies Inc. (TTMI)
TTM Technologies, Inc. is a global technology company that specializes in mission systems, radio frequency components, microwave assemblies, printed circuit boards, and advanced substrates. It operates in three segments: aerospace and defense, commercial, and RF and specialty components. The company offers designed systems, RF and microwave assemblies, ceramic components, multi-chip modules, beamforming networks, and PCB design and testing services. Its technologies are useful for applications such as aircraft radar, marine surveillance, counter-drone systems, communications, air traffic management, and advanced air mobility. TTM serves the aerospace and defense, data centers, automotive, medical, industrial, and networking areas, serving OEMs, government agencies, electronics makers, and distributors globally. TTM Technologies, Inc., founded in 1978, is headquartered in Santa Ana, California.
Wajid Ali has served as a Director on the Board of TTM Technologies Inc. since May 9, 2024, when he was appointed as an independent director. He did not join TTM as an employee; his relationship with the company began through his Board appointment. He is the Chief Financial Officer of Lumentum Holdings Inc., overseeing its financial operations, and previously held senior finance leadership roles at Synaptics, Teledyne Technologies, and DALSA Corporation. He also held financial management positions at AMD and ATI. Ali holds a Bachelor of Arts and a Master of Arts in Economics from York University, an MBA from the Schulich School of Business at York University, and CPA and CMA designations.
Edwin Roks joined TTM Technologies Inc. as President and Chief Executive Officer on September 2, 2025, succeeding Thomas T. Edman. On the same date, he was also appointed to the company’s Board of Directors as a Class II director. Before joining TTM, Roks served as Chief Executive Officer of Teledyne Technologies from January 2024 to April 2025 and held several senior leadership positions there, including President of Teledyne Digital Imaging. Earlier in his career, he worked at Philips Research Laboratories and Philips Semiconductor. He holds a Ph.D. in Electronics and Semiconductor Physics from the University of Twente, a Master’s degree in Electrical Engineering from Eindhoven University of Technology, and completed an Executive MBA program at INSEAD.
Insomniac Hedge Fund Guy Opinion: TTMI is a legitimate AI-infrastructure growth story wearing an old-school contract manufacturer’s valuation multiple, with a PEG ratio of 0.36, Perfect 10 composite score of +3.8 (constructive, on the -10 to +10 scale), strong insider buying, and real cash flow backing up the growth, this isn’t vapor. But the October 28% air-pocket on an earnings beat is the market telling you something true: the debt load, the acquisition financing, and rising customer concentration are legitimate risks that could bite if the AI capex cycle so much as hiccups. On the numbers, the case leans bullish for investors who can stomach volatility and a still-cyclical underlying business, this isn’t a widows-and-orphans name. That call on sizing and timing is yours to make with your advisor.
Given how violently this stock has moved around a single earnings print, this is a textbook candidate for an earnings volatility strategy heading into the next report, large percentage moves on earnings day are TTMI’s calling card lately. Happy to walk through that setup if you want it.
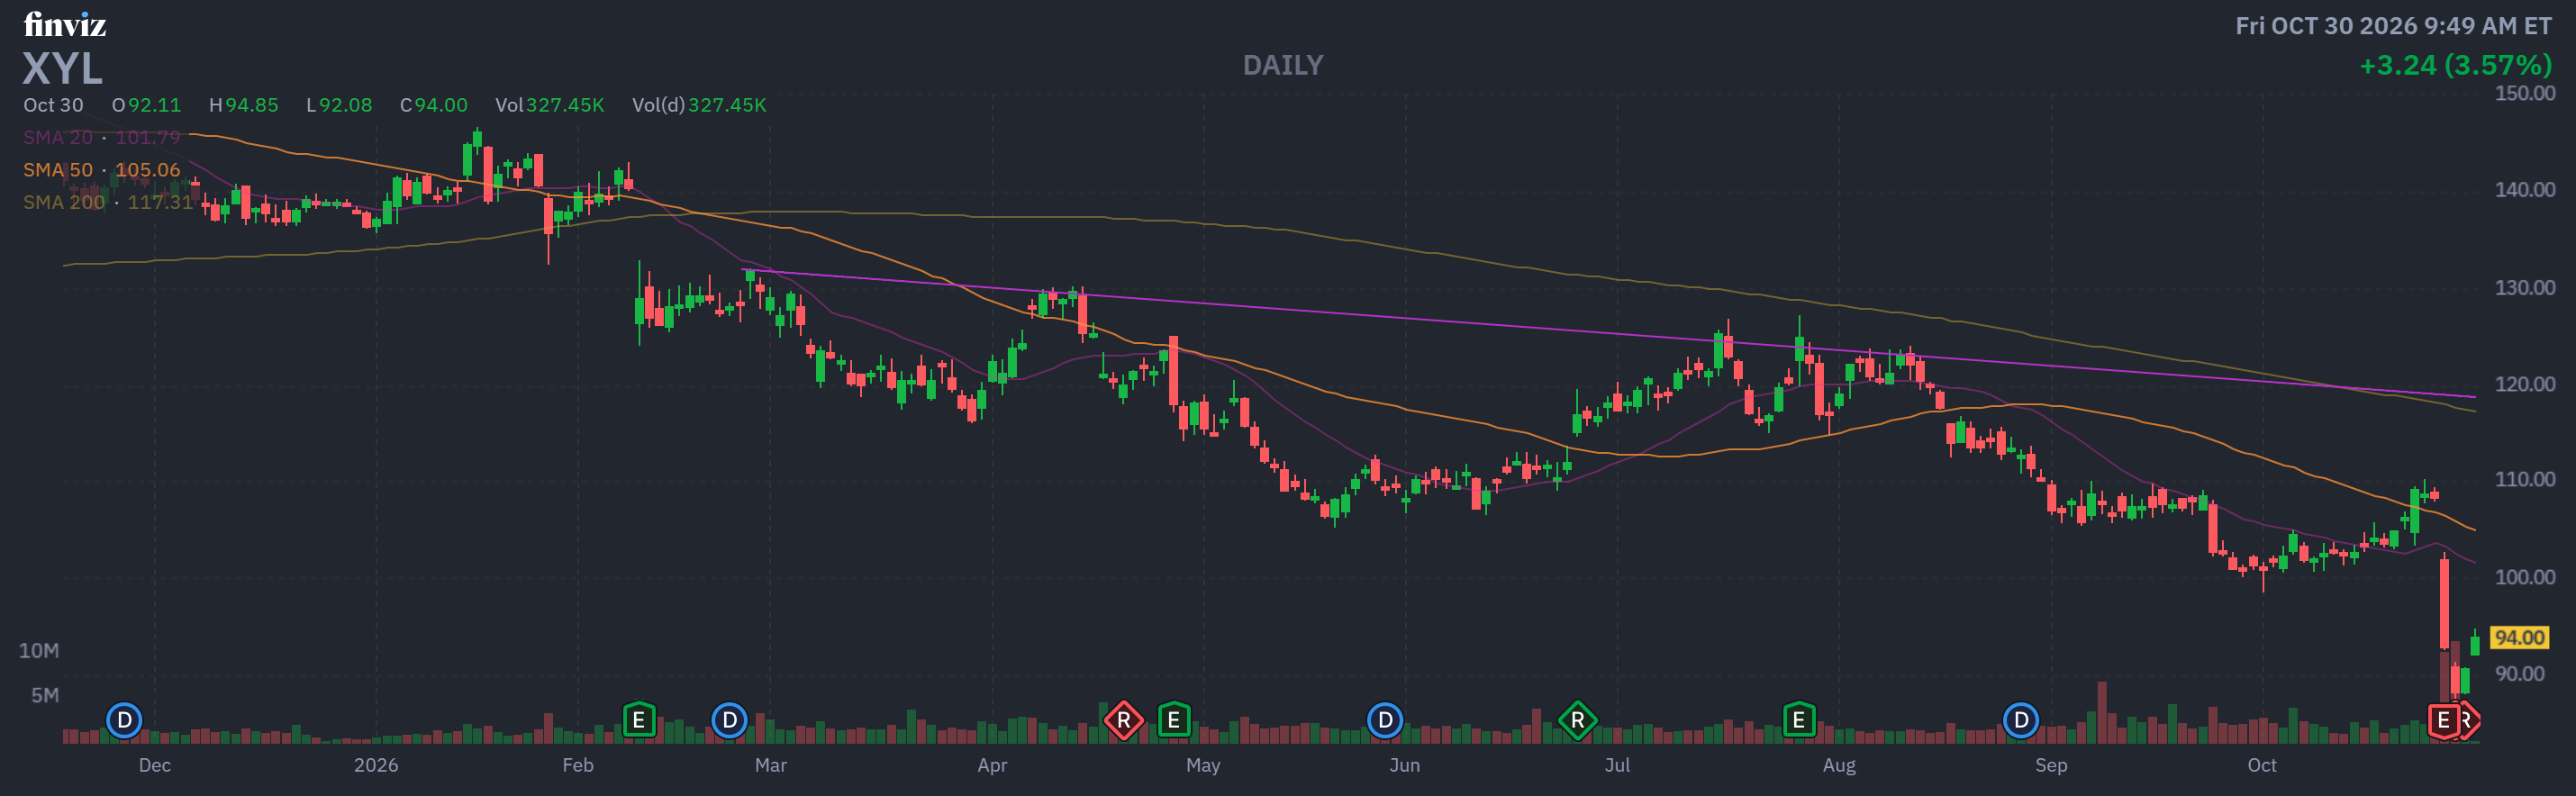
Name: D. Christian Koch
Position: Director
Transaction Date: 10-29-2026 Shares Bought: 11,000 shares an average price paid of $89.60 for Cost: $985,600
Company: Xylem Inc. (XYL)
Xylem Inc. is a global water technology company that designs, manufactures, and services engineered products and solutions for utility, industrial, residential, and commercial applications. The company operates through four segments: Water Infrastructure, Applied Water, Measurement and Control Solutions, and Water Solutions and Services. Its products and services include water, wastewater, and stormwater pumps, filtration and treatment systems, valves, heat exchangers, smart meters, communication devices, sensors, software, data analytics, remote monitoring, and water management solutions. It also provides maintenance, wastewater treatment, environmental remediation, dewatering equipment rentals, and infrastructure services through brands such as Flygt, Goulds Water Technology, Sensus, Godwin, and Xylem Vue. The company was formerly known as ITT WCO, Inc., before changing its name to Xylem Inc. in July 2011. Xylem Inc. was incorporated in 2011 and is headquartered in Washington, District of Columbia.
D. Christian Koch joined Xylem Inc. as an independent Director on August 13, 2026, when he was appointed to the company’s Board of Directors. He joined Xylem in a board capacity rather than as an employee. Koch brings more than 30 years of experience in global industrial businesses and currently serves as Chairman, President and CEO of Carlisle Companies Incorporated, a position he has held since 2016. He joined Carlisle in 2008 and previously held leadership roles at Graco Inc. and H.B. Fuller. He holds a bachelor’s degree from Macalester College and an MBA from the University of Minnesota.
Insomniac Hedge Fund Guy Opinion: Xylem is a good business having a bad quarter, wrapped in a credibility problem. The structural case (water scarcity, aging infrastructure, smart metering, growing backlog) is intact, and at roughly $94 against a DCF fair value near $95-$105, you’re not overpaying. But I’m not calling this a screaming buy today: a guidance cut this sharp combined with active securities investigations means the market is right to demand a discount until management proves the new numbers are real. My lean is a cautious hold, let the next one or two quarters confirm the backlog is actually converting to revenue before treating this dip as a gift rather than a warning.
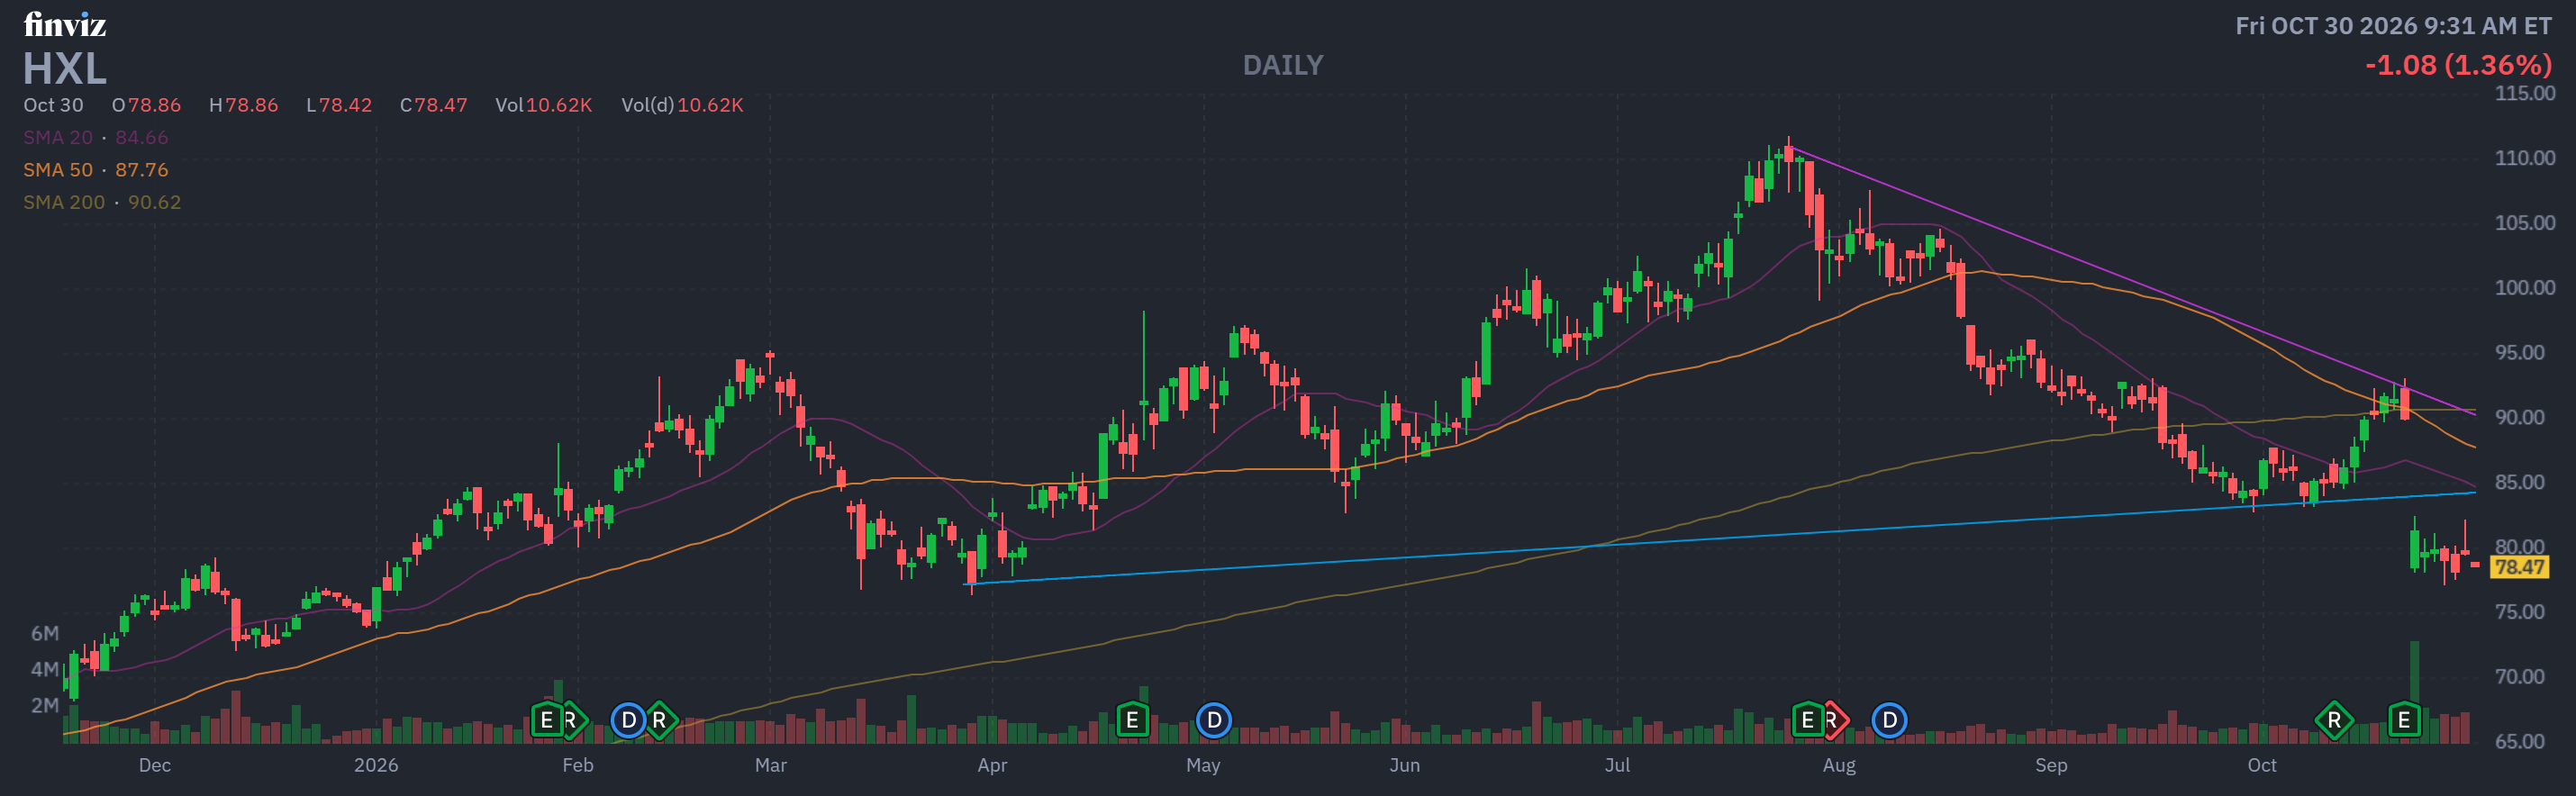
Name: Neal J. Keating
Position: Director
Transaction Date: 10-26-2026 Shares Bought: 3,000 shares an average price paid of $80.67 for Cost: $242,010
Company: Hexcel Corp. (HXL)
Hexcel Corporation develops, manufactures, and markets advanced lightweight composite materials and technologies for aerospace, defense, space, and industrial applications. The company operates through two segments: Composite Materials and Engineered Products. It offers carbon fibers, fabrics, reinforcements, prepregs, honeycomb structures, resins, structural adhesives, laminates, and composite components used in aircraft, rotorcraft, transportation, recreational products, and other industrial applications. Its Engineered Products segment manufactures aircraft structures and components, including wing panels, fairings, flight deck panels, rotorcraft blades, and engine nacelle components. The company also provides electromagnetic interference control materials, dielectric absorber foams, magnetic absorbers, and thermoplastics for commercial and defense applications. Hexcel Corporation was founded in 1946 and is headquartered in Stamford, Connecticut.
Neal J. Keating joined the Board of Directors of Hexcel Corporation on March 3, 2026, and was appointed to its Audit Committee on the same date. He joined Hexcel in a board leadership capacity rather than as an employee. Keating is an experienced aerospace and industrial executive who previously served as Chairman, President and CEO of Kaman Corporation from 2008 to 2020, followed by Executive Chairman until 2021. He also held senior leadership positions at GKN Aerospace and Hughes Supply and has served on the board of Hubbell Incorporated since 2010. He earned a Bachelor of Science degree in Electrical Engineering from the University of Illinois and an MBA from the University of Chicago.
Insomniac Hedge Fund Guy Opinion: HXL is a quality business having an ugly quarter inside an ugly sector. The moat is real, the cash flow is clean, and a director just bought the dip with his own money. But the guidance reaffirmation instead of a raise, combined with industrials-wide weakness, means the stock could stay under pressure near-term even as the long-term aerospace story stays intact. On the numbers, this leans toward a cautious buy for patient investors willing to look past a rough quarter toward the multi-year widebody recovery, not a stock to chase on momentum right now. That call is yours to make with your advisor, especially given the customer concentration risk baked into the business model.
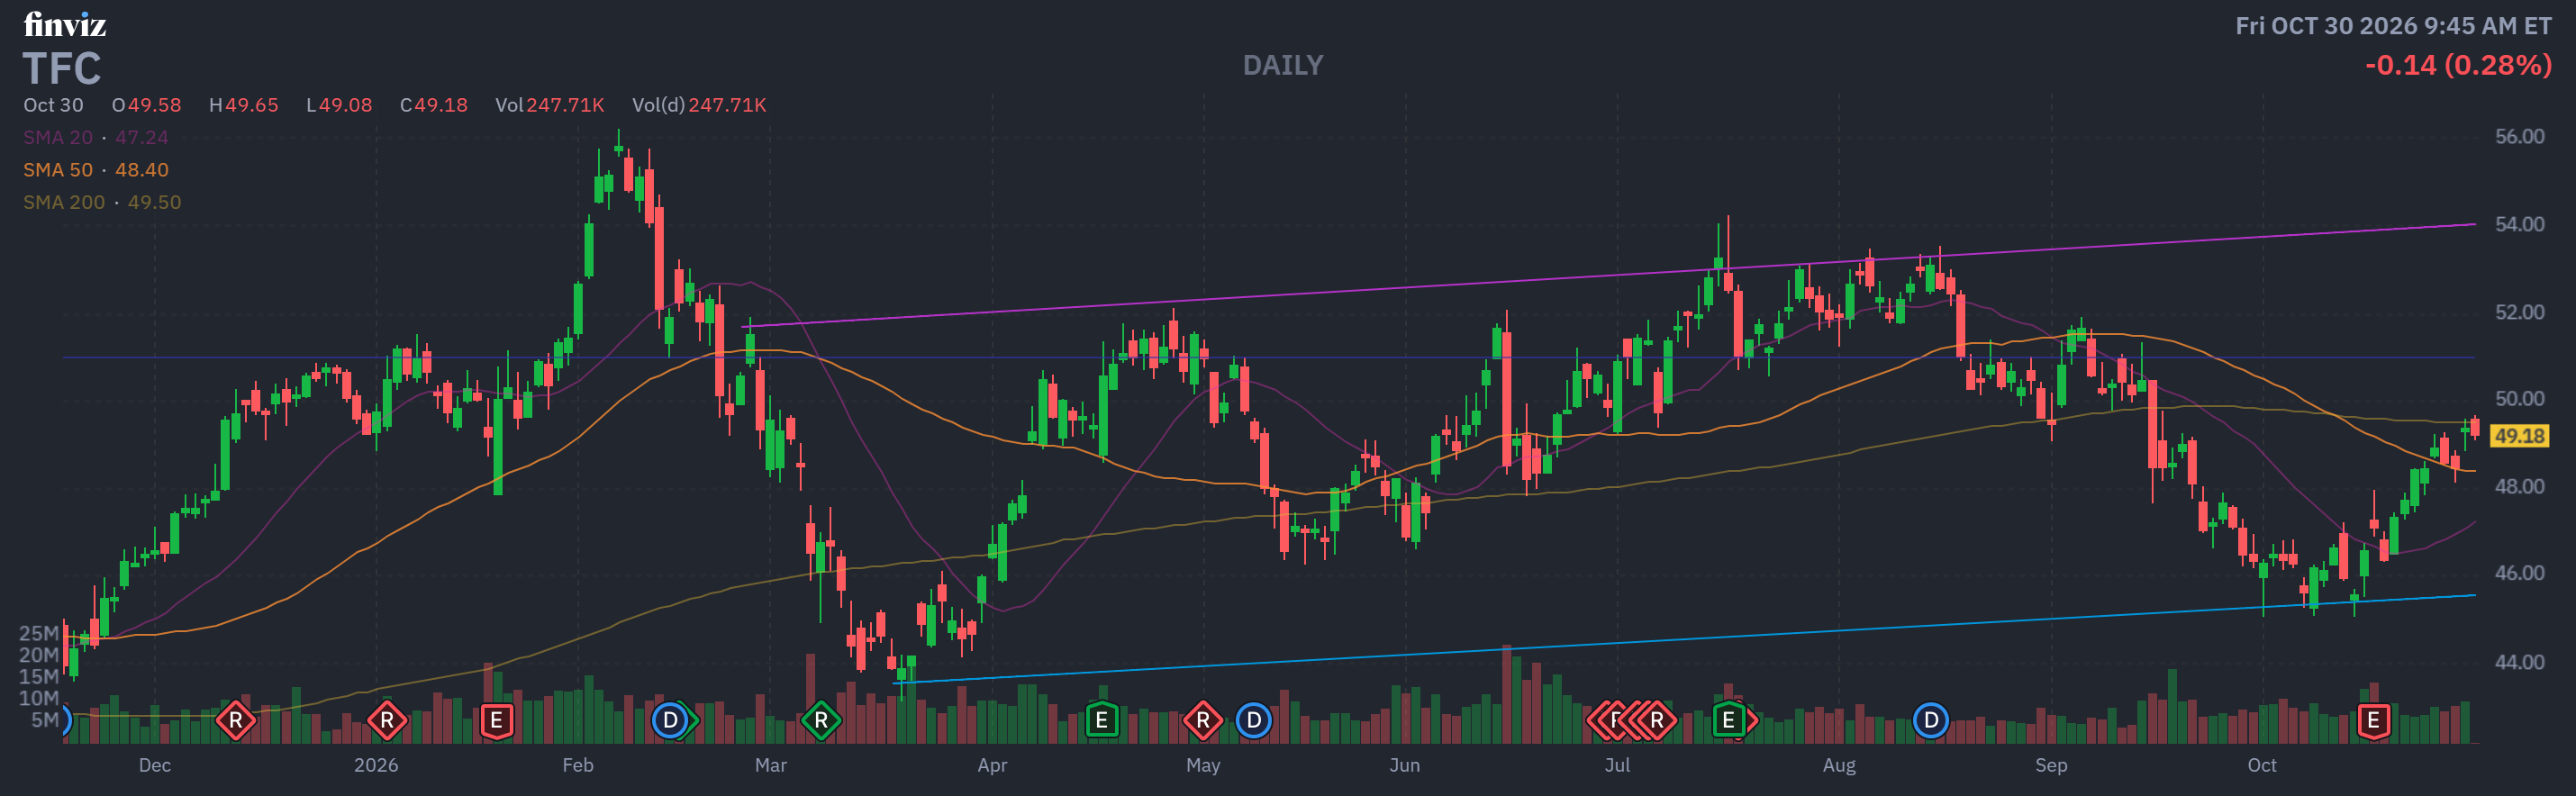
Name: Michael P. Lyons
Position: President and CEO
Transaction Date: 10-28-2026 Shares Bought: 25,000 shares an average price paid of $48.36 for Cost: $1,209,050
Company: Truist Financial Corp. (TFC)
Truist Financial Corporation is a financial services company that provides banking, lending, investment, and trust services across the Southeastern and Mid-Atlantic United States. The company operates through two segments: Consumer and Small Business Banking, and wholesale banking. Its services include checking and savings accounts, certificates of deposit, credit cards, mortgage and commercial lending, asset management, investment banking, wealth management, private banking, treasury services, insurance premium finance, mobile and online banking, and payment solutions. It was formerly known as BB&T Corporation before changing its name to Truist Financial Corporation in December 2019. Truist Financial Corporation was founded in 1872 and is headquartered in Charlotte, North Carolina.
Michael P. Lyons joined Truist Financial Corporation as President and Chief Executive Officer on September 1, 2026, succeeding William H. Rogers Jr. On the same date, he also joined the company’s Board of Directors. He brings more than three decades of experience in financial services, having previously served as CEO of Fiserv from May 2025 to June 2026 and as President of The PNC Financial Services Group from February 2024 to January 2025. Earlier in his career, he held senior leadership positions at Bank of America, Morgan Stanley, and Maverick Capital. He earned a bachelor’s degree from the University of Pennsylvania.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite score lands at +2.4 (Constructive), a mildly bullish read built on positive insider buying, healthy cash flow, and a supportive sector backdrop, offset by neutral valuation and a bearish broader market trend. Truist is a turnaround story that’s actually turning: new management is cutting the dead weight, the CEO just put real money behind it, and the DCF suggests modest undervaluation. But profitability still lags the PNC/USB tier, and GAAP headline numbers remain noisy through 2026. This isn’t a screaming buy, it’s a patient, show-me story with a credible plan and a CEO willing to back it with his wallet. The lean here is cautiously bullish on the restructuring thesis, but the decision on initiating or adding to a position is yours to make with your advisor.
Worth flagging separately: with 2 insider purchases in the last 90 days concentrated around the CEO, that’s a cleaner signal than most regional banks are showing right now.
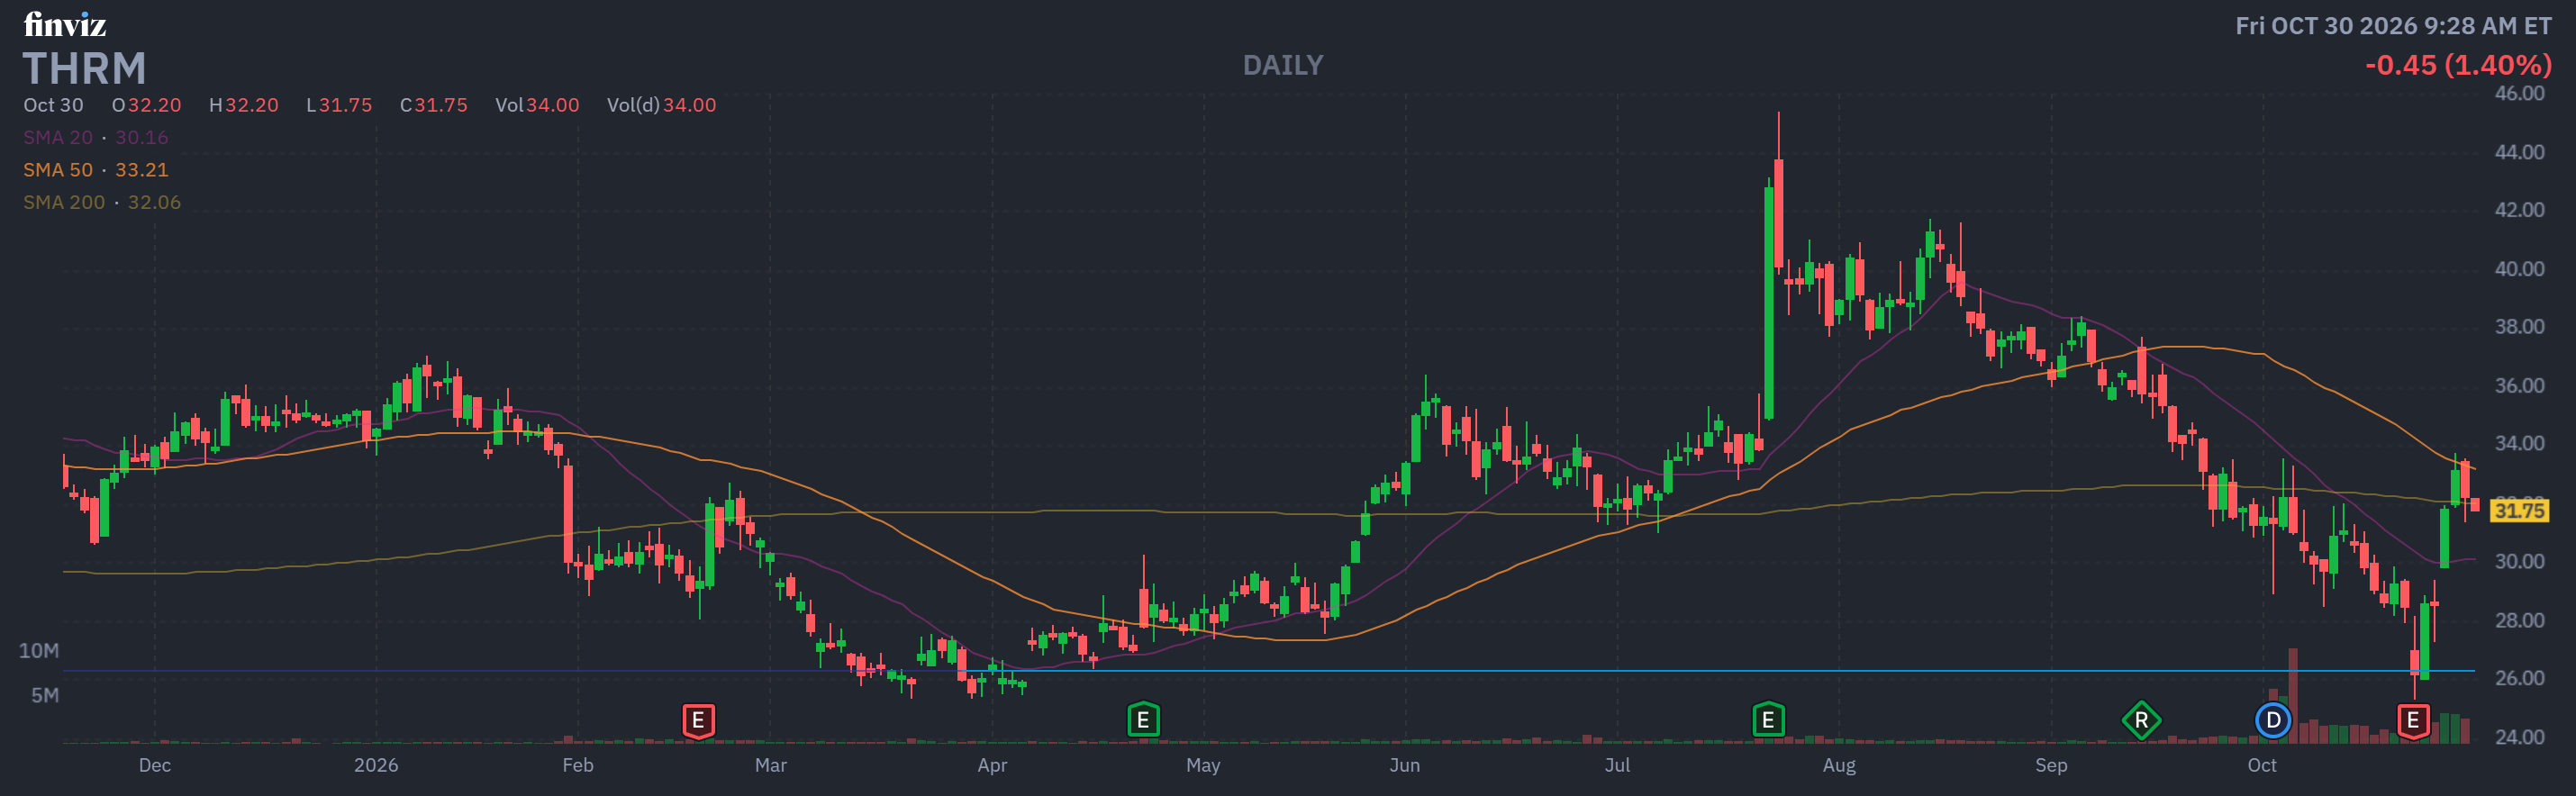
Name: Paul Anthony Mascarenas
Position: Director
Transaction Date: 10-23-2026 Shares Bought: 20,000 shares an average price paid of $26.63 for Cost: $532,600
Company: Gentherm Inc. (THRM)
Gentherm Incorporated designs, develops, manufactures, and sells thermal management and pneumatic comfort technologies for the automotive and medical industries worldwide. The company operates through Automotive and Medical segments, offering climate comfort systems, heated seats and steering wheels, electronic control units, pneumatic lumbar support, massage systems, battery thermal management solutions, automotive cables, and valve systems. Its medical products include patient temperature management systems marketed under the Blanketrol and Astotherm brands for warming and cooling therapies in intensive care and surgical procedures. The company serves automotive manufacturers, tier-one suppliers, and medical industry customers across global markets. Gentherm Incorporated was formerly known as Amerigon Incorporated before changing its name in September 2012. Gentherm Incorporated was incorporated in 1991 and is headquartered in Novi, Michigan.
Paul Anthony Mascarenas has served as a director on the Board of Gentherm Inc.since October 1, 2026, following the completion of Gentherm’s combination with Modine’s Performance Technologies business. He did not join Gentherm as an employee; his appointment was to the Board of Directors, where he also joined the Technology Committee. Mascarenas previously spent more than three decades at Ford Motor Company, from 1982 to 2014, serving in several engineering leadership roles, including Chief Technical Officer. He is also a Venture Partner at Fontinalis Partners and serves on the boards of other companies. He holds a Bachelor of Science degree in mechanical engineering from King’s College, University of London, and an honorary doctorate from Chongqing University.
Insomniac Hedge Fund Guy Opinion: Gentherm is a cyclical auto supplier wearing a growth-stock valuation multiple, carrying real integration risk from the Modine deal, but backed by genuine insider buying, a Buy-rated analyst consensus, and a DCF that pencils out meaningfully above today’s price. The case leans bullish on a multi-year horizon if the Modine integration goes smoothly and EV thermal management scales, but the GAAP loss, decelerating growth, and customer concentration keep this from being a slam dunk. This reads as a show-me story: the market is paying up for a 2027 turnaround that hasn’t fully shown up in the numbers yet.
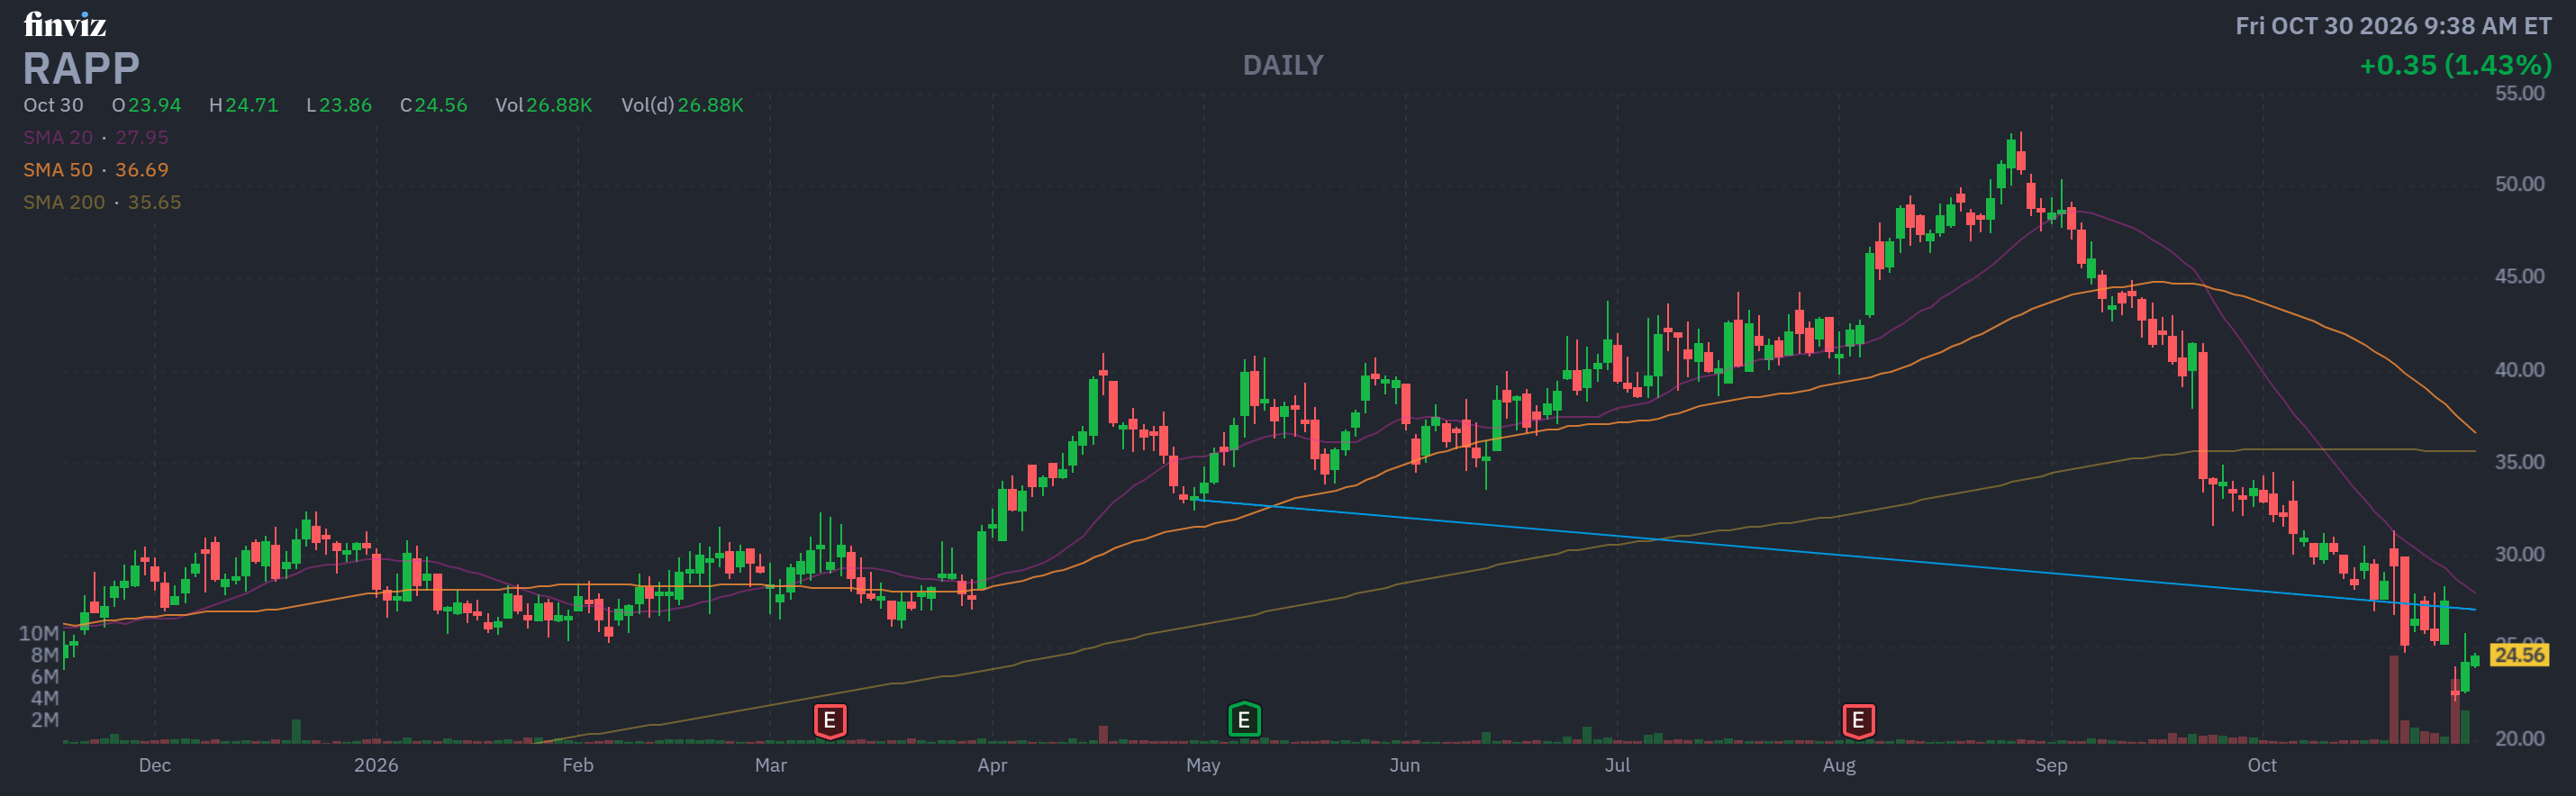
Name: John Maraganore
Position: Director
Transaction Date: 10-22-2026 Shares Bought: 9,411 shares an average price paid of $26.45 for Cost: $248,891
Name: James Healy
Position: Director
Transaction Date: 10-28-2026 Shares Bought: 969,480 shares an average price paid of $21.00 for Cost: $20,359,080
Company: Rapport Therapeutics Inc. (RAPP)
Rapport Therapeutics, Inc. is a clinical-stage biopharmaceutical company focused on discovering and developing small-molecule medicines for patients with central nervous system disorders. The company’s lead product candidate, RAP-219, is an investigational medicine designed to target specific AMPA receptors for the treatment of focal epilepsy and other neurological conditions, including peripheral neuropathic pain and bipolar disorder. It also develops nicotinic acetylcholine receptor programs targeting chronic pain, migraine, and hearing and vestibular disorders. The company was formerly known as Precision Neuroscience NewCo, Inc. before changing its name to Rapport Therapeutics, Inc. in October 2022. Rapport Therapeutics, Inc. was incorporated in 2022 and is headquartered in Boston, Massachusetts.
John Maraganore has served as a Director on the Board of Rapport Therapeutics Inc. since March 2024. He joined the company’s Board of Directors to contribute his extensive experience in biotechnology, pharmaceutical innovation, and corporate leadership. Maraganore previously served as the founding Chief Executive Officer of Alnylam Pharmaceuticals from 2002 to 2021, helping establish the company as a leader in RNA interference therapeutics. He currently serves as a Venture Partner at ARCH Venture Partners and Atlas Venture and advises life sciences businesses. He holds a Bachelor of Arts in Biological Sciences and both a Master of Science and a Ph.D. in Biochemistry and Molecular Biology from the University of Chicago.
James I. Healy has served as a Director on the Board of Rapport Therapeutics Inc. since August 2023. He joined the company’s Board as an experienced biotechnology investor, bringing extensive knowledge of drug development and life sciences. He has served as Managing Partner of Sofinnova Investments since June 2000, where he focuses on investing in innovative healthcare companies. He previously held positions at Bayer and Sanderling Ventures and has served on the boards of several biotechnology companies. He earned bachelor’s degrees in Molecular Biology and Scandinavian Studies from the University of California, Berkeley, and both an M.D. and a Ph.D. in Immunology from Stanford University School of Medicine.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite reads +1.0 (mixed/neutral), a scorecard with a bullish Phase 2 catalyst, a bullish Strong Buy analyst consensus, and a bullish sector tailwind pulling against bearish cash flow and a bearish broader market trend. This is a binary, single-asset biotech bet dressed up with a healthy cash cushion and a real clinical win already banked. The data readout is legitimate, the funding is secured, and the sector has wind at its back, but there is no revenue, no moat beyond unproven IP, and the entire thesis rides on a 2027 Phase 3 result nobody can know today. This leans speculative-bullish on the strength of the clinical data and analyst enthusiasm, but it’s a binary science bet, not a steady compounder, size it (if at all) like one.
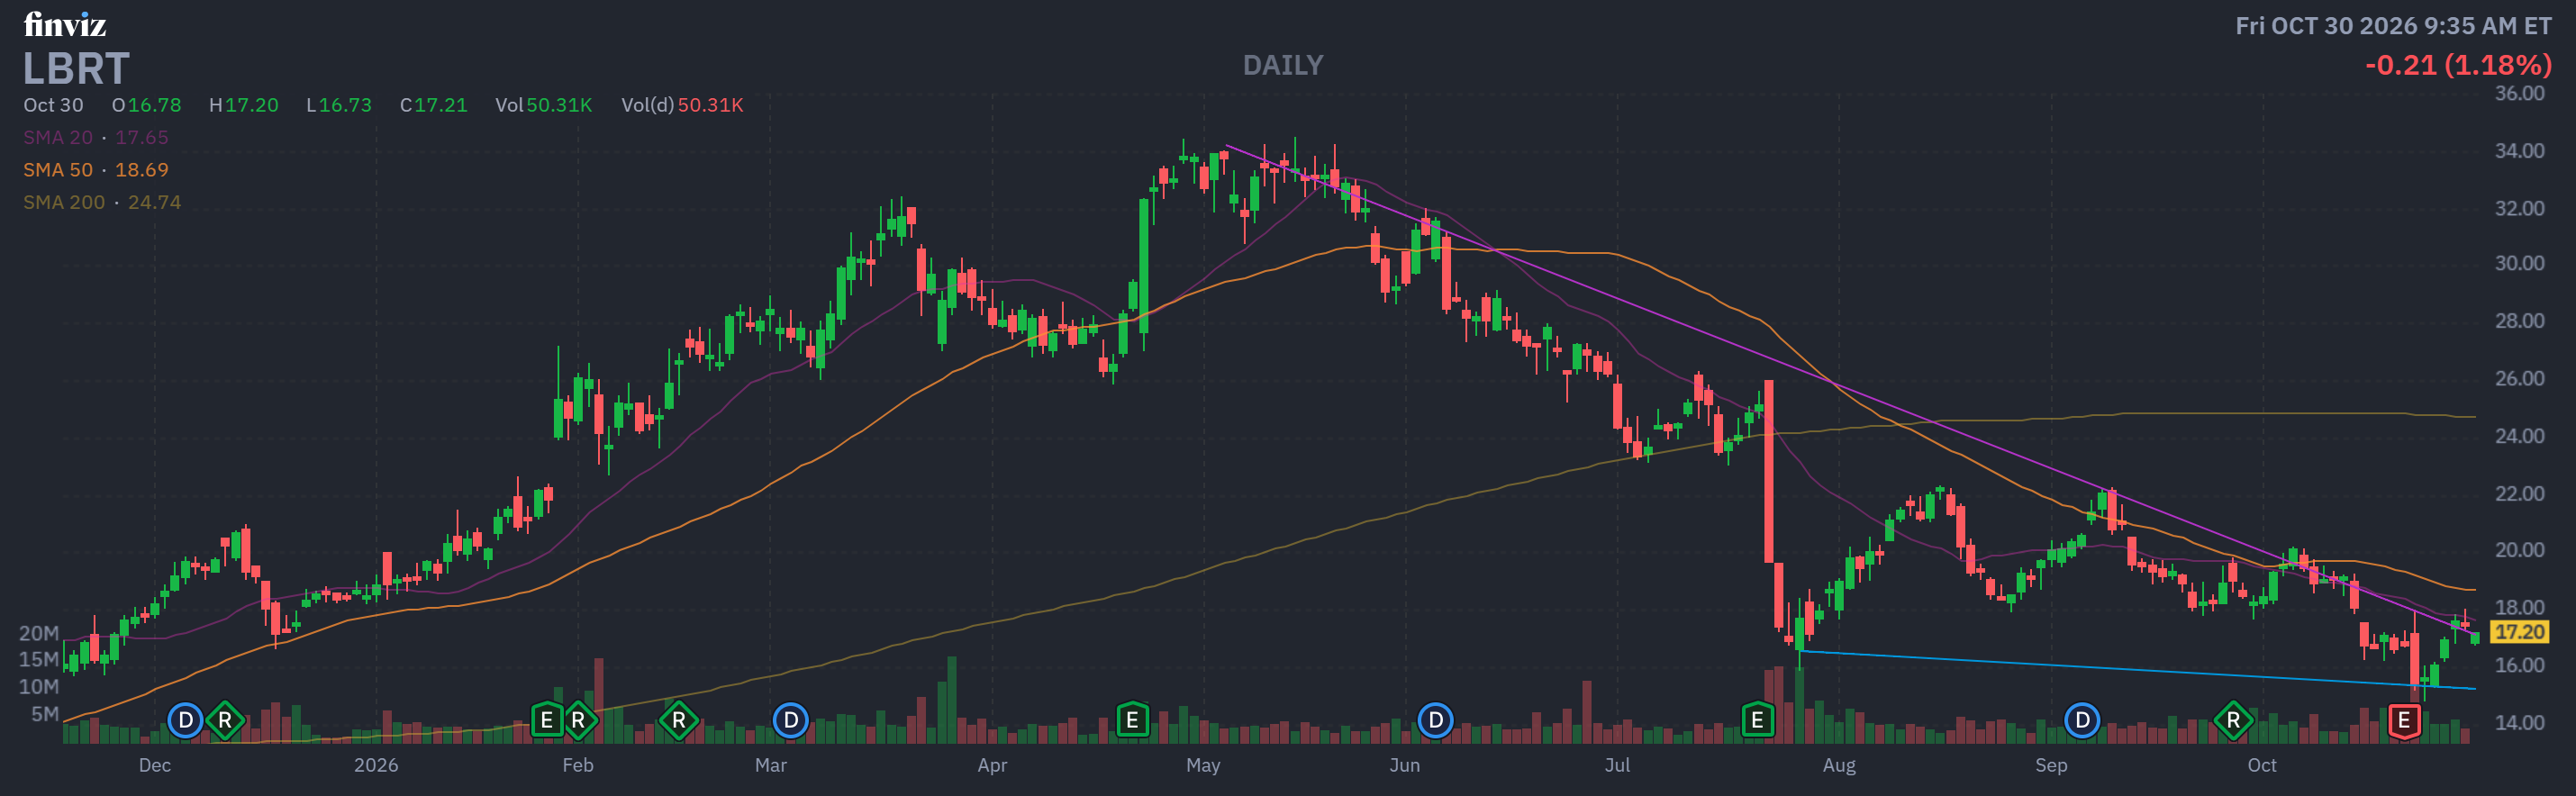
Name: Ken Babcock
Position: Director
Transaction Date: 10-26-2026 Shares Bought: 14,500 shares an average price paid of $15.40 for Cost: $223,300
Company: Liberty Energy Inc. (LBRT)
Liberty Energy Inc., a provider of integrated energy services and technology, offers hydraulic fracturing services and related technologies to North American onshore oil, gas, and enhanced geothermal exploration and production firms. It provides wireline services, proppant delivery solutions, field gas processing and treatment, compressed natural gas distribution, data analytics, and related commodities such as sand mine operations and technology, proppant handling equipment, and logistics software. The company was previously known as Liberty Oilfield Services Inc., but it changed its name to Liberty Energy Inc. in April 2022. Liberty Energy Inc. was founded in 2011 and is based in Denver, Colorado.
Ken Babcock has served as a Director on the Board of Liberty Energy Inc. since 2018. He joined the Board as an independent director, bringing extensive experience in the oilfield services and energy technology industries. Babcock has held several senior leadership positions, including Chief Executive Officer of Abaco Energy Technologies until its acquisition in January 2026, President and CEO of Titan Specialties from 2008 to 2011, and President and CEO of International Logging from 2005 to 2008. Earlier in his career, he held roles at Baker Hughes INTEQ and Noble Technology Services. He holds a Bachelor of Science degree in Geology from Florida State University.
Insomniac Hedge Fund Guy Opinion: Perfect 10 score: +4.5 (constructive, leaning bullish), with bullish reads on analyst sentiment, insider activity, cash flow quality, valuation, sector outlook, and catalysts, offset by a neutral chart and a bearish market-direction read. The core frac business is under real pressure (net loss, shrinking earnings growth), but the stock got hammered on that miss while the far more interesting story, LPI’s gigawatt-scale data center power pivot, keeps gaining traction with a concrete contract timeline. Add a post-selloff insider buy and an 11% dividend hike, and the case leans bullish for investors willing to stomach oilfield-services volatility while the power business matures. This isn’t a stock for someone wanting a smooth ride, it’s a leveraged bet that Liberty successfully becomes an energy-infrastructure company, not just a frac-services one. That decision is yours to make with your advisor.
This blog is solely for educational purposes and the author’s own amusement. IT IS NOT INVESTMENT ADVICE. Think of the blog as part of my personal investment journal that I am willing to share with the DIY investor. We could be long, short, or have no position at all in any of the stocks mentioned and express no written or implied obligation to disclose any of that. Nothing contained here constitutes a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal, and past performance is not indicative of future results.
“The insomniac hedge fund guy” is a moniker Harvey Sax, the portfolio manager for The Insiders Fund” has used from time to time on email, blog ,and social media posts. While Mr. Sax is the portfolio manager of The Insiders Fund, these posts are not communications from, nor endorsed by, Alpha Wealth Funds, LLC or any of its managed funds. References to Alpha Wealth Funds or its affiliates are for identification only and do not imply sponsorship or approval.
All company names, logos, and trademarks belong to their respective owners. The use of company logos is solely for descriptive and illustrative purposes under fair use. Any information provided is based on publicly available data and should not be considered financial, investment, or legal advice. Readers should conduct their own research or consult with a professional before making any investment decisions. Insiders sell the stock for many reasons, but they generally buy for just one – to make money. You’ve always heard the best information is inside information. Everyone with any stock market experience pays close attention to what insiders are doing. After all, who knows a business better than the people running it? Officers, directors, and 10% owners are required to inform the public through a Form 4 Filing of any transaction, buy, sell, exercise, or any other within 48 hours of doing so.
This info is available for free from the SEC’s Web site, Edgar, although we subscribe to SECForm4 as they provide a way to manage and make sense of the vast realms of data. I’ve tried a lot of vendors. SECForm4 is one of the smaller ones, but I like supporting Frank. He is not arrogant. He’s helpful and has great prices. He also trades on his own data, so I like people that eat what they kill. The bar is different from selling because the natural state of management is to be a seller. This is because most companies provide significant amounts of management compensation packages as stock and options. Therefore, we analyze unusual patterns with selling, such as insiders selling 25 percent or more of their holdings or multiple insiders selling near 52-week lows. Another red flag is large planned sale programs that start without warning. Unfortunately, the public information disclosure requirements about these programs, referred to as Rule 10b5-1, are horrendously poor. Also, planned sales that pop up out of nowhere are basically sales and are seeking cover under this corporate welfare loophole.
I also generally ignore 10 percent shareholders as they tend to be OPM (other people’s money) and perhaps not the smart money on which we are trying to read the tea leaves. I say generally because some 10% shareholders are great investor, think Warren Buffett and others. Of course, insiders can also be wrong about their Company’s prospects. Don’t let anyone fool you into believing they never make mistakes. Do your own analysis. They can easily be wrong, and in many cases, maybe most cases, have no more idea what the future may hold than you or me. In short, you can lose money following them. We have, and we curse aloud; what were they thinking!
We like Fly on the Wall for keeping up with what events might be happening, analysts’ comments, and whatever else could be moving the stock. Dow Jones news service is an essential tool, but many services pick up their feed like they do Bloomberg. My assistant probes the 10k for a reasonable description of the business. I’ve found that to be the most accurate and succinct place to find out what a business actually does.
For more, please visit out website at https://insomniachedge.com/