The tech war is on, then it’s off, While semis go cold, then they scoff. The SAS end is near, Or a head fake of fear, As we trapped in psychosis all cough. Data centers will cover the ground, Though the cosmos is where we are bound. By twenty-thirty-six, Cash is out of the mix, And whatever you wish will be found. Money won’t matter in 2036 according to Musk. But it matters today and we are all just a margin call away. Protect your money, look at what insiders are doing with their own.
Name: Michael R. Hayden
Position: Director
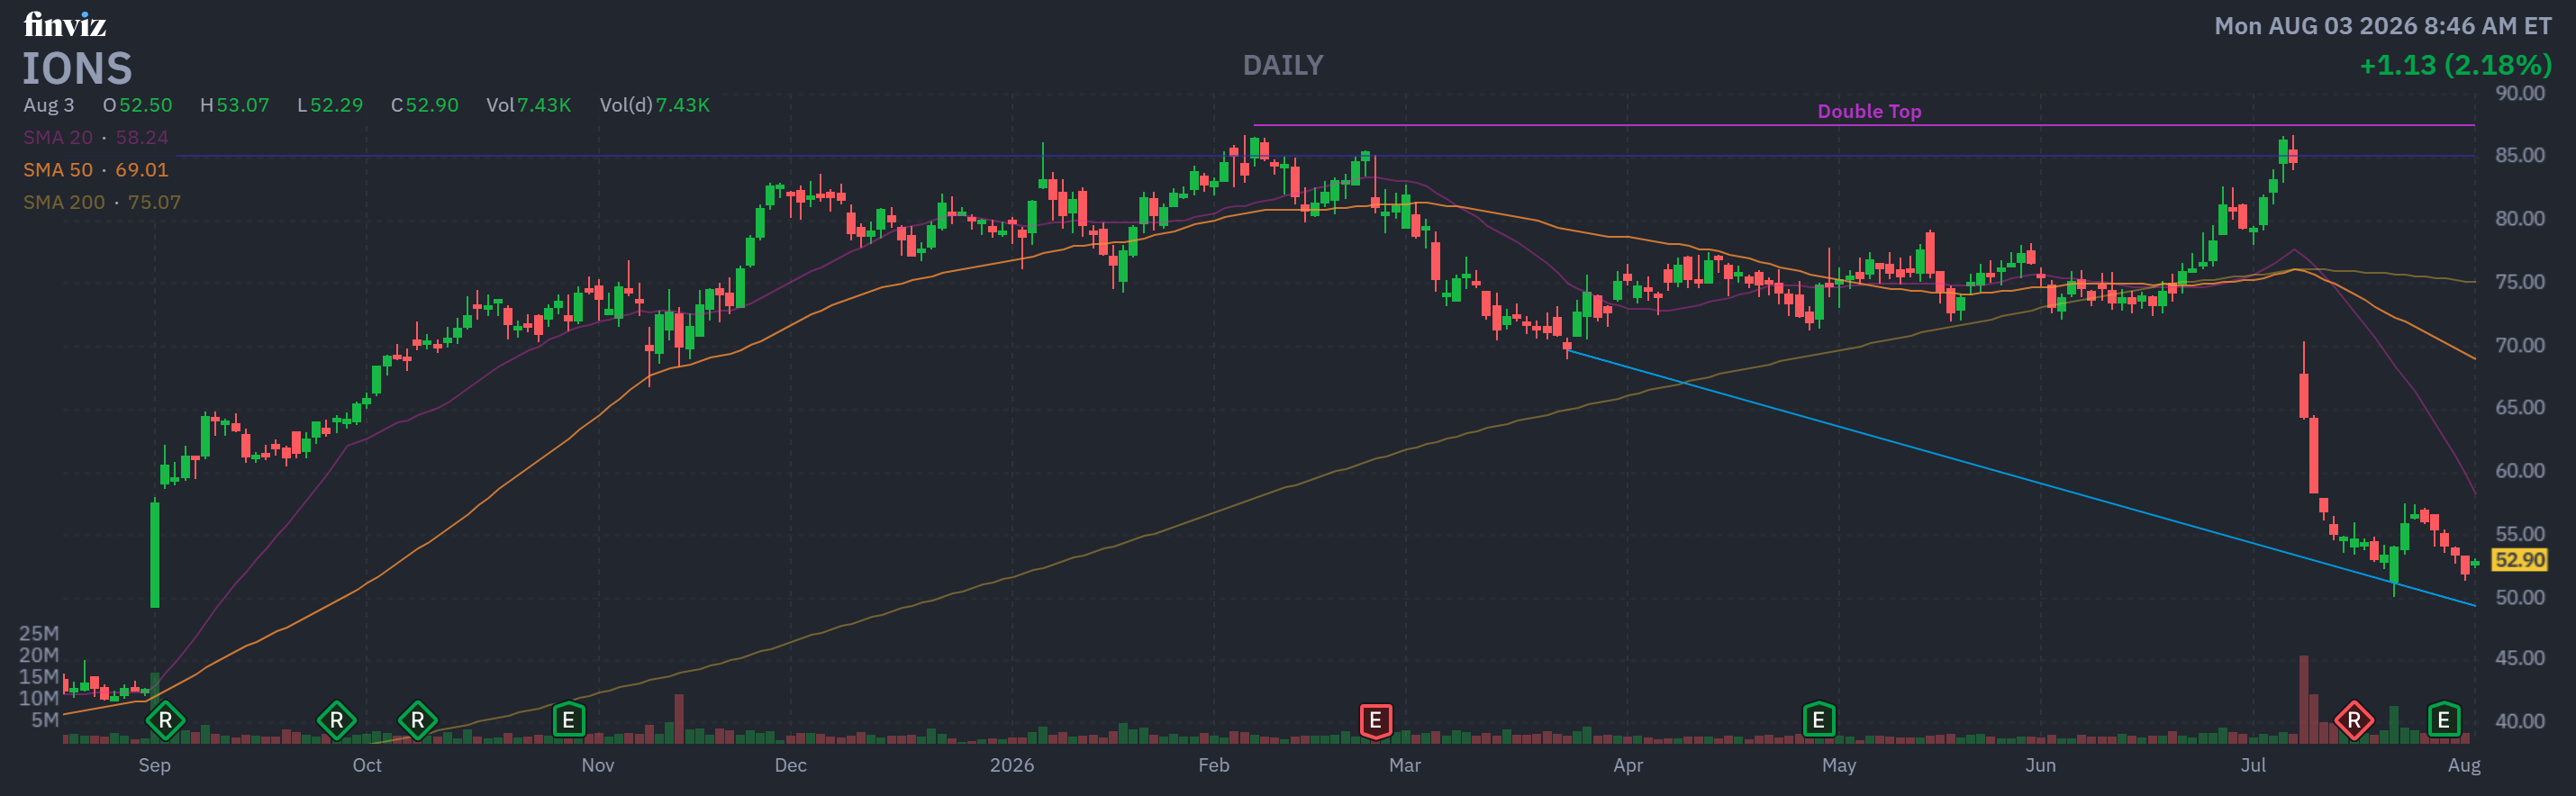
Transaction Date: 07-30-2026 Shares Bought: 20,000 shares an average price paid of $52.94 for Cost: $1,058,700
Company: Ionis Pharmaceuticals Inc. (IONS)
Ionis Pharmaceuticals, Inc. is a commercial-stage biotechnology business that focuses on creating RNA-targeted therapies for critical disorders. Its commercialized products include TRYNGOLZA for familial chylomicronemia syndrome, DAWNZERA for hereditary angioedema, WAINUA and TEGSEDI for hereditary transthyretin amyloidosis, SPINRAZA for spinal muscular atrophy, QALSODY for ALS, and WAYLIVRA for uncommon lipid disorders. The company also has a substantial pipeline, with many Phase 3 and mid-stage products aimed at cardiovascular, neurological, hepatic, and rare genetic illnesses. Strategic agreements with prominent pharmaceutical firms, such as Biogen, GSK, AstraZeneca, Novartis, Roche, and Metagenomi, help Ionis strengthen its innovative capabilities. Ionis Pharmaceuticals, Incorporated. Ionis Pharmaceuticals was founded in 1989 and has its headquarters in Carlsbad, California.
Michael R. Hayden has served as an independent director of Ionis Pharmaceuticals, Inc. since June 2022, when he joined the company’s Board of Directors. He has never served as Chief Executive Officer of Ionis, serving solely as a non-executive director. Hayden is an internationally recognized physician-scientist and biotechnology executive, previously serving as President of Global Research and Development and Chief Scientific Officer at Teva Pharmaceutical Industries Ltd.. He has also held senior leadership roles at the University of British Columbia and has made significant contributions to genetics and precision medicine research. He earned his medical degree from the University of Cape Town and completed postgraduate training in Internal Medicine, Pathology, and Medical Genetics.
Insomniac Hedge Fund Guy Opinion: IONS is a battleground stock right now: a Perfect10 composite of essentially flat at -0.1 (mixed/neutral on a -10 to +10 scale) tells you the market genuinely can’t decide what this company is worth. You’ve got a “Buy”-rated analyst consensus pointing to 72% upside, a director putting over a million dollars of his own money on the table just days ago — and, in the same breath, a PEG ratio north of 27, negative cash flow, and short sellers holding 12% of the float after a real Phase 3 disappointment. This isn’t a stock for anyone who needs a clean story; it’s a binary bet on pelacarsen’s cardiovascular data and zilganersen’s approval landing well in the back half of 2026. I’d call this a speculative hold for existing shareholders and a “wait for the catalyst, not the hype” situation for new money — the pipeline is real, but so is the cash burn, and biotech doesn’t forgive a second trial miss the way it forgave the first.
This analysis is for informational purposes only and isn’t financial advice — do your own due diligence before trading.
Name: Arjun N. Murti
Position: Director
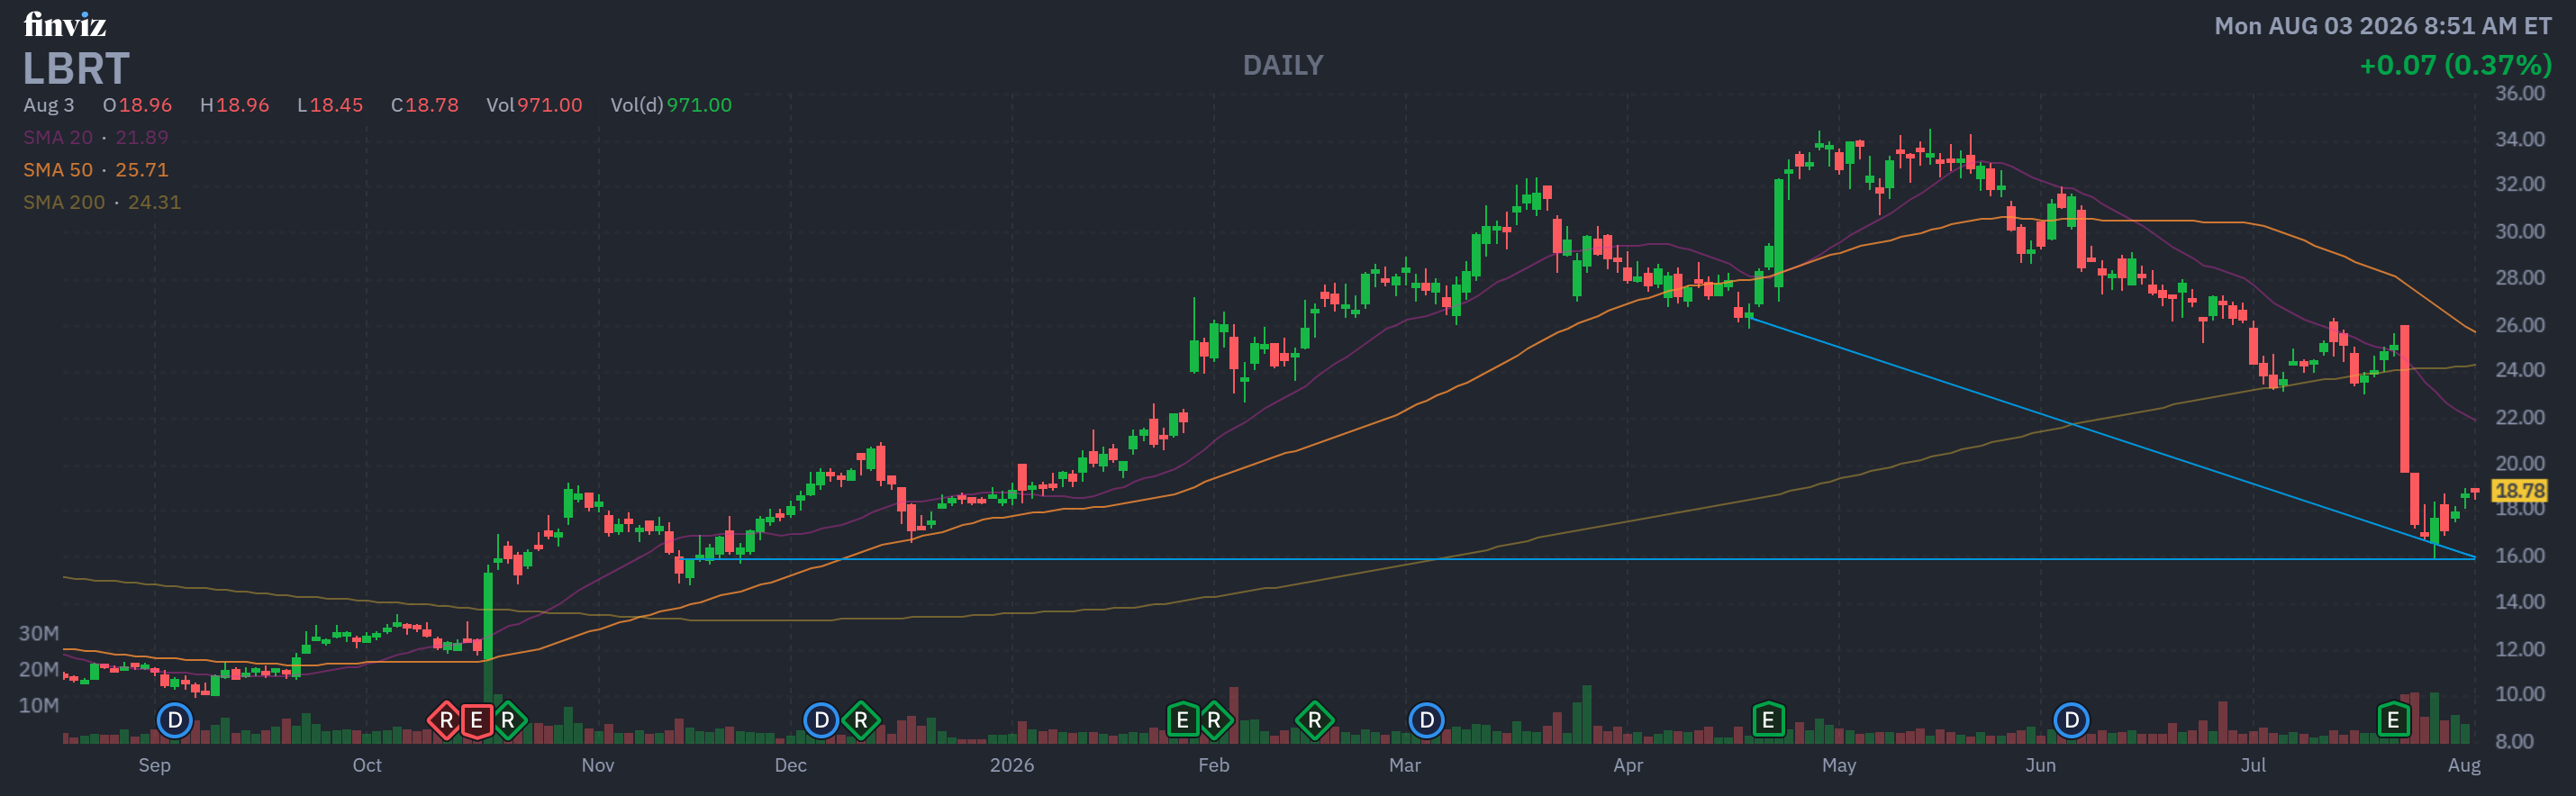
Transaction Date: 07-28-2026 Shares Bought: 14,053 shares an average price paid of $17.79 for Cost: $250,009
Company: Liberty Energy Inc. (LBRT)
Liberty Energy Inc., a provider of integrated energy services and technology, offers hydraulic fracturing services and related technologies to North American onshore oil, gas, and enhanced geothermal exploration and production firms. It provides wireline services, proppant delivery solutions, field gas processing and treatment, compressed natural gas distribution, data analytics, and related commodities such as sand mine operations and technology, proppant handling equipment, and logistics software. The company was previously known as Liberty Oilfield Services Inc., but it changed its name to Liberty Energy Inc. in April 2022. Liberty Energy Inc. was founded in 2011 and is based in Denver, Colorado.
Arjun N. Murti is an energy industry expert who was appointed as Liberty Energy Inc.’s independent Class I director on January 22, 2025, to fill a newly established board seat with an initial term expiring at the company’s 2026 annual meeting of stockholders. Before joining Liberty Energy’s board, he worked as an equities research analyst, counselor, and board member in the global energy industry, including top positions at Veriten LLC and Warburg Pincus, as well as a long stint at Goldman Sachs. Murti’s extensive background in finance and energy strategy complements his governance responsibilities at Liberty. He earned a Bachelor of Science and a Bachelor of Arts in Finance from the University of Denver.
Insomniac Hedge Fund Guy Opinion: LBRT is a value-priced cyclical (7.75x EV/EBITDA) with a legitimate insider buying his own dip and analysts modeling nearly 60% upside — but that upside is doing a lot of work betting the AI power pivot actually materializes before the core frac business finishes its cyclical slide. I’d call this a speculative buy for investors willing to underwrite the power-infrastructure story, not a screaming buy on fundamentals alone: the fracking business is shrinking, margins are under pressure, and customer concentration is a real tail risk. If SLB and PowerBridge deliver anywhere close to the stated capacity targets, today’s price looks cheap in hindsight. If they don’t, you own a discounted oilfield-services company in a fading cycle. This is not financial advice — do your own homework before sizing a position.
Name: Thomas M. Moriarty
Position: EVP, M&A and Corporate Affairs
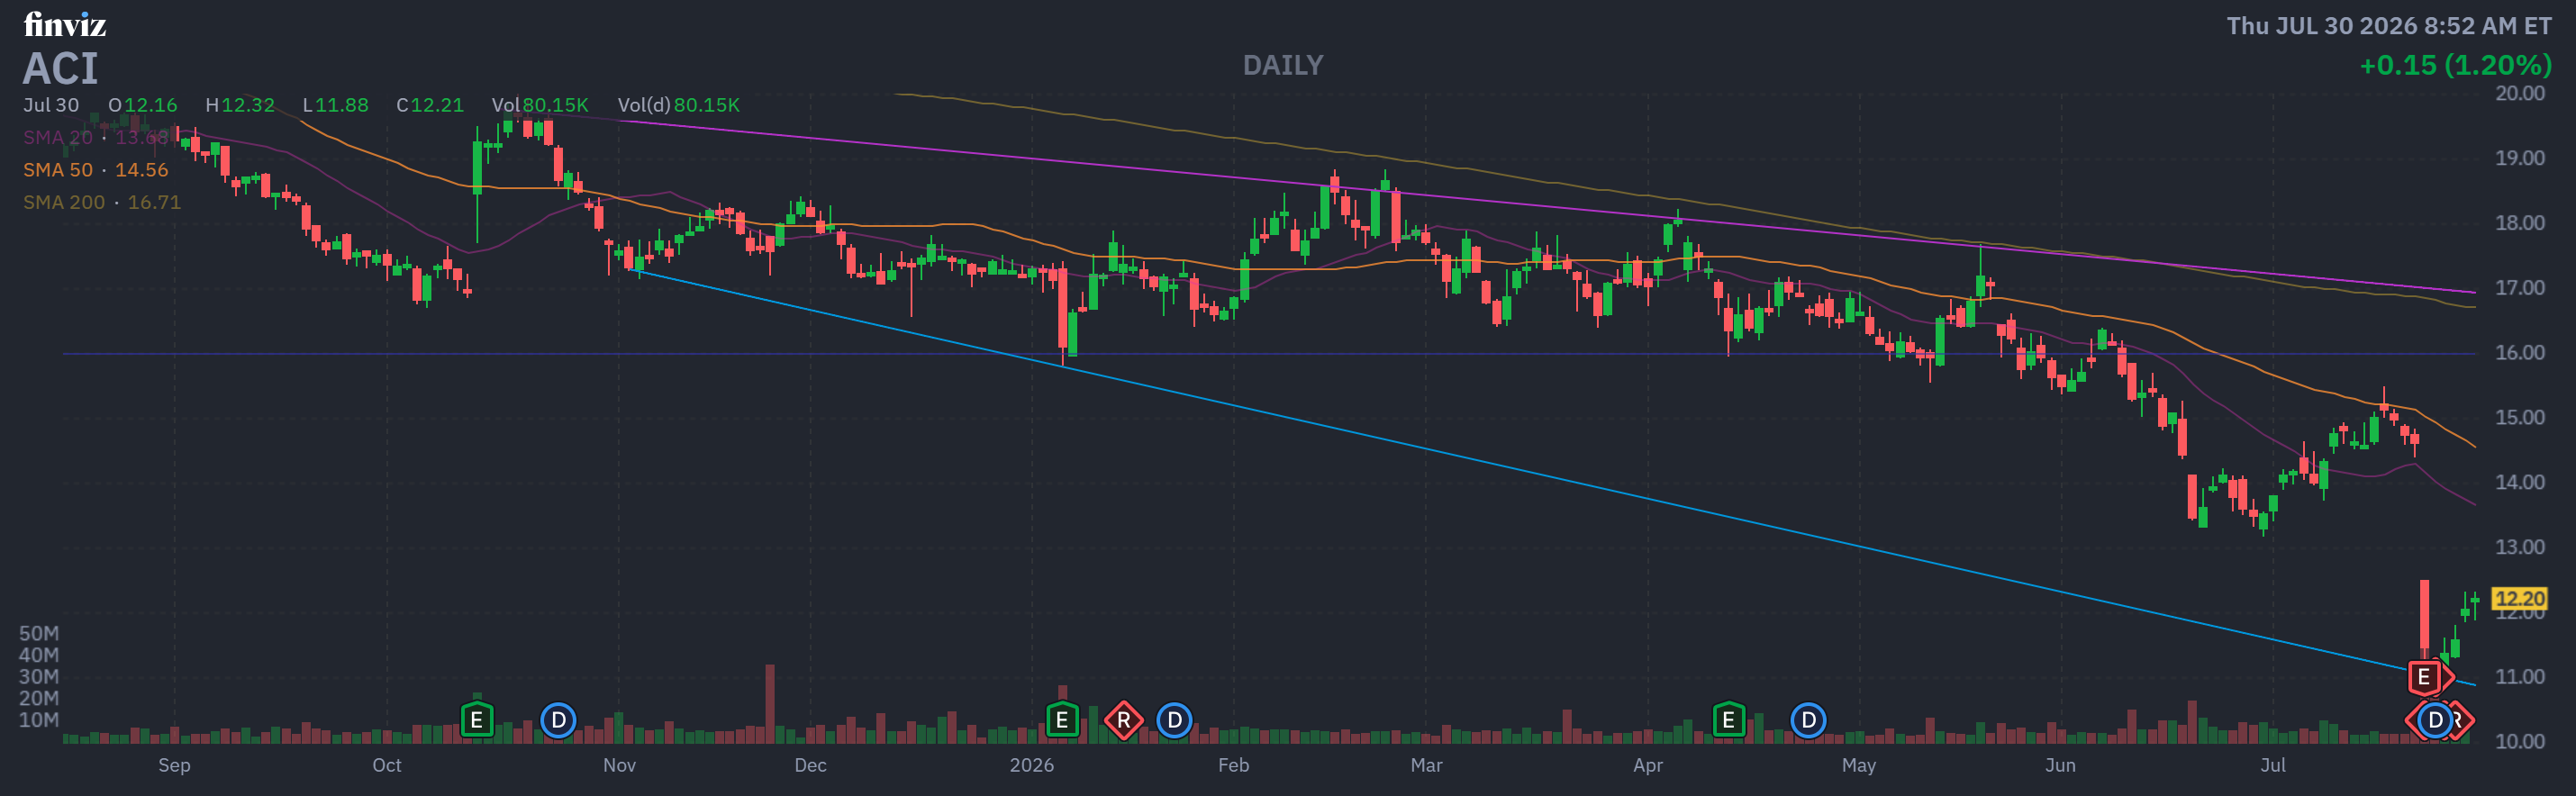
Transaction Date: 07-27-2026 Shares Bought: 170,500 shares an average price paid of $11.51 for Cost: $1,962,285
Company: Albertsons Companies Inc. (ACI)
Albertsons Companies, Inc. and its subsidiaries engage in the food and drug retail market in the United States. The company’s food and drug retail stores sell groceries, general merchandise, health and beauty products, pharmacies, vaccines, petrol, and other goods and services. It also operates stores under a variety of banners, such as Albertsons, Safeway, Vons, Pavilions, Randalls, Tom Thumb, Carrs, Jewel-Osco, ACME, Shaw’s, Star Market, United Supermarkets, Market Street, Haggen, Kings Food Markets, and Balducci’s Food Lovers Market, as well as in-store pharmacies, branded coffee shops, fuel centers, distribution centers, manufacturing facilities, and various digital platforms. Albertsons Companies, Inc. was founded in 1860 and is based in Boise, Idaho.
Since February 2025, Thomas M. Moriarty has been the Executive Vice President of Mergers and Acquisitions and Corporate Affairs at Albertsons Companies, Inc. He joined Albertsons in 2018 as Executive Vice President, General Counsel, and Corporate Secretary, before expanding his responsibilities to include mergers and acquisitions, government relations, and corporate affairs. Moriarty is not a member of the company’s Board of Directors, hence he has not served as a director or CEO. Prior to joining Albertsons, he was Executive Vice President, General Counsel, and Corporate Secretary at CVS Health Corporation. He received a Bachelor of Arts degree from Boston College and a Juris Doctorate from George Washington University Law School.
Insomniac Hedge Fund Guy Opinion: Albertsons just got hit by the ugly stick — guidance cut, earnings miss, CFO heading for the door, and lawyers circling. Short interest is climbing, and the sector itself is out of favor. That’s a legitimate list of red flags, and I won’t pretend otherwise.
But here’s what keeps this from being a straight “avoid”: insiders just put $2.4 million of their own money into this stock during the wreckage, the valuation (6x EV/EBITDA, well below the historical range) already prices in a lot of the bad news, and the dividend keeps growing even as guidance shrinks. That’s not the behavior of a company circling the drain — it’s a company mid-stumble, not mid-collapse.
My read: this is a speculative “show-me” story, not a screaming buy or a hard pass. If “ACI Edge” delivers real efficiency and the Kroger break-fee lawsuit goes Albertsons’ way in October, there’s real upside from a beaten-down price. If execution falters again, the shorts piling in right now get paid. I’d rather watch the October earnings report and lawsuit outcome from the sidelines than catch this falling grocery cart today.
This is market commentary and educational analysis, not personalized investment advice — do your own research before trading.
This blog is solely for educational purposes and the author’s own amusement. IT IS NOT INVESTMENT ADVICE. Think of the blog as part of my personal investment journal that I am willing to share with the DIY investor. We could be long, short, or have no position at all in any of the stocks mentioned and express no written or implied obligation to disclose any of that. Nothing contained here constitutes a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal, and past performance is not indicative of future results.
“The insomniac hedge fund guy” is a moniker Harvey Sax, the portfolio manager for The Insiders Fund” has used from time to time on email, blog ,and social media posts. While Mr. Sax is the portfolio manager of The Insiders Fund, these posts are not communications from, nor endorsed by, Alpha Wealth Funds, LLC or any of its managed funds. References to Alpha Wealth Funds or its affiliates are for identification only and do not imply sponsorship or approval.
All company names, logos, and trademarks belong to their respective owners. The use of company logos is solely for descriptive and illustrative purposes under fair use. Any information provided is based on publicly available data and should not be considered financial, investment, or legal advice. Readers should conduct their own research or consult with a professional before making any investment decisions. Insiders sell the stock for many reasons, but they generally buy for just one – to make money. You’ve always heard the best information is inside information. Everyone with any stock market experience pays close attention to what insiders are doing. After all, who knows a business better than the people running it? Officers, directors, and 10% owners are required to inform the public through a Form 4 Filing of any transaction, buy, sell, exercise, or any other within 48 hours of doing so.
This info is available for free from the SEC’s Web site, Edgar, although we subscribe to SECForm4 as they provide a way to manage and make sense of the vast realms of data. I’ve tried a lot of vendors. SECForm4 is one of the smaller ones, but I like supporting Frank. He is not arrogant. He’s helpful and has great prices. He also trades on his own data, so I like people that eat what they kill. The bar is different from selling because the natural state of management is to be a seller. This is because most companies provide significant amounts of management compensation packages as stock and options. Therefore, we analyze unusual patterns with selling, such as insiders selling 25 percent or more of their holdings or multiple insiders selling near 52-week lows. Another red flag is large planned sale programs that start without warning. Unfortunately, the public information disclosure requirements about these programs, referred to as Rule 10b5-1, are horrendously poor. Also, planned sales that pop up out of nowhere are basically sales and are seeking cover under this corporate welfare loophole.
I also generally ignore 10 percent shareholders as they tend to be OPM (other people’s money) and perhaps not the smart money on which we are trying to read the tea leaves. I say generally because some 10% shareholders are great investor, think Warren Buffett and others. Of course, insiders can also be wrong about their Company’s prospects. Don’t let anyone fool you into believing they never make mistakes. Do your own analysis. They can easily be wrong, and in many cases, maybe most cases, have no more idea what the future may hold than you or me. In short, you can lose money following them. We have, and we curse aloud; what were they thinking!
We like Fly on the Wall for keeping up with what events might be happening, analysts’ comments, and whatever else could be moving the stock. Dow Jones news service is an essential tool, but many services pick up their feed like they do Bloomberg. My assistant probes the 10k for a reasonable description of the business. I’ve found that to be the most accurate and succinct place to find out what a business actually does.