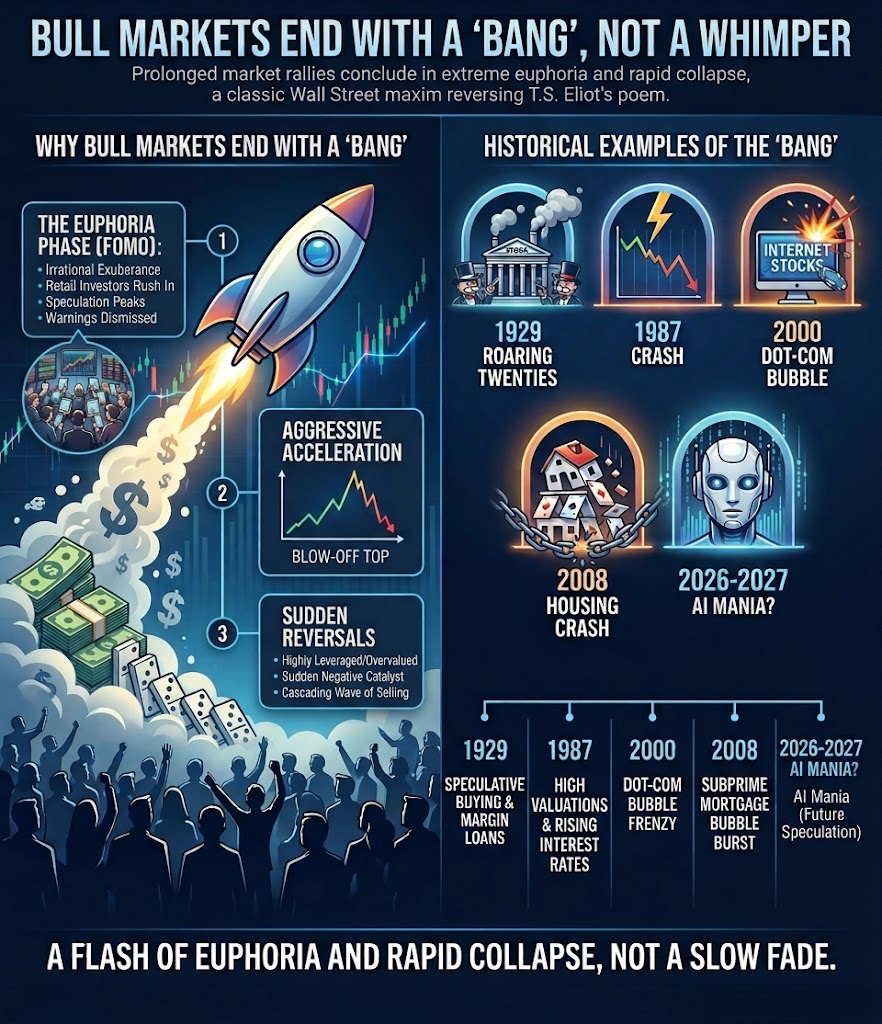
- The Euphoria Phase: At the very peak, investor optimism turns into irrational exuberance. Retail investors rush in due to FOMO (fear of missing out), speculation peaks, and warnings are dismissed.
- Aggressive Acceleration: Prices often rise at their steepest, most vertical angle right before the crash, creating a blow-off top.
- Sudden Reversals: Because the market becomes highly leveraged and overvalued, a sudden negative catalyst (like a spike in interest rates or a liquidity shortage) triggers a cascading wave of selling.
- 1929 Roaring Twenties: Years of speculative buying funded by margin loans ended abruptly with Black Thursday and Black Tuesday, shattering the economy.
- Crash of 1987:
- High valuations: Stock prices had surged dramatically for years. Many experts agree the market was overvalued and overdue for a major correction.
- Rising interest rates and inflation: Inflation began to tick up in early 1987, leading to higher interest rates that made bonds more attractive than stocks. [
- Trade deficits and currency shifts: Tensions regarding the U.S. trade deficit and a falling U.S. dollar—compounded by international policy disagreements like the Louvre and Plaza Accords—spooked global investors
- 2000 Dot-Com Bubble: Extreme valuations in internet stocks peaked in a massive frenzy before crashing rapidly as companies burned through cash.
- 2008 Housing Crash: A boom in subprime mortgage lending built a massive bubble that burst violently, freezing global credit markets almost overnight.
- 2026-2027 AI Mania of course this hasn’t happened yet but we all know history rhymes rather than repeats and this sounds just about like iambic pentameter to me.
Name: David Blair Kirk
Position: Director
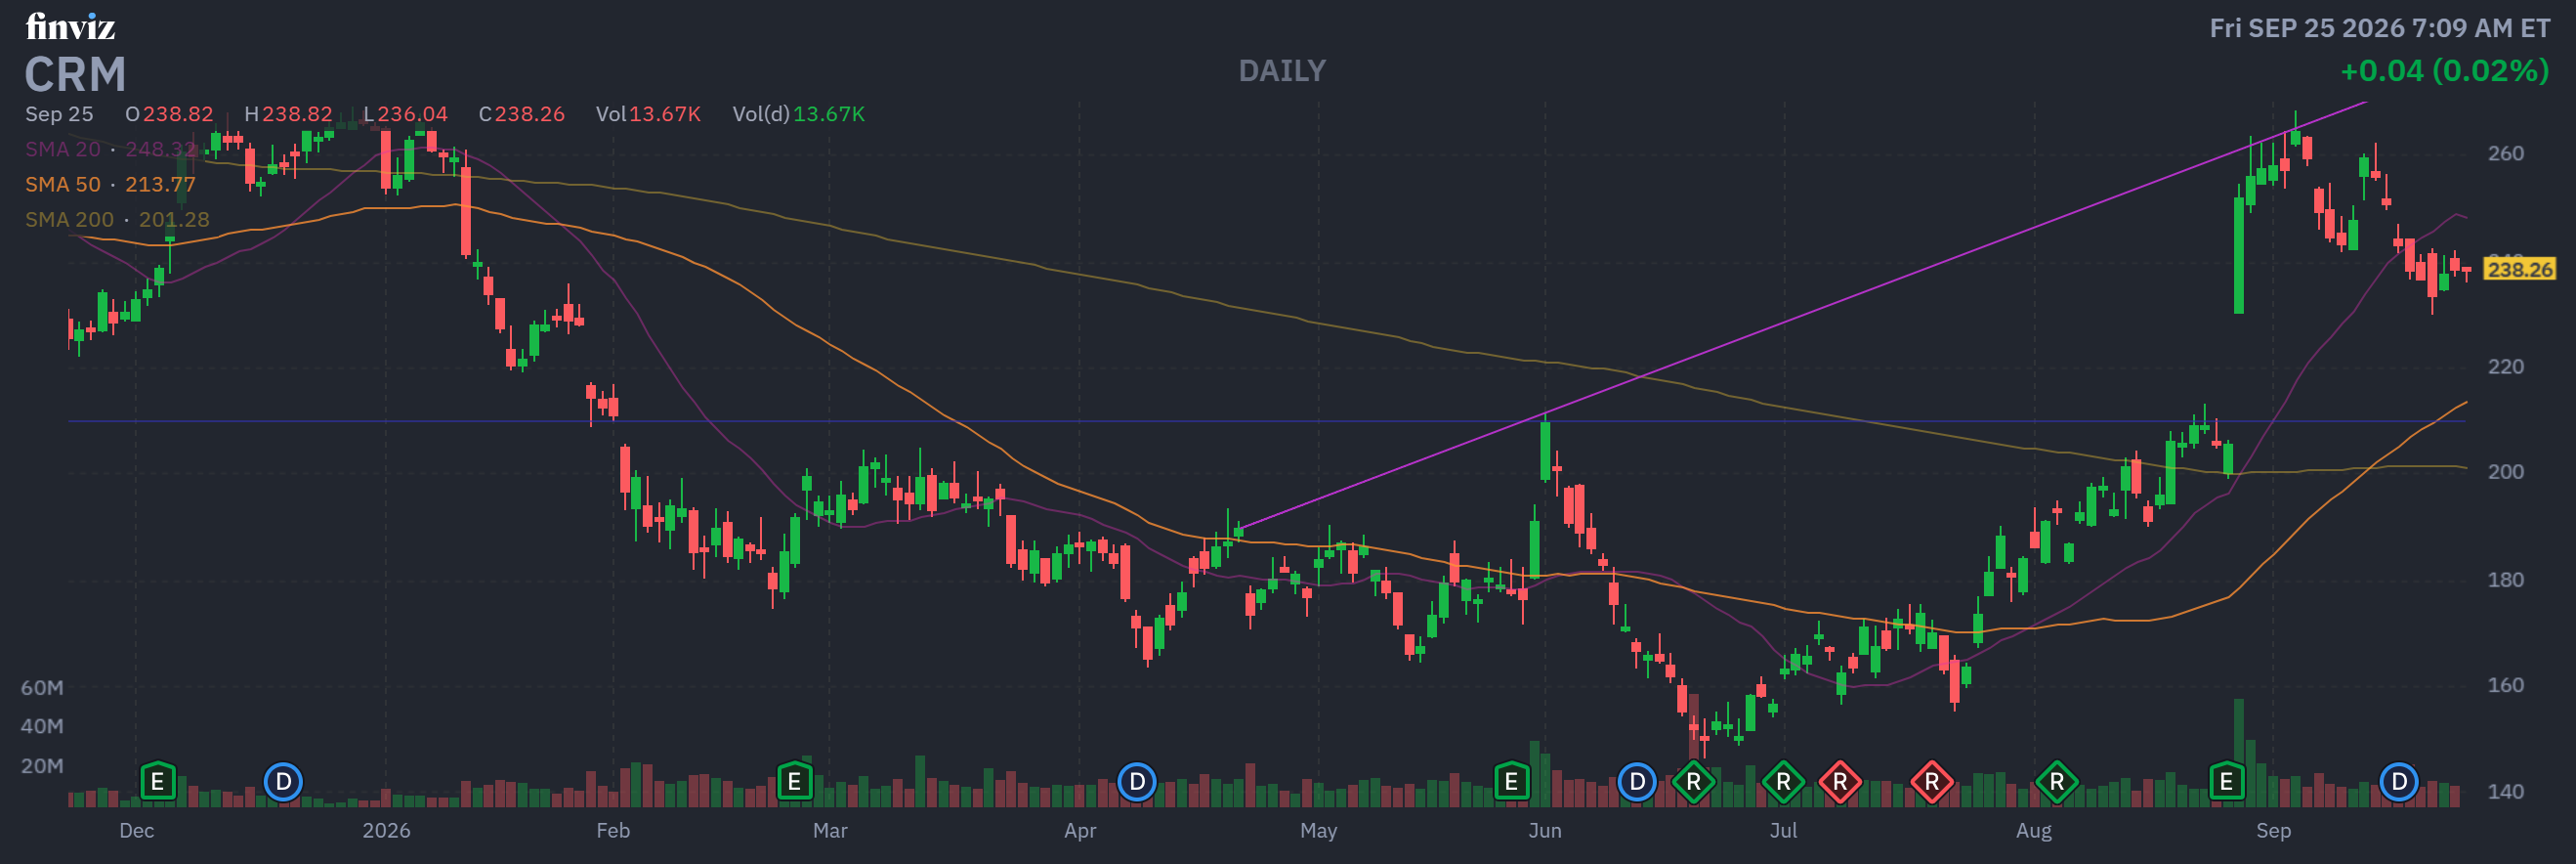
Transaction Date: 09-18-2026 Shares Bought: 4,176 shares an average price paid of $239.33 for Cost: $999,451
Company: Salesforce Inc. (CRM)
Salesforce, Inc. offers customer relationship management technology services that connect businesses and customers across the United States, Europe, and Asia Pacific. The company provides Agentforce, which enables customers to build, deploy, and manage enterprise-grade, autonomous AI agents at scale, allowing humans and agents to collaborate; Agentforce Sales, an integrated platform that combines the power of humans with AI agents to assist sales teams in selling, managing, and automating entire sales processes; and Agentforce Service, which enables companies in every industry to bring all of their customer, employee.It supports the financial services, healthcare and life sciences, manufacturing, automotive, and government industries. Salesforce, Inc. was established in 1999 and is based in San Francisco, California.
David Blair Kirk has served as a Director of Salesforce Inc. since November 2018, when he was appointed to the company’s Board of Directors to provide strategic guidance on technology, operations, and corporate governance. He brings extensive executive experience from his leadership roles in the technology and software industries, including his tenure as Chief Executive Officer and Director of NeXT Computer and as a senior executive at Apple, where he contributed to software development and enterprise technology strategy. Kirk has also served on the boards of several technology and financial services companies, offering expertise in corporate management, innovation, and growth strategy. He holds a Bachelor of Science degree in Electrical Engineering from Stanford University.
Insomniac Hedge Fund Guy Opinion: Salesforce just proved the “AI kills SaaS” thesis wrong, at least for now, ripping 23% in a day and following it with raised long-term guidance. Growth has slowed to a mature company’s pace, margins are solid but not best-in-class, and the valuation at 17.5x EBITDA isn’t a gift. But a 0.79 PEG ratio, a $72 billion contracted revenue backlog, a director buying shares with his own money, and short sellers already covered and out the door add up to a name with more room to climb than to fall. This is a buy on the dip that already happened, not the top: I’d rather own the moat with the AI optionality than bet against it.
Name: Larry Jr. Fitzgerald
Position: Director
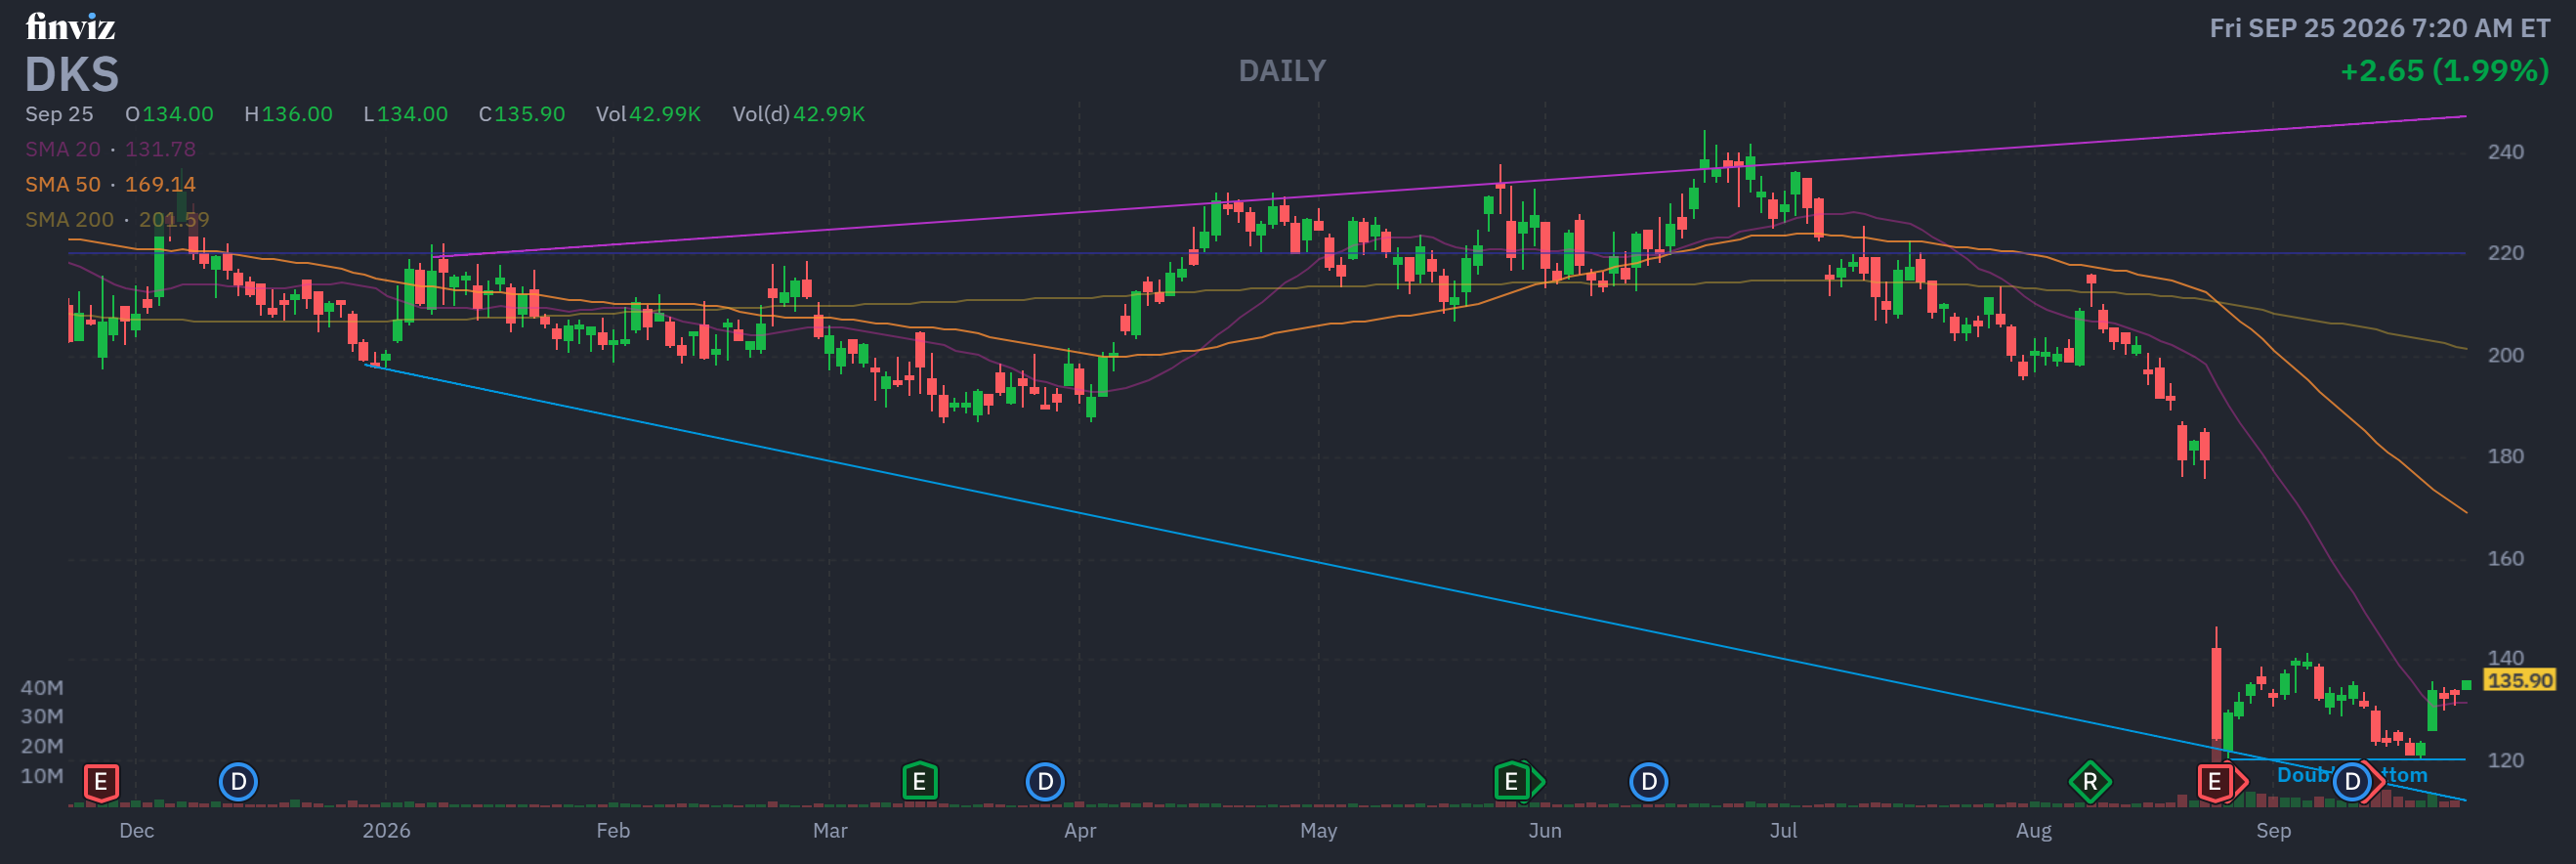
Transaction Date: 09-23-2026 Shares Bought: 1,860 shares an average price paid of $131.67 for Cost: $244,906
Name: Navdeep Gupta
Position: EVP, Chief Financial Officer
Transaction Date: 09-22-2026 Shares Bought: 7,707 shares an average price paid of $129.75 for Cost: $999,983
Company: Dick’s Sporting Goods Inc. (DKS)
DICK’S Sporting Goods, Inc. is a multichannel sporting goods retailer based mostly in the United States. The company sells sporting products, exercise equipment, golf equipment, fishing gear, clothing, footwear, and accessories for a variety of sports and outdoor activities. It owns and operates specialist concept stores such as Sporting Goods, Golf Galaxy, Public Lands, Moosejaw, and Going Going Gone!, as well as DICK’S House of Sport and Golf Galaxy Performance Center. The firm was previously known as Dick’s Clothing and Sporting Goods, Inc. before changing its name to DICK’S Sporting Goods, Inc. in April 1999. DICK’S Sporting Goods, Inc. was established in 1948 and is based in Coraopolis, Pennsylvania.
Larry Fitzgerald, Jr. has been a Director at DICK’S Sporting Goods, Inc. since July 2020, when he joined the company’s Board of Directors. Prior to joining the Board, he worked for DICK’S Sporting Goods for than a decade and was a member of the DICK’S Sporting Goods Foundation Sports Matter Advisory Board. He is a former NFL player who played for the Arizona Cardinals. He is now involved in business and humanitarian projects through Larry Fitzgerald Enterprises and the Larry Fitzgerald Foundation. He attended the University of Pittsburgh and received a B.A. in Communications from the University of Phoenix.
Navdeep Gupta joined DICK’S Sporting Goods, Inc. in November 2017 as Senior Vise President, Finance, and Chief Accounting Officer, and will become Executive Vise President and Chief Financial Officer in October 2021. He oversees the company’s finance, investor relations, accounting, procurement, construction, planning, allocation and replenishment, and pricing responsibilities. Gupta is not a member of the DICK’S Sporting Goods Board of Directors; instead, he joined the Lowe’s Companies Board in May 2024. Prior to joining DICK’S, he held top finance positions at Advance Auto Parts and Sprint Nextel, as well as a lieutenant in the Indian Navy. He has an undergraduate degree in Physics from the University of Madras and an MBA from William and Mary.
Insomniac Hedge Fund Guy Opinion: DKS is a buy for patient investors, not a trade for the faint of heart. The core DICK’S business is still one of the best-run retailers in America, throwing off strong cash flow even while absorbing a genuinely messy Foot Locker integration. The stock has been beaten down 30% on a guidance cut that’s real but likely temporary, and the valuation (9x EBITDA, DCF fair value north of $145) plus insider buying and Perfect 10 composite score of +1.7 (mixed to modestly bullish) suggest the market has priced in the worst of the Foot Locker drag without giving enough credit for the turnaround optionality. The risk is real: if Fast Break doesn’t scale and Foot Locker keeps bleeding, this becomes a value trap. But at these levels, the reward skews in the buyer’s favor.
Name: Jon Faiz Kayyem
Position: Director
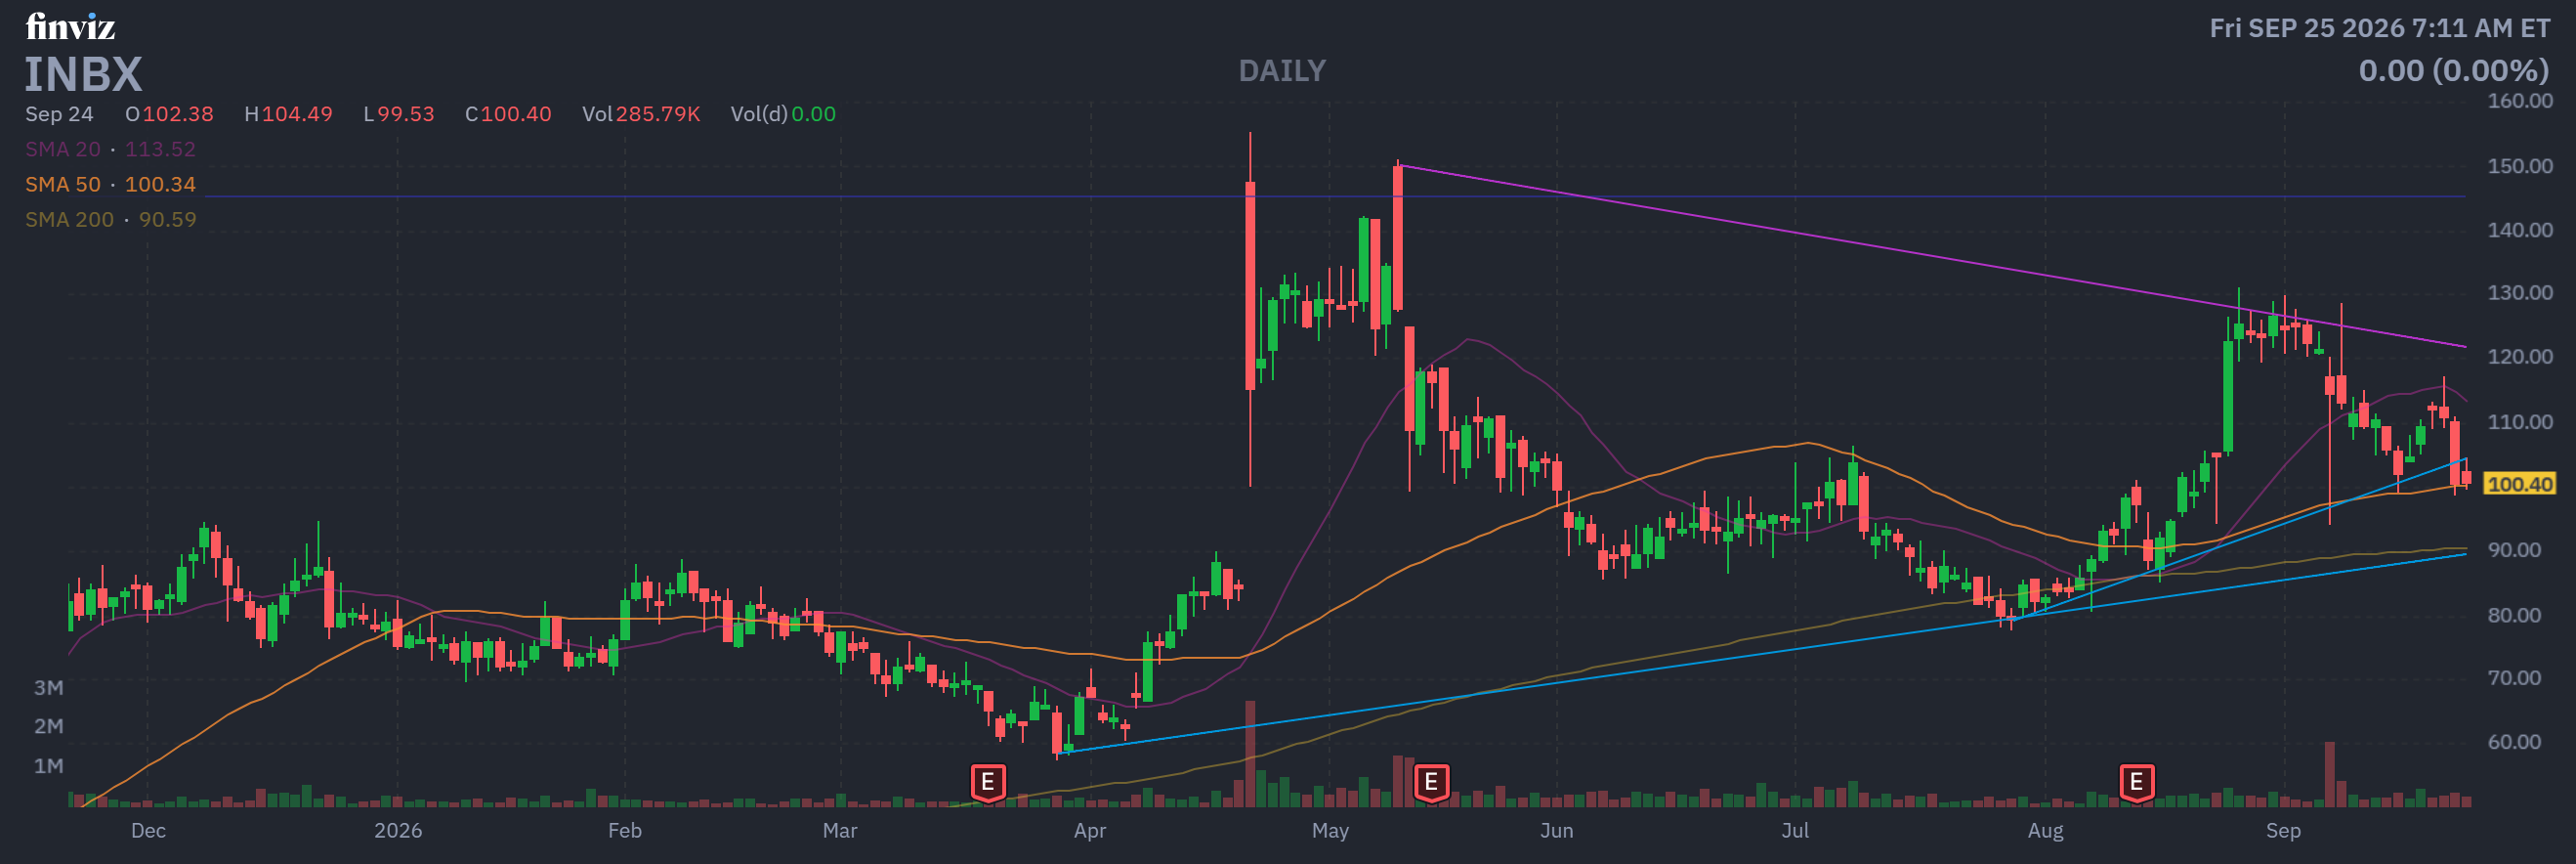
Transaction Date: 09-23-2026 Shares Bought: 5,000 shares an average price paid of $100.00 for Cost: $500,000
Company: Inhibrx Biosciences Inc. (INBX)
Inhibrx Biosciences, Inc. is a clinical-stage biopharmaceutical firm that develops biologic therapies for patients with life-threatening illnesses. INBRX-109, a tetravalent therapeutic candidate targeting death-receptor 5 to treat unresectable or metastatic conventional chondrosarcoma, and INBRX-106, a hexavalent sdAb-based therapeutic candidate targeting OX4 for the treatment of metastatic solid tumor, non-small cell lung cancer, melanoma, head non-small cell lung cancer cell carcinoma, gastric or gastroesophageal junction adenocarcinoma, renal cell carcinoma, Inhibrx Biosciences, Inc. was established in 2024 and is headquartered in La Jolla, California.
Jon Faiz Kayyem, has been a Director of Inhibrx Biosciences Inc. since May 2024, when he joined the board following the company’s split from its former parent. He formerly served on the former parent’s board from April 2018 until May 2024. Kayyem founded GenMark Diagnostics and has held various leadership positions, including President and Chief Executive Officer. He has vast knowledge with biotechnology, diagnostics, and biotherapeutics. He earned a B.S. and M.S. in Molecular Biophysics and Biochemistry from Yale University and a Ph.D. in Molecular Biology from Caltech.
Insomniac Hedge Fund Guy Opinion: INBX is a high-conviction, high-risk binary bet dressed up as a $100 stock. The Perfect10 composite comes in at +3 out of a possible +10 (Constructive), driven by strong analyst sentiment (Strong Buy consensus, average target $266.67), bullish insider buying, and positive catalyst flow, offset by genuinely bearish cash flow. The clinical data is real, the insider buying is loud and recent, and the M&A chatter isn’t nothing when names like Merck and Ono are reportedly involved. But this stock has already run 300%+ off its lows, short interest above 20% of float says plenty of sharp money doesn’t buy the story at these levels, and there’s zero revenue cushion if a trial disappoints. I’d call this a speculative buy for risk-tolerant investors who can stomach a stock that could double or get cut in half on a single FDA letter, not a core holding for anyone who needs to sleep at night. Do your own diligence here; this is analysis, not a recommendation.
Name: Warren E. Buffett
Position: 10% Owner
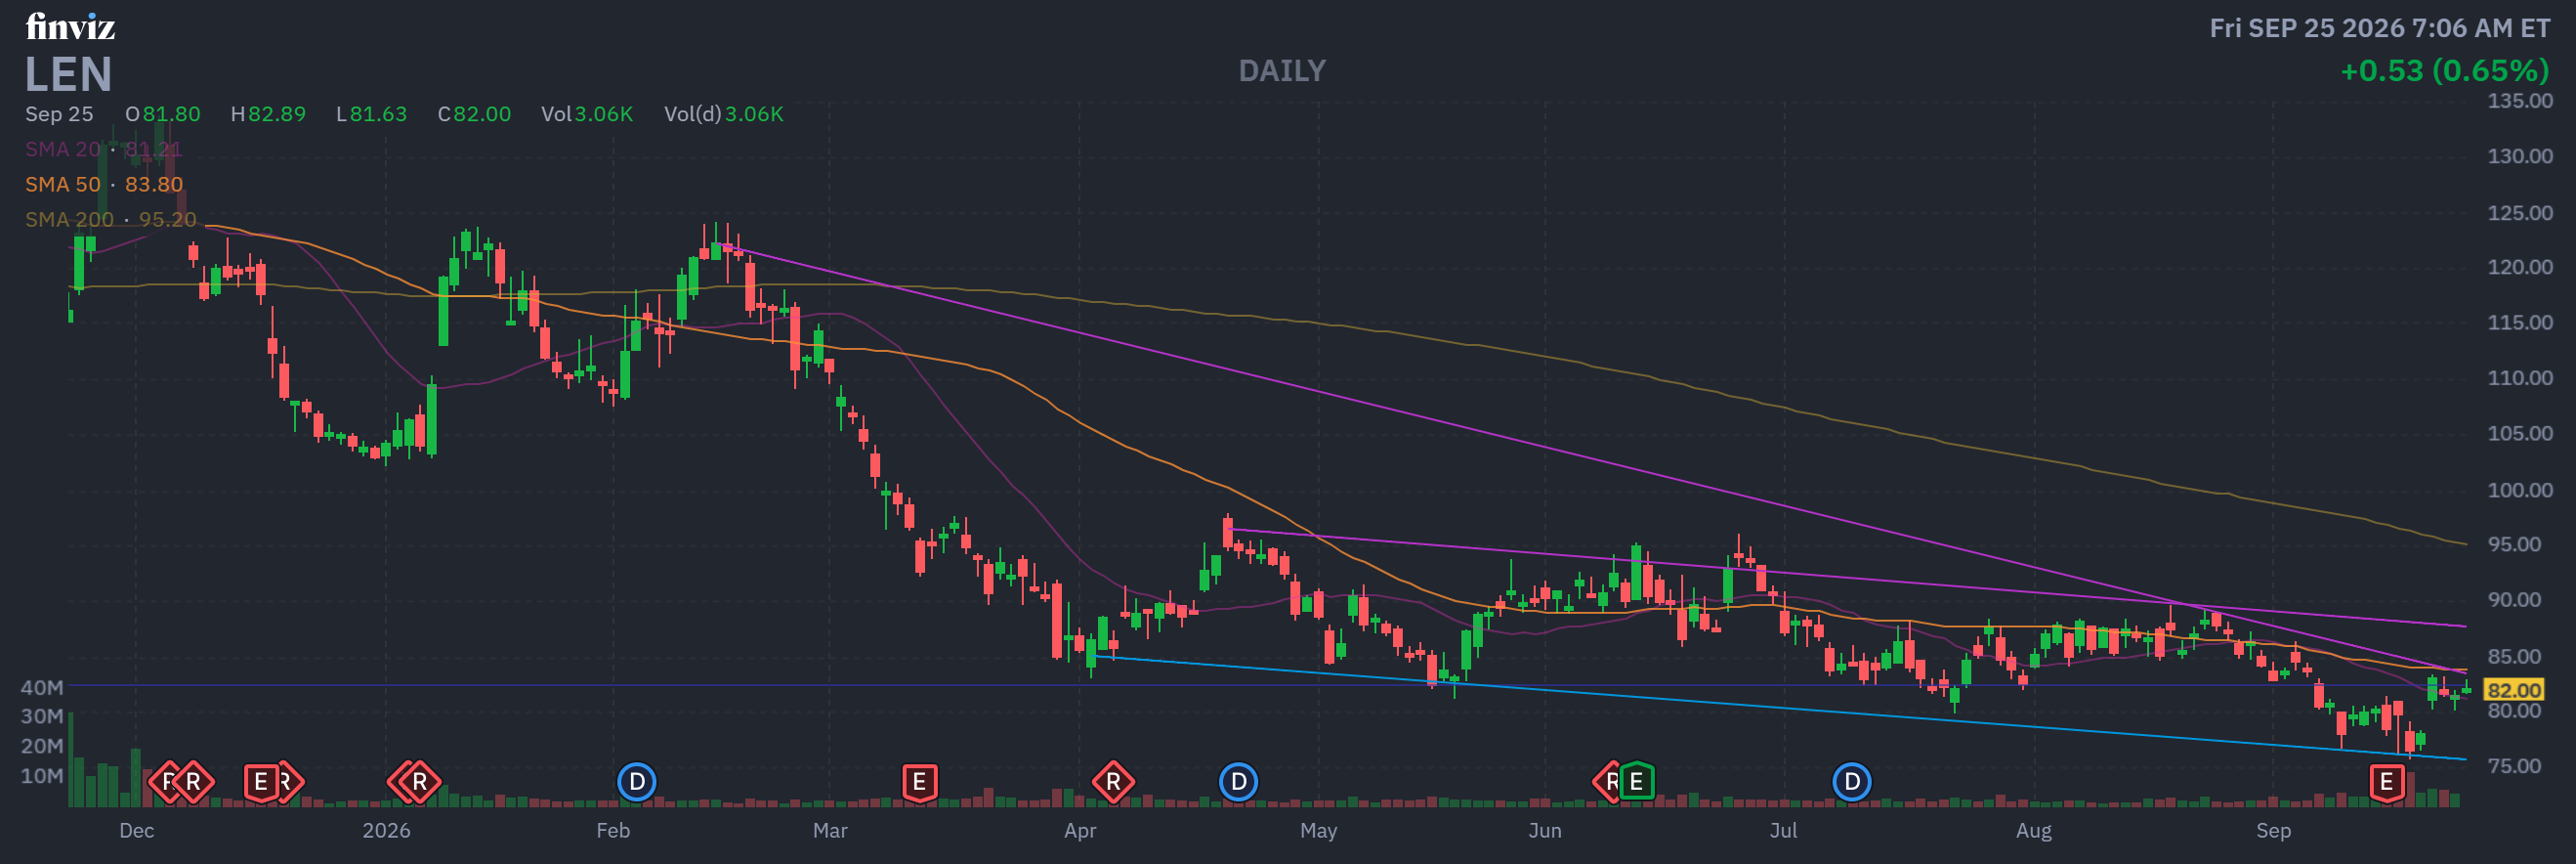
Transaction Date: 09-17-2026 Shares Bought: 2,743,529 shares an average price paid of $77.42 for Cost: $212,395,151
Company: Lennar Corp. (LEN)
Lennar Corporation and its subsidiaries are primarily a homebuilder in the United States, operating under the Lennar brand. It works through the following segments: Homebuilding East, Homebuilding Central, Homebuilding South Central, Homebuilding West, Financial Services, Multifamily, and Lennar Other. The company’s homebuilding operations include the construction and sale of single-family attached and detached homes, as well as the purchase, development, and sale of residential land. It also develops, builds, and manages multifamily rental properties. It also provides residential mortgage finance, title insurance, and closing services to homebuyers and others, as well as the origination and sale of securitized commercial mortgage loans. The company was created in 1954 and is headquartered in Miami, Florida.
Warren E. Buffett is a 10% Owner of Lennar Corp. through Berkshire Hathaway Inc. and its insurance subsidiaries, which hold the reported Lennar shares. His association with Lennar began in 2026 through Berkshire Hathaway’s investment, and he is not a CEO or member of Lennar’s Board of Directors. Buffett is best known as the longtime leader of Berkshire Hathaway, having served as its Chairman and CEO before Gregory Abel became CEO. He studied at the University of Nebraska and earned a Master of Science in Economics from Columbia Business School.
Insomniac Hedge Fund Guy Opinion: Lennar is cheap on paper (0.87x book, a DCF ceiling well above the current price) but that operating cash flow collapse is the number that keeps me from calling this an easy buy. Margins are compressing, orders are falling, and management is explicitly sacrificing profitability to keep the assembly line moving. The Berkshire stake and the beaten-down valuation make this a legitimate value-watch name for patient investors betting on a rate-driven housing recovery, but I wouldn’t call it a buy here, I’d call it a hold for existing owners and a “wait for the cash flow story to clear up” for new money. This is a rate-cut bet dressed up as a stock pick, and until mortgage rates actually move, the fundamentals don’t give you much cover.
Name: Patrick E. Allen
Position: Director
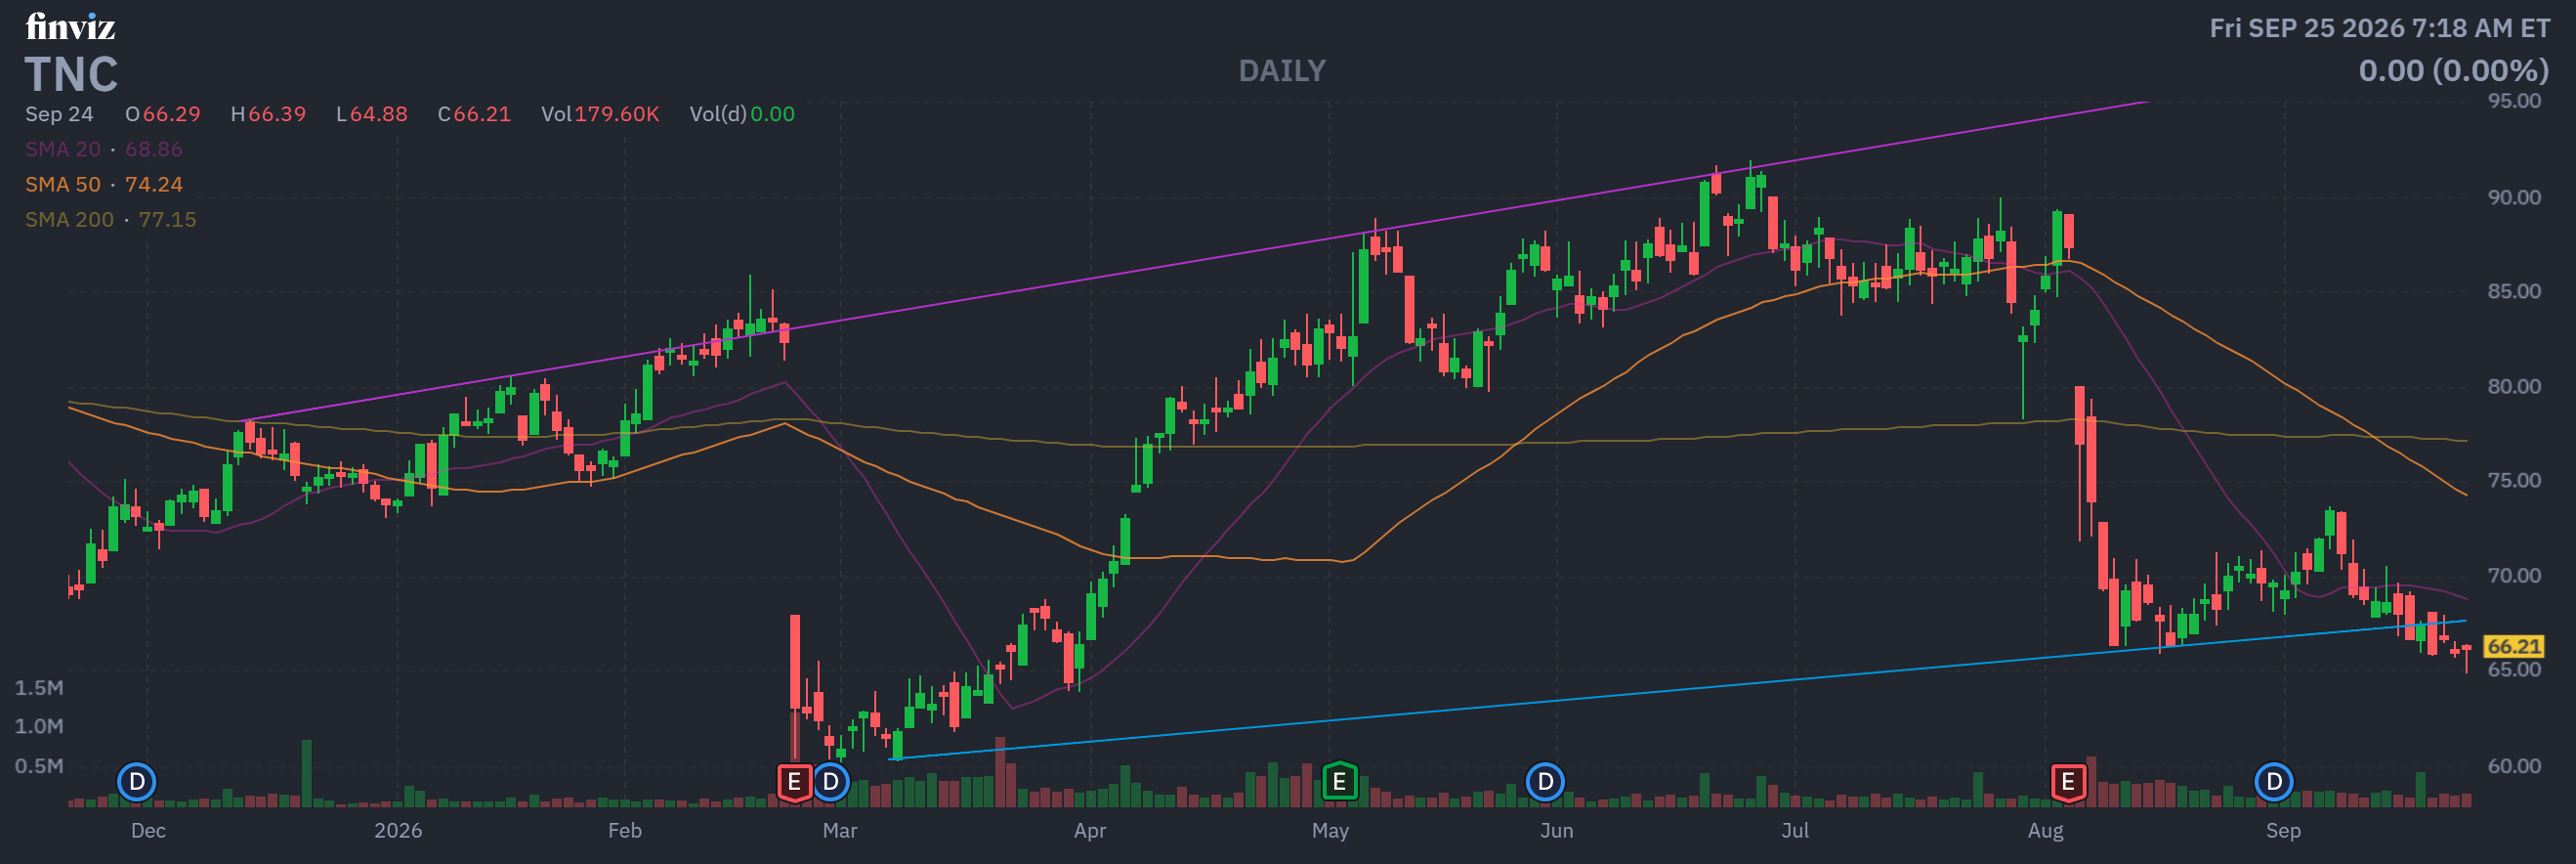
Transaction Date: 08-31-2026 Shares Bought: 3,000 shares an average price paid of $69.42 for Cost: $208,250
Company: Tennant Co. (TNC)
Tennant Company and its subsidiaries create, manufacture, and distribute floor cleaning equipment throughout the Americas, Europe, the Middle East, Africa, and Asia Pacific. The company provides manual and automated mechanized cleaning equipment for industrial and commercial use, detergent-free and other environmentally friendly cleaning technologies, aftermarket parts and consumables, and equipment maintenance and repair services. It also offers financing, rental and leasing programs, and machine-to-machine asset management services. It sells its goods to contract cleaners and businesses via direct sales and service organizations, as well as a network of approved distributors. Tennant Company was formed in 1870 and is based in Eden Prairie, Minnesota.
Patrick E. Allen has served as a Director of Tennant Co. since February 2026, when he joined the company’s Board of Directors as an independent director. He did not previously serve as an employee of Tennant. Allen most recently served as Chief Financial Officer of Collins Aerospace and previously held senior financial leadership roles at Rockwell Collins and Rockwell International. He began his career at Deloitte & Touche as an auditor and brings extensive experience in finance, strategic planning, risk management, and corporate governance. Allen earned a Bachelor of Science degree in Finance from Pennsylvania State University.
Insomniac Hedge Fund Guy Opinion: Tennant is a decent business having a bad year, and the stock’s trailing P/E of 63x doesn’t yet reflect that. The Perfect10 composite lands at a barely-positive +0.8 out of a possible +10 (mixed/neutral), with insiders buying and cash flow quality being the lone bright spots against a bearish industrials sector backdrop and a still-unresolved ERP mess. My DCF pegs fair value closer to $45-$55 a share against a $65.95 print, that’s a gap I’m not comfortable closing on faith in a robotics story that’s still tiny relative to the whole business. I’d stay on the sidelines until Q3 earnings in November show the ERP bleeding has actually stopped, this isn’t a stock to chase into a guidance cut with 8% of the float already betting against it.
Name: Alain Attal
Position: Director
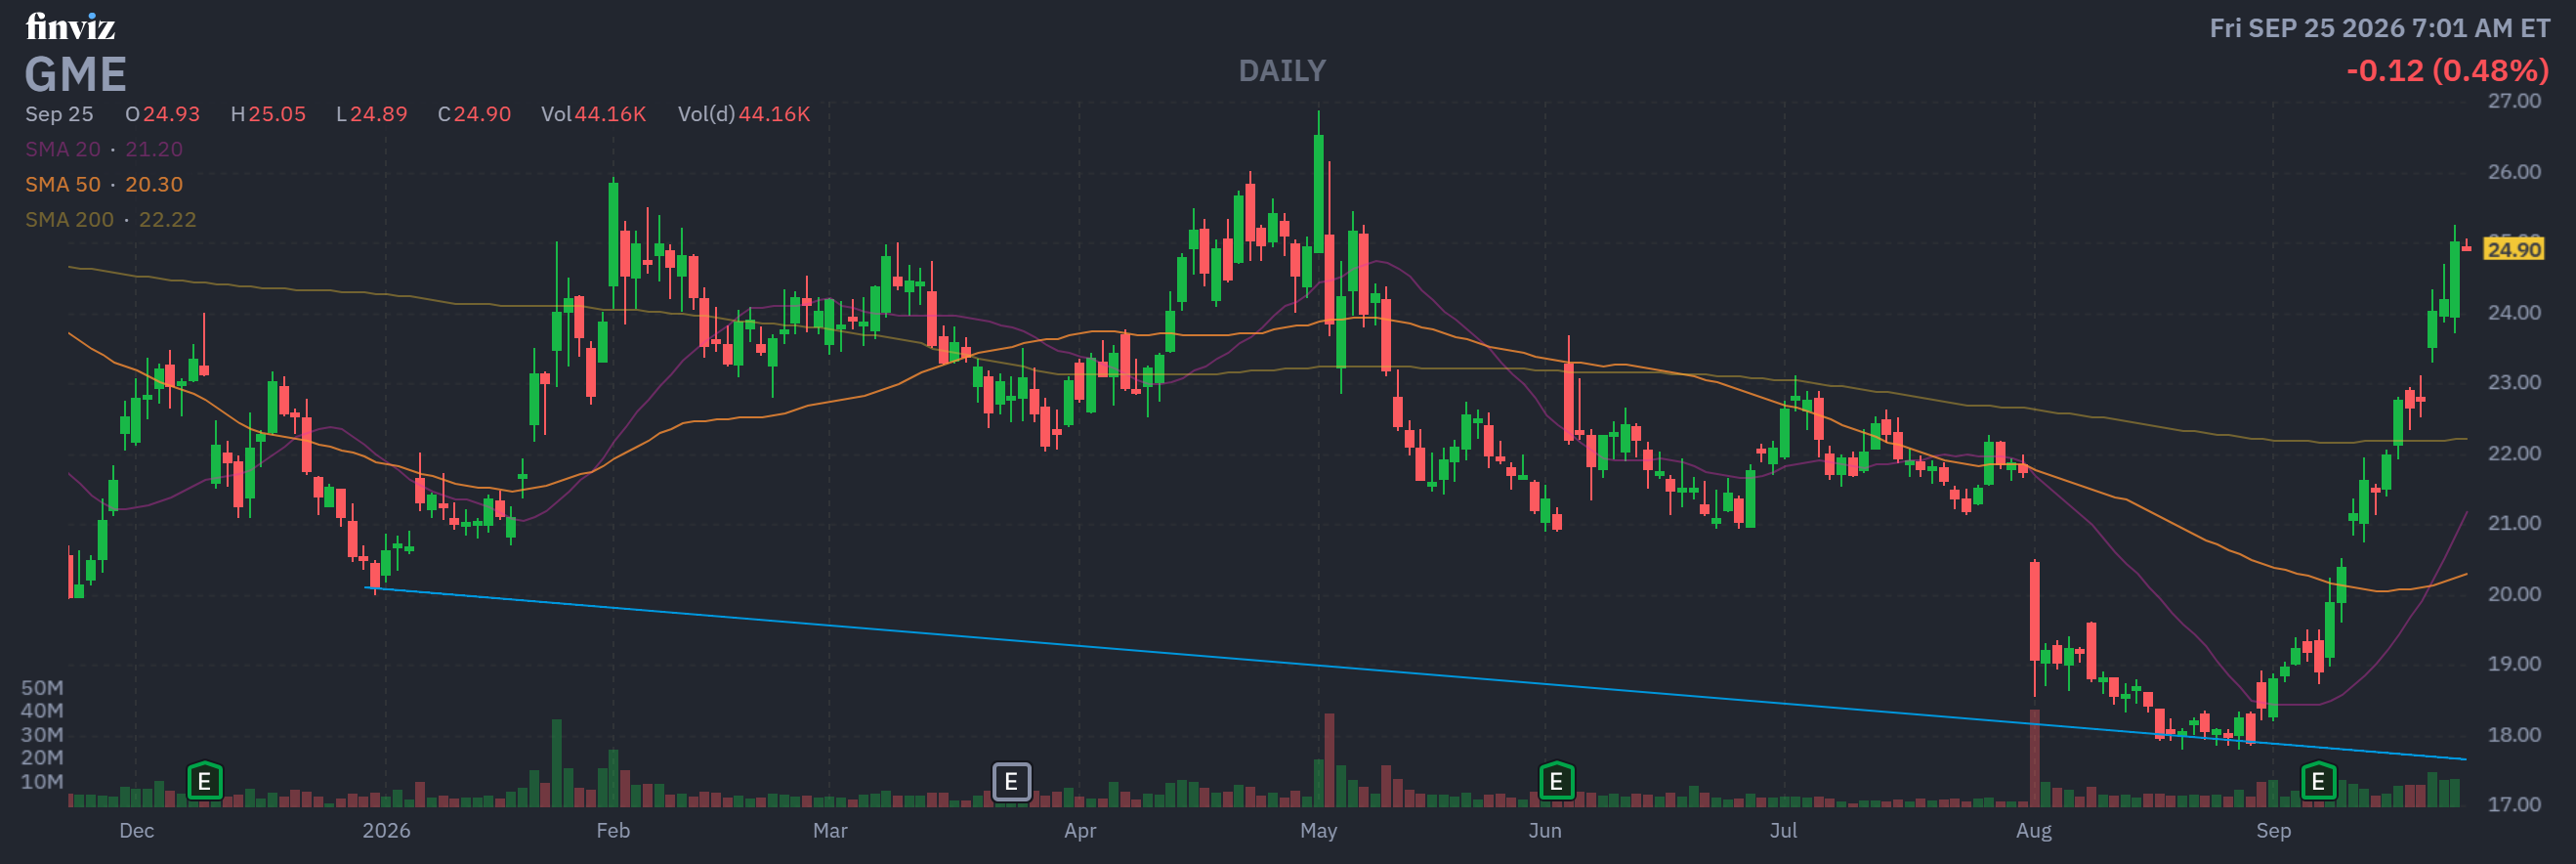
Transaction Date: 09-21-2026 Shares Bought: 17,500 shares an average price paid of $22.97 for Cost: $401,958
Name: Ryan Cohen
Position: President, CEO, and Chairman
Transaction Date: 09-21-2026 Shares Bought: 1,150,680 shares an average price paid of $22.94 for Cost: $26,393,723
Company: GameStop Corp. (GME)
GameStop Corp. is a specialty retailer that sells games, collectibles, and entertainment products through physical stores and e-commerce platforms in the United States, Australia, and Europe. The company provides new and pre-owned gaming platforms; accessories such as controllers, gaming headsets, and other peripheral devices; new and pre-owned gaming software; and in-game digital currency, digital downloadable content, and full-game downloads. It also sells memorabilia such as clothing, toys, trading cards, gadgets, and other retail items for pop culture and technology fans. GameStop Corp., formerly GSC Holdings Corp., was formed in 1996 and is headquartered in Grapevine, Texas.
Alain Attal joined GameStop Corp. as a Director in January 2021, when he was named to the Board of Directors with immediate effect. He is an e-commerce executive and entrepreneur with over 20 years of experience establishing and managing enterprises. Before to GameStop, he was Chewy’s Chief Operating Officer from 2011 to early 2017 and Chief Marketing Officer from 2017 to 2018. He is now GameStop’s Lead Independent Director, chairing the Compensation, Nominating, and Corporate Governance Committees.
Ryan Cohen has served as President, CEO, and Chairman of the Board of GameStop Corp. He joined GameStop’s Board of Directors in January 2021 and was appointed Executive Chairman in June 2023. He was appointed President and CEO of the company in September 2023, with immediate effect, and he continues to occupy these positions. Cohen is Chewy’s co-founder and former CEO, with substantial experience in e-commerce, technology, consumer enterprises, and capital allocation. He attended McMaster University but did not complete his degree.
Insomniac Hedge Fund Guy Opinion: GameStop the retailer is a fading business. GameStop the balance sheet and insider-conviction play is a different animal entirely. The DCF says fair value on fundamentals alone is closer to $16-$20, well under the $22.76 tape, but that ignores $46 million in fresh CEO buying and a short interest sitting near 14% of float with almost 10 days to cover. This is a hold-to-cautious-buy for anyone willing to bet on Cohen’s capital allocation skill and the collectibles pivot, not a stock to own on retail fundamentals alone. If you’re in it, you’re betting on the man in the corner office, not the guy behind the counter selling used copies of NBA 2K. Do your own homework here, this one moves on headlines as much as earnings.
Small fortunes get made or lost on earnings day, and GME’s next report in early December is exactly the kind of volatility event the EVS (earnings volatility screener) strategy is built for, worth a look if you trade around catalysts. I can also pull GameStop’s Perfect10 breakdown further or the insider selling side if any directors start heading for the exits, just say the word.
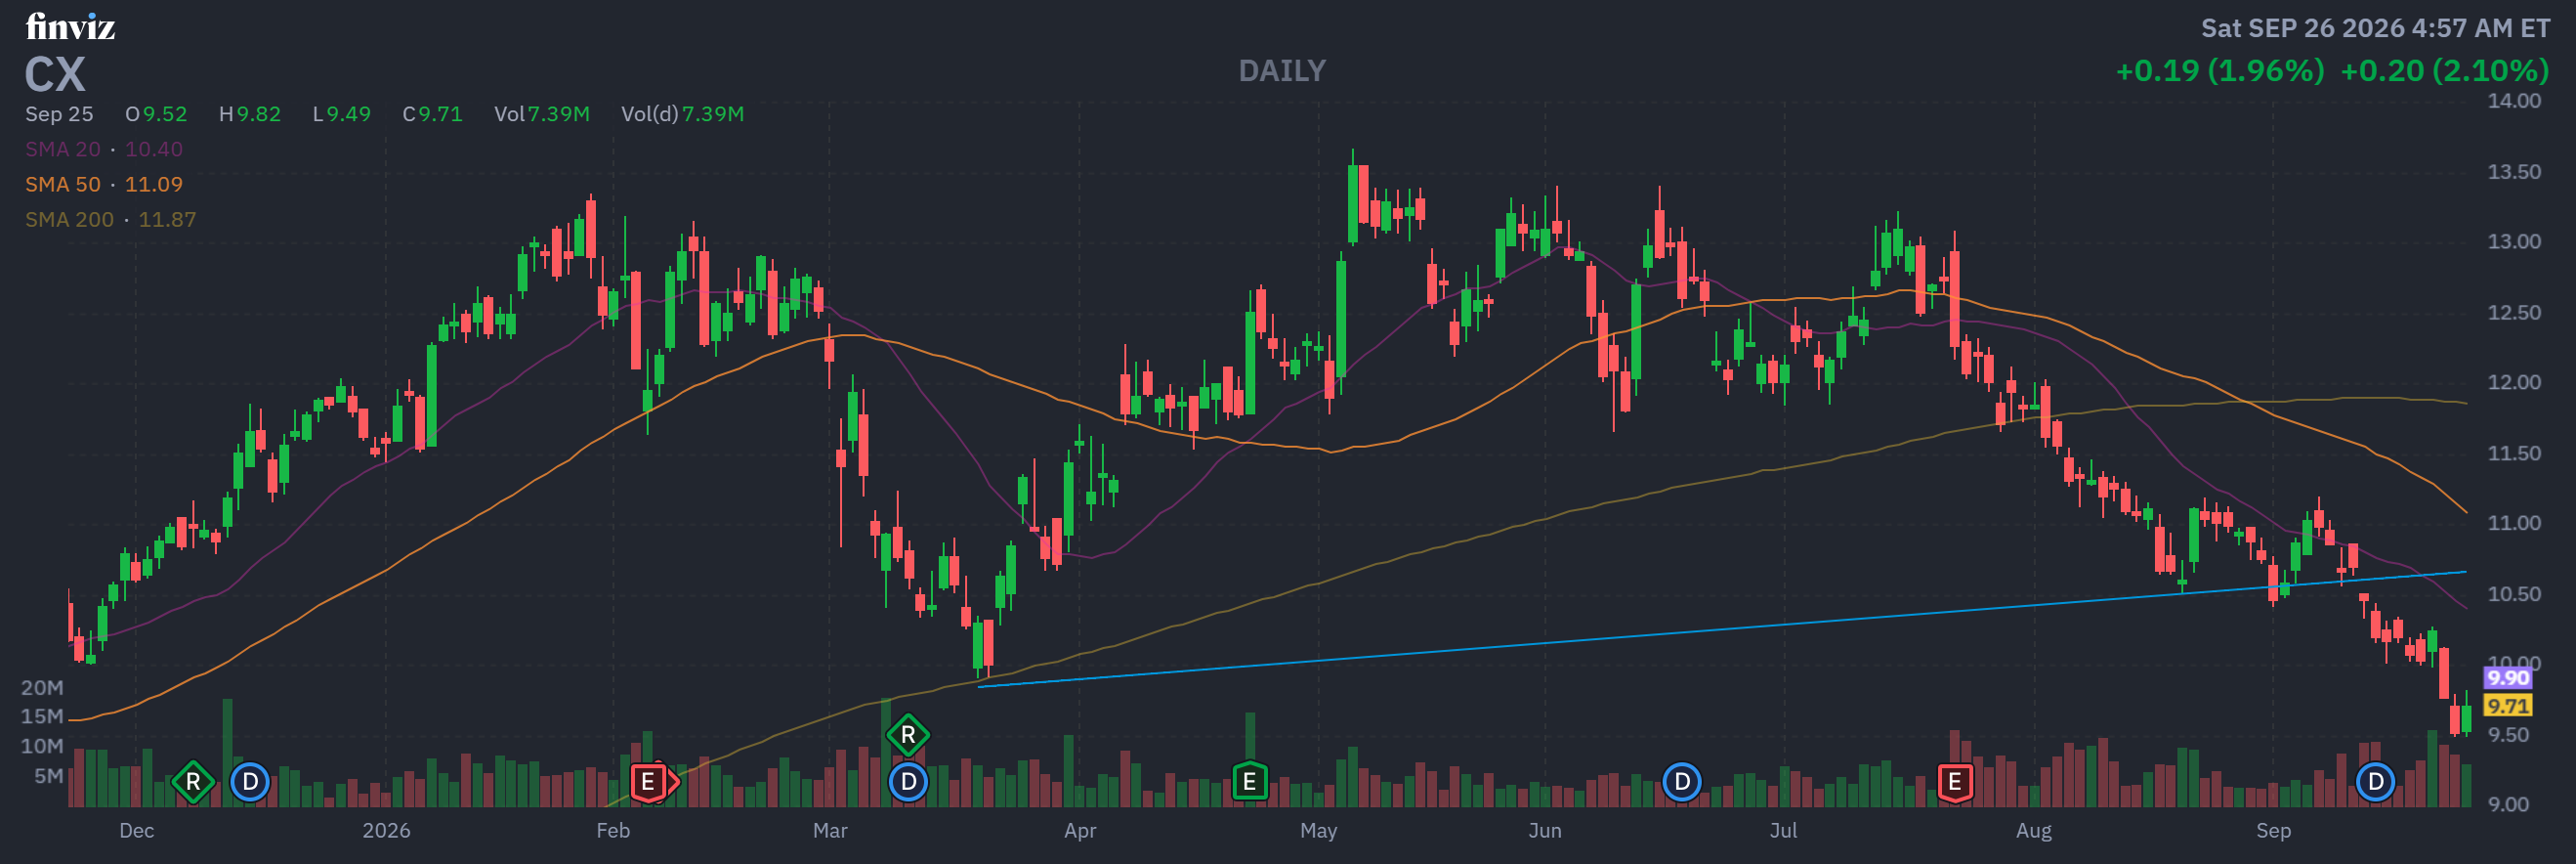
Name: Lozano Rogelio Zambrano
Position: Director
Transaction Date: 09-25-2026 Shares Bought: 400,800 shares an average price paid of $17.28 for Cost: $6,926,305
Company: CEMEX SAB DE CV (CX)
CEMEX, S.A.B. de C.V., through its subsidiaries, manufactures, markets, distributes, and sells cement, ready-mix concrete, aggregates, urbanization solutions, and other construction materials and services globally. It provides gray ordinary Portland, white Portland, and blended cement products; masonry or mortar products; standard ready-mix, architectural and decorative, rapid-setting, fiber-reinforced, fluid-fill, roller-compacted, self-consolidating, pervious, and antibacterial concrete products; aggregate products such as crushed stone and manufactured sand; gravel, sand, and recycled concrete; and vertua products. CEMEX, S.A.B. de C.V. was established in 1906 and is headquartered in San Pedro Garza García, Mexico.
Rogelio Zambrano Lozano joined CEMEX, S.A.B. de C.V., in 1977 and has held numerous positions in production, distribution, marketing, and strategic planning. He joined CEMEX’s Board of Directors in 1987 and became Chairman in 2014. He has substantial experience in the construction and building materials industries, having founded and served as co-CEO of Carza, a real estate development firm. He has a Bachelor of Science in Industrial and Systems Engineering from the Instituto Tecnológico y de Estudios Superiores de Monterrey and an MBA from the Wharton School of the University of Pennsylvania.
Insomniac Hedge Fund Guy Opinion: Perfect 10 composite score: +5.2 (Constructive), with bullish reads on analysts, insiders, cash flow, PEG, and valuation, offset by a bearish sector-outlook dimension. The stock is cheap on every multiple that matters, management is executing on margins and the balance sheet, and someone on the inside just wrote a $6.9 million check to buy shares. The knock is real too: growth is slow and the sector is fighting the tape. This is a value and turnaround play, not a growth story, buy it for the multiple gap and the balance-sheet improvement, not for excitement. Lean: Buy, for investors comfortable with cyclical, commodity-exposed industrials waiting for the market to catch up to the numbers.
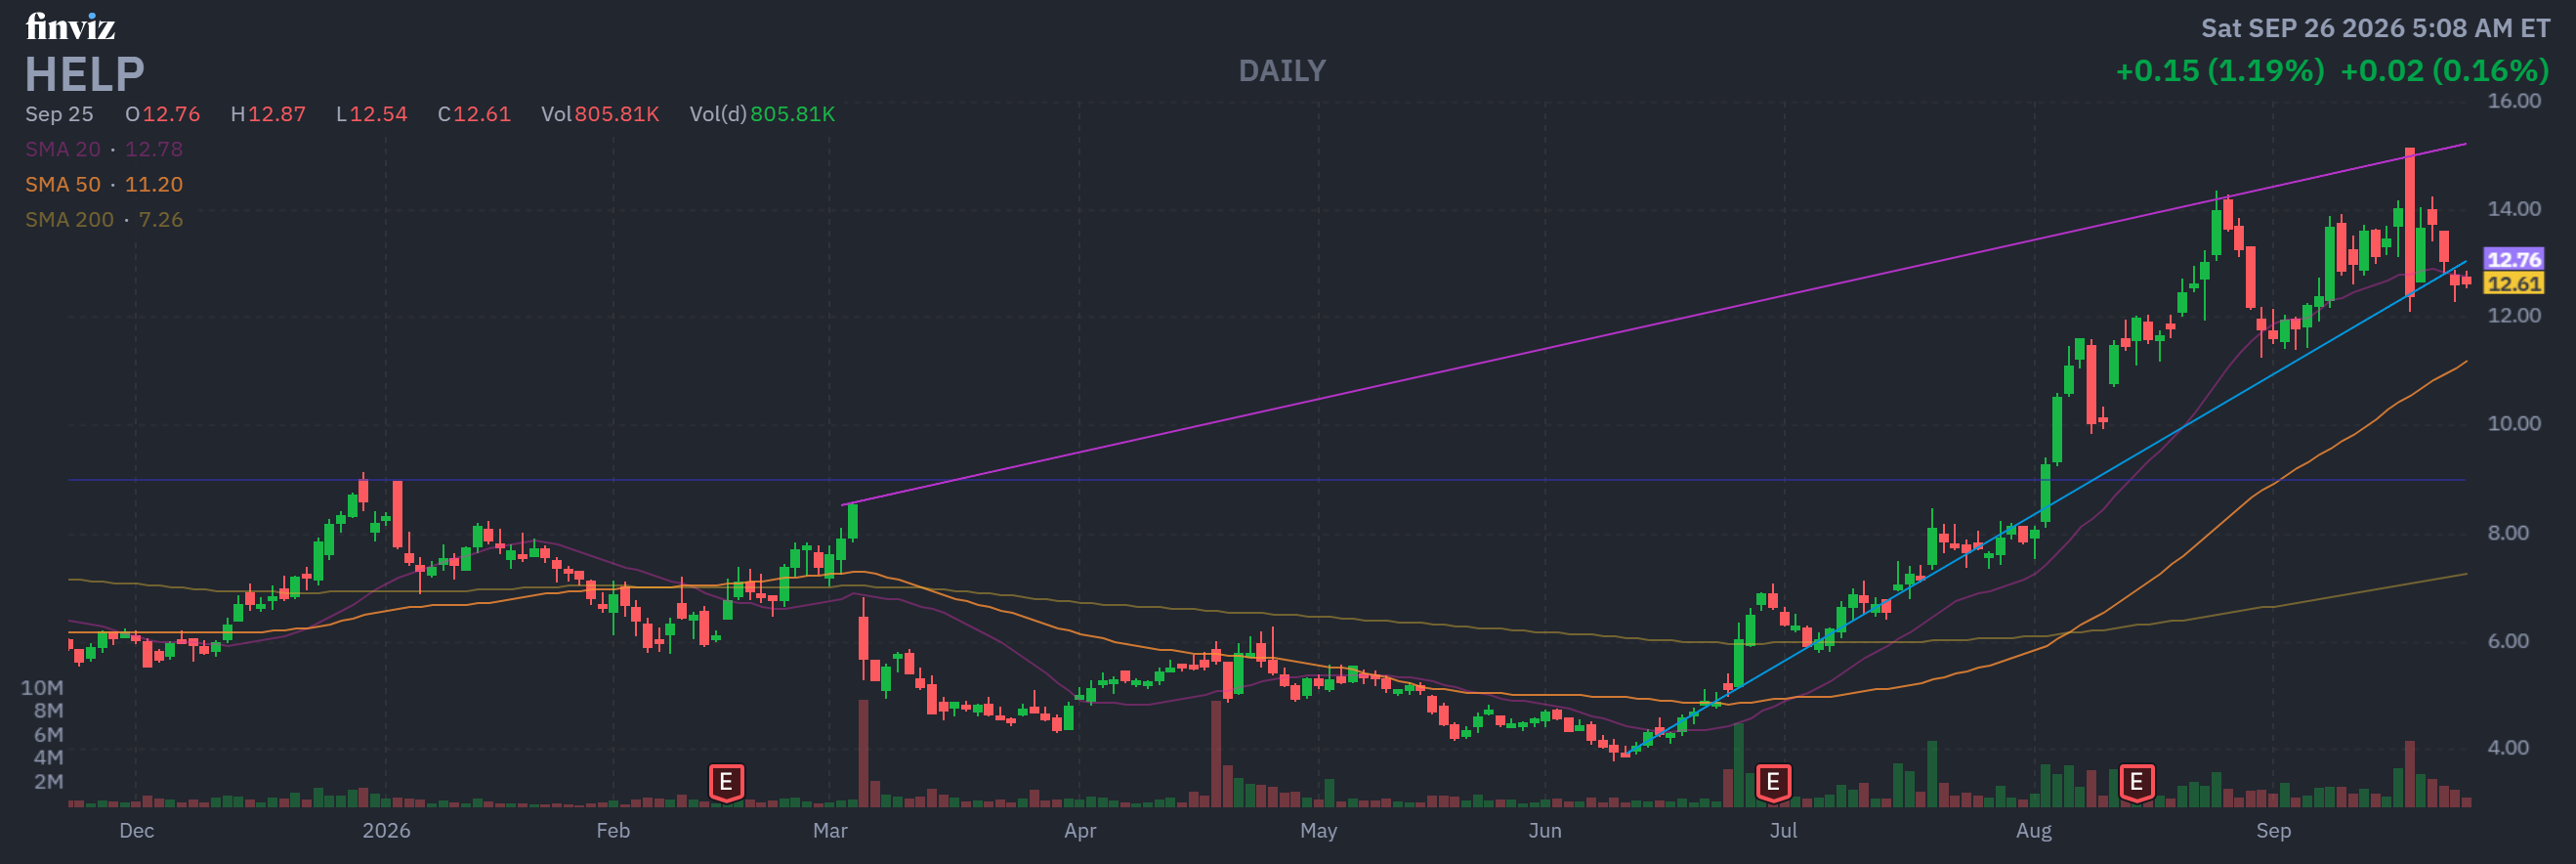
Name: Michael Halstead
Position: Chief Executive Officer
Transaction Date: 09-21-2026 Shares Bought: 100,000 shares an average price paid of $13.47 for Cost: $1,347,050
Company: Cybin Inc. (CYBN)
Cybin Inc., doing business as Helus Pharma, is a clinical-stage pharmaceutical firm focused on developing treatments to address a variety of psychiatric and neurological diseases.It is working on HLP003, a deuterated psilocybin analog that is in phase 3 clinical trials to treat major depressive disorder, and HLP004, a deuterated N, N-dimethyltryptamine that is in phase 2 clinical trials to treat generalized anxiety disorders. The company’s preclinical product is HLP005, a phenethylamine and tryptamine derivative used to treat the central nervous system. It has signed a strategic cooperation agreement with Segal Trials to evaluate HLP003 as an adjunctive treatment for major depressive disorder, as well as with Osmind for mental health treatments. The corporation is headquartered in Toronto, Canada.
Michael Halstead became CEO of Cybin Inc., now known as Helus Pharma, in August 2026, after being appointed to lead the firm through its late-stage clinical development and commercialization efforts. He has substantial pharmaceutical industry expertise, most recently serving as President of Intra-Cellular Therapies, where he helped develop and commercialize CAPLYTA and oversaw the company’s acquisition by Johnson & Johnson. He has previously held significant executive positions at Warner Chilcott. Halstead is not listed on Cybin’s board of directors. He earned a J.D. from Villanova University’s Charles Widger School of Law and a B.A. in International Relations from Boston University.
Insomniac Hedge Fund Guy Opinion: CYBN (soon fully known as HELP) is a high-conviction, high-risk biotech trade, not an investment in a business with earnings you can model. The insider buying here is the loudest part of the story: three top executives dropping over $8M of their own money in a two-week span ahead of major data readouts is not something you see from people who think the trial is going to flop. Combine that with Breakthrough Therapy Designation, a fortress-like $248M cash position, and real Phase 3 progress, and the bull case is legitimate.
But the stock already ran nearly 190% in three months, and 10-14% of the float is sold short by people betting against it. This is a “size it like a lottery ticket, not a core holding” situation: I lean bullish on the setup into the Q4 2026 data, but only for money you can genuinely afford to lose if the trial disappoints and this reprices toward single digits. Do your own diligence, and remember every syllable of this is educational analysis, not a recommendation.
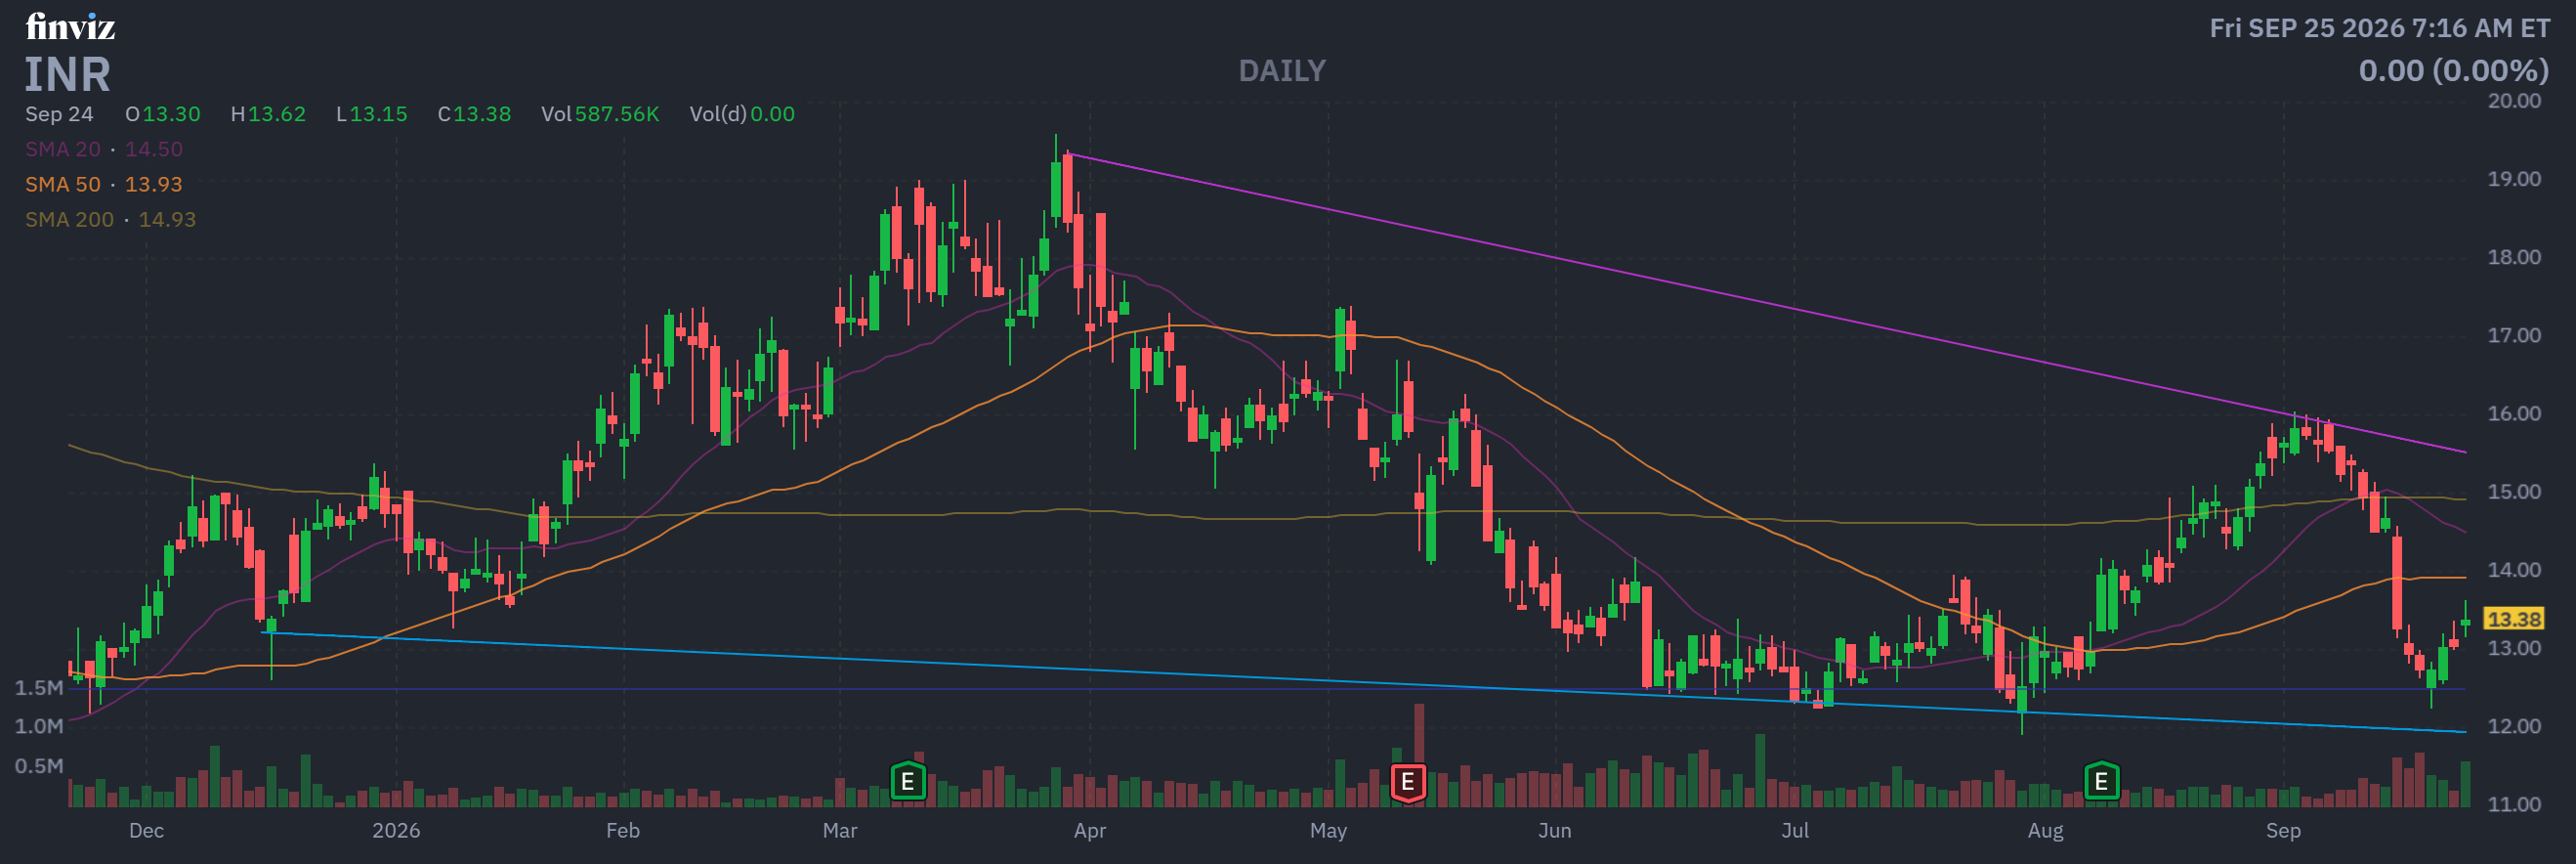
Name: Scott Gieselman
Position: Director
Transaction Date: 09-21-2026 Shares Bought: 28,467 shares an average price paid of $12.78 for Cost: $363,777
Company: Infinity Natural Resources Inc. (INR)
Infinity Natural Resources, Inc. is an independent energy company focused on acquiring, exploring, and developing properties in the United States that produce crude oil, natural gas, and natural gas liquids. The firm focuses on developing assets in the Utica Shale and Marcellus Shale formations of Ohio and Pennsylvania, where it has considerable acreage and strives to increase production through efficient drilling and operational procedures. Infinity Natural Resources intends to build long-term value by diversifying and optimizing its resource portfolio in major Appalachian Basin regions. The company was created in 2017 and is headquartered in Morgantown, West Virginia.
Scott Gieselman has been a Director of Infinity Natural Resources Inc. since January 2025, when he joined the company’s Board of Directors as an independent director. He formerly worked as a Partner at NGP Energy Capital Management from April 2007 to 2023, and also had different positions in Goldman Sachs’ energy investment banking business, eventually becoming a partner. Gieselman has also been on the boards of several energy firms, bringing vast knowledge of energy investing, finance, and corporate governance. He has a Bachelor of Science and a Master of Business Administration degree from Boston College.
Insomniac Hedge Fund Guy Opinion: INR is a buy for investors comfortable with commodity-cycle risk. The stock is statistically cheap on every multiple that matters (4.4x earnings, 0.13 PEG, sub-5x EV/EBITDA), cash flow quality is excellent, production is scaling fast, and a company director just backed up the bull case with real cash while the stock sits near 52-week lows. The 21%+ short interest is the market’s counter-argument, betting the Antero-driven leverage and preferred stock structure will bite if commodity prices turn. My read: the growth and cash generation outrun the leverage concern at this valuation, but this is a volatile, cyclical energy name, not a buy-and-forget position, size it accordingly and watch the debt covenants as closely as you watch the well data.
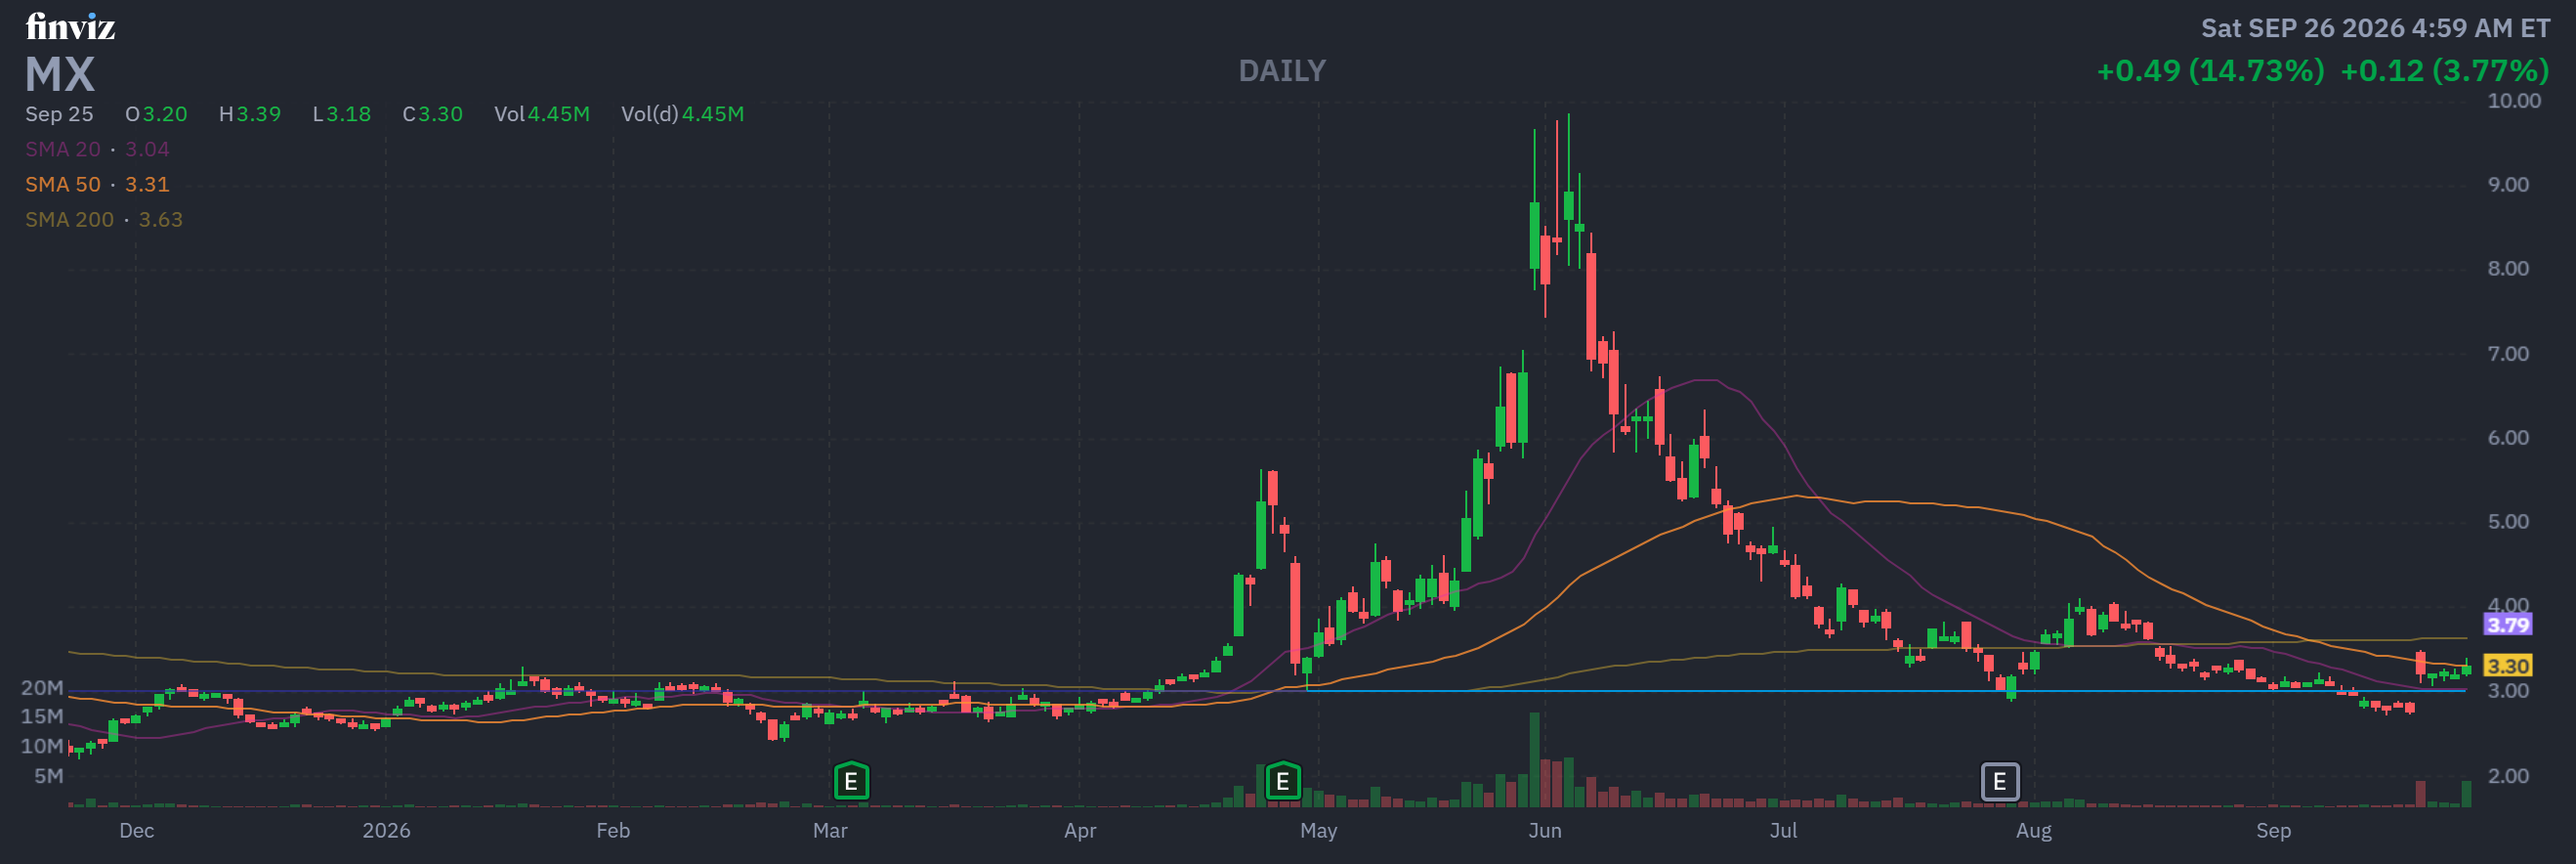
Name: Chae Lee
Position: Chief Executive Officer
Transaction Date: 09-23-2026 Shares Bought: 100,000 shares an average price paid of $3.19 for Cost: $318,496
Company: Magnachip Semiconductor Corp. (MX)
Magnachip Semiconductor Corporation develops, manufactures, and distributes analog and mixed-signal semiconductor products for communications, consumer electronics, computing, industrial, automotive, and Internet of Things applications. The company provides display solutions, such as source and gate drivers and timing controllers, for LCD, OLED, and Micro LED panels found in smartphones, televisions, automotive displays, monitors, notebooks, tablets, and other products. It also offers power semiconductors such as MOSFETs, IGBTs, AC-DC and DC-DC converters, LED drivers, regulators, and power management integrated circuits for both consumer and industrial applications. The company supports electronic manufacturers and designers in Korea, Asia Pacific, the United States, and Europe. Magnachip Semiconductor Corporation was founded in 2003 and is headquartered in Cheongju-si, South Korea.
Chae Lee became Chief Executive Officer of Magnachip Semiconductor Corporation in July 2026, when he was recruited to oversee the company’s next phase of expansion in power semiconductors and related technologies. He joined the Board of Directors simultaneously, starting in July 2026. Lee has over 30 years of worldwide semiconductor industry expertise, having previously served as CEO of Tagore Technology and held top leadership positions at InSyte Systems, NXP Semiconductors, and Maxim Integrated Products. He earned a Bachelor of Science in Electrical and Electronics Engineering from Missouri University of Science and Technology.
Insomniac Hedge Fund Guy Opinion: This is a broken-growth story wearing a turnaround costume. Five years of revenue nearly cut two-thirds, ongoing cash burn, no real competitive moat, and a business getting outgunned by bigger, better-funded rivals in a commodity market. The one thing keeping this from being a flat “avoid” is the new CEO putting real money behind the stock and the Navitas partnership giving the SiC pivot some external credibility, that’s worth watching, not worth chasing yet. Perfect 10 composite score: -0.1 (essentially neutral, tilted slightly bearish), which lines up with a stock caught between a legitimate insider-buying signal and genuinely ugly fundamentals. I’d call this a watch, not a buy, until the income statement actually confirms the turnaround the CEO is betting his own money on.
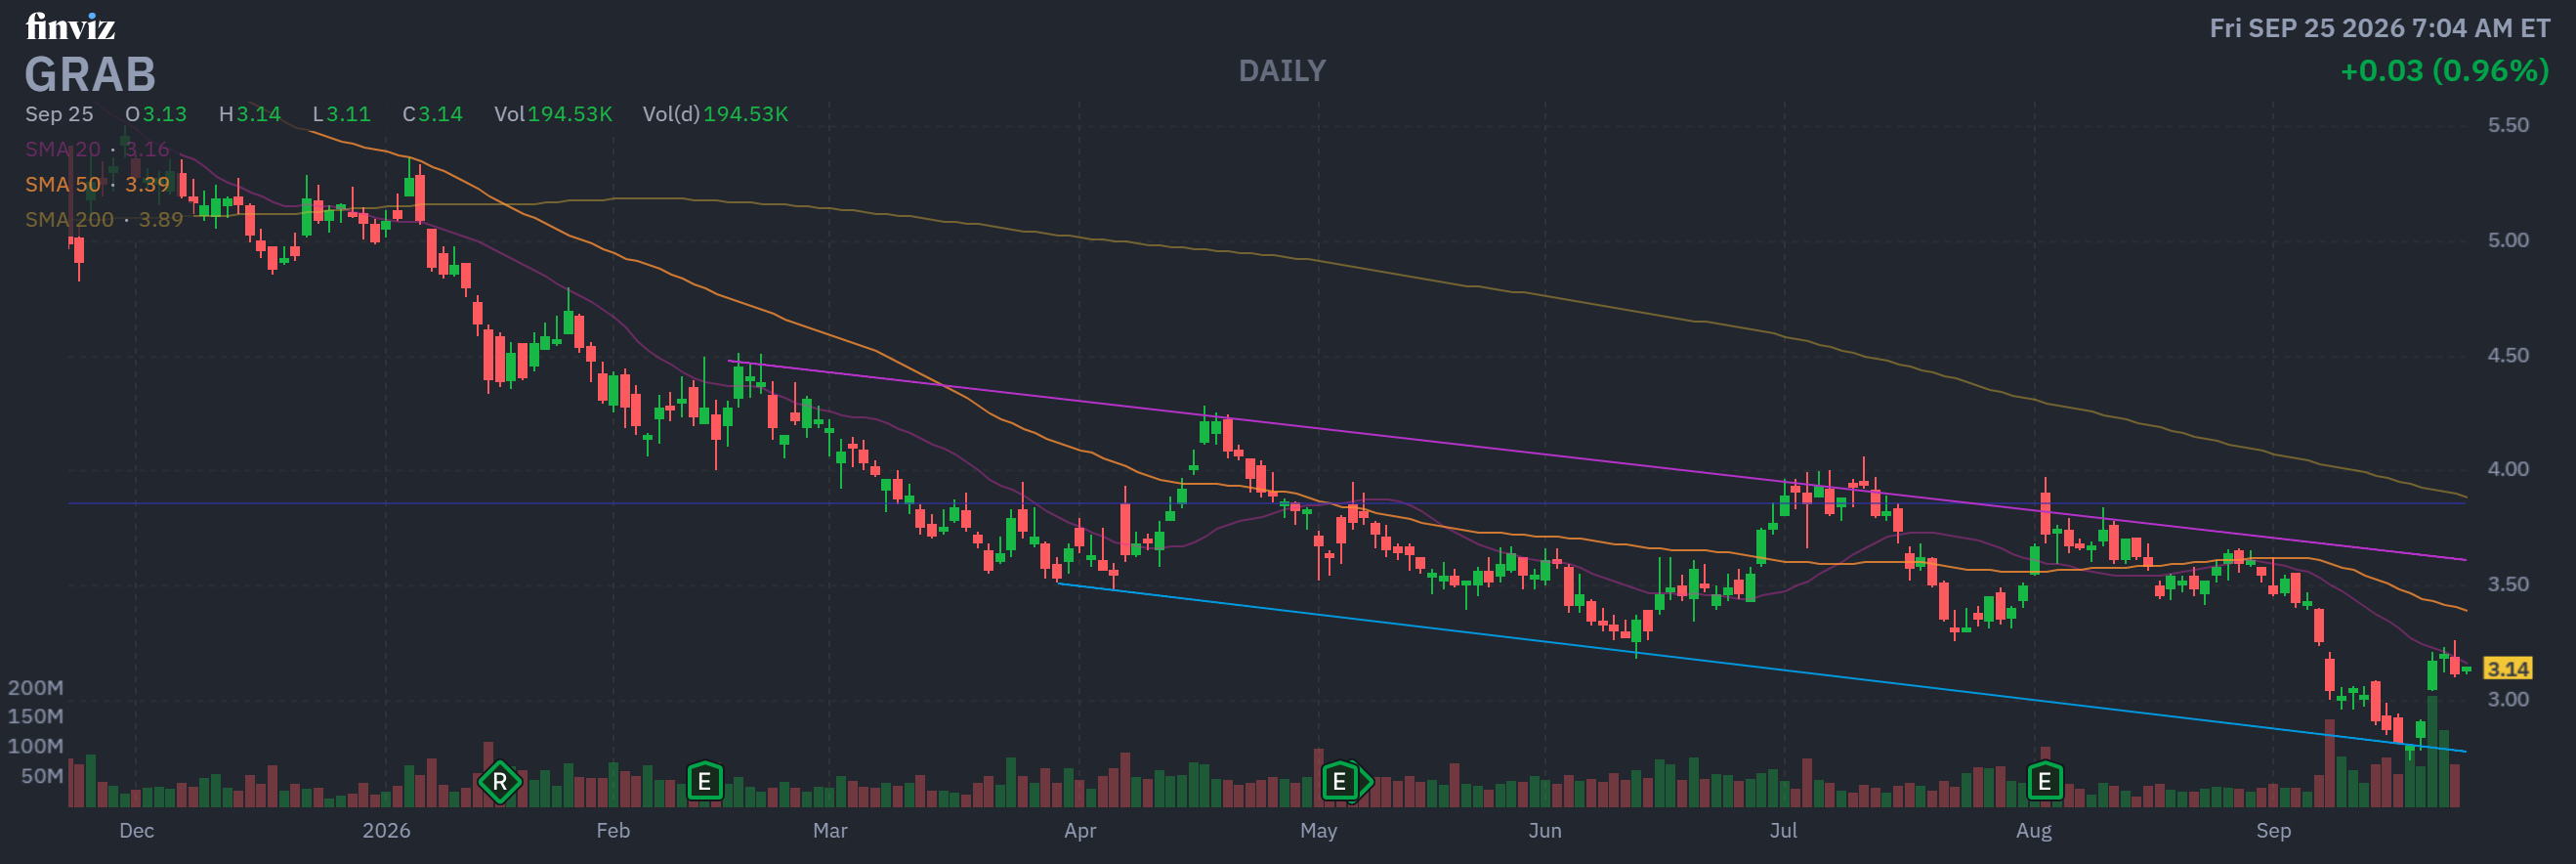
Name: Alexander Charles Hungate
Position: President and COO
Transaction Date: 09-21-2026 Shares Bought: 299,571 shares an average price paid of $2.89 for Cost: $866,839
Name: Anthony Ping Yeow Tan
Position: Chief Executive Officer
Transaction Date: 09-21-2026 Shares Bought: 10,350,000 shares an average price paid of $2.89 for Cost: $29,876,310
Company: Grab Holdings Ltd. (GRAB)
Grab Holdings Limited operates a superapp that offers delivery, mobility, banking, and digital services throughout Southeast Asia. Its platform includes GrabFood, GrabMart, GrabExpress, GrabCar, GrabTaxi, GrabBike, GrabRentals, and Grab for Business, which link customers, drivers, merchants, and enterprises. The company also provides digital payment and financial services through GrabPay, GrabFin, GrabInsure, and GrabLink, as well as digital banking solutions such as lending, insurance, payment, and financing. In addition, Grab offers advertising, loyalty, mapping, driverless vehicles, and last-mile delivery services. Grab Holdings Limited was created in 2012 and is based in Singapore, Singapore.
Alexander Charles Hungate is the President and Chief Operating Officer of Grab Holdings Ltd. (GRAB), having joined the company in 2026. He has served as a member of Grab’s Board of Directors since May 1, 2026, in addition to his executive role. Before joining Grab, Hungate served as President and CEO of SATS for eight years and previously held senior leadership positions at HSBC and Reuters. He brings more than 25 years of experience across financial services, logistics, and food solutions. He earned a degree in Engineering, Economics and Management from the University of Oxford and an MBA from Harvard Business School, where he graduated as a Baker Scholar.
Anthony Ping Yeow Tan is the co-founder and CEO of Grab Holdings Ltd. He joined the company when it was launched in 2012. He has been Grab’s Group CEO and Chairman of the Board since its inception. Tan worked in supply chain and marketing at Tan Chong Group before to starting Grab. Under his leadership, Grab grew from a cab booking service to a comprehensive digital platform that offers mobility, deliveries, and financial services. He earned a Bachelor of Arts with honors in Economics and Public Policy from the University of Chicago and an MBA with honors from Harvard Business School.
Insomniac Hedge Fund Guy Opinion: GRAB is a buy here, and the CEO just told you so with $29.9 million of his own cash. You’ve got a superapp that finally turned the corner into sustained profitability, a PEG ratio under 1 suggesting the market hasn’t caught up to the growth, and a Perfect Ten composite of +4.4 (Constructive) with bullish reads on analyst sentiment (Strong Buy, ~99% upside to target), insider activity, and catalysts. The knock is cash flow quality (operating cash flow badly lagging net income) and thin Deliveries margins, real issues worth watching next quarter, not deal-breakers. The Atome bet is a swing for the fences on fintech that could either be the next profit engine or an integration headache. Weigh the risk, but when a founder buys $30 million of stock into a 20% drawdown, that’s usually a signal worth listening to, not ignoring.
This blog is solely for educational purposes and the author’s own amusement. IT IS NOT INVESTMENT ADVICE. Think of the blog as part of my personal investment journal that I am willing to share with the DIY investor. We could be long, short, or have no position at all in any of the stocks mentioned and express no written or implied obligation to disclose any of that. Nothing contained here constitutes a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal, and past performance is not indicative of future results.
“The insomniac hedge fund guy” is a moniker Harvey Sax, the portfolio manager for The Insiders Fund” has used from time to time on email, blog ,and social media posts. While Mr. Sax is the portfolio manager of The Insiders Fund, these posts are not communications from, nor endorsed by, Alpha Wealth Funds, LLC or any of its managed funds. References to Alpha Wealth Funds or its affiliates are for identification only and do not imply sponsorship or approval.
All company names, logos, and trademarks belong to their respective owners. The use of company logos is solely for descriptive and illustrative purposes under fair use. Any information provided is based on publicly available data and should not be considered financial, investment, or legal advice. Readers should conduct their own research or consult with a professional before making any investment decisions. Insiders sell the stock for many reasons, but they generally buy for just one – to make money. You’ve always heard the best information is inside information. Everyone with any stock market experience pays close attention to what insiders are doing. After all, who knows a business better than the people running it? Officers, directors, and 10% owners are required to inform the public through a Form 4 Filing of any transaction, buy, sell, exercise, or any other within 48 hours of doing so.
This info is available for free from the SEC’s Web site, Edgar, although we subscribe to SECForm4 as they provide a way to manage and make sense of the vast realms of data. I’ve tried a lot of vendors. SECForm4 is one of the smaller ones, but I like supporting Frank. He is not arrogant. He’s helpful and has great prices. He also trades on his own data, so I like people that eat what they kill. The bar is different from selling because the natural state of management is to be a seller. This is because most companies provide significant amounts of management compensation packages as stock and options. Therefore, we analyze unusual patterns with selling, such as insiders selling 25 percent or more of their holdings or multiple insiders selling near 52-week lows. Another red flag is large planned sale programs that start without warning. Unfortunately, the public information disclosure requirements about these programs, referred to as Rule 10b5-1, are horrendously poor. Also, planned sales that pop up out of nowhere are basically sales and are seeking cover under this corporate welfare loophole.
I also generally ignore 10 percent shareholders as they tend to be OPM (other people’s money) and perhaps not the smart money on which we are trying to read the tea leaves. I say generally because some 10% shareholders are great investor, think Warren Buffett and others. Of course, insiders can also be wrong about their Company’s prospects. Don’t let anyone fool you into believing they never make mistakes. Do your own analysis. They can easily be wrong, and in many cases, maybe most cases, have no more idea what the future may hold than you or me. In short, you can lose money following them. We have, and we curse aloud; what were they thinking!
We like Fly on the Wall for keeping up with what events might be happening, analysts’ comments, and whatever else could be moving the stock. Dow Jones news service is an essential tool, but many services pick up their feed like they do Bloomberg. My assistant probes the 10k for a reasonable description of the business. I’ve found that to be the most accurate and succinct place to find out what a business actually does.
For more, please visit out website at https://insomniachedge.com/