I’m not feeling particularly optimistic about the market right now. With diesel and gasoline prices at record levels and a Fed Chairman intent on burnishing his inflation-fighting credentials, animal spirits are under significant pressure. The daily revenue and earnings beats that have propelled the market’s tech stack higher are now sidelined behind the quarterly earnings blackout curtains. It’s play time for the bears, and I expect them to continue to push the market lower.
Are insiders sniffing out genuine bargains, or are they simply fulfilling mandatory stock purchases as part of their employment agreements? You’ll have to read our analysis to get the answers. Every insider purchase is filtered through Veru 365’s “truth test” to determine the buyer’s real intent. A subscription to The Insomniac Hedge Fund Guy unlocks powerful financial AI tools, including our proprietary Attaboy strategy, which applies deep learning and sentiment analysis to decode analyst sentiment ahead of the Q3 earnings season.
Earnings Blackout: Oil Up, Interest Rates Up, Market Down—the game just got harder.
Name: Eric Mark Green
Position: Director
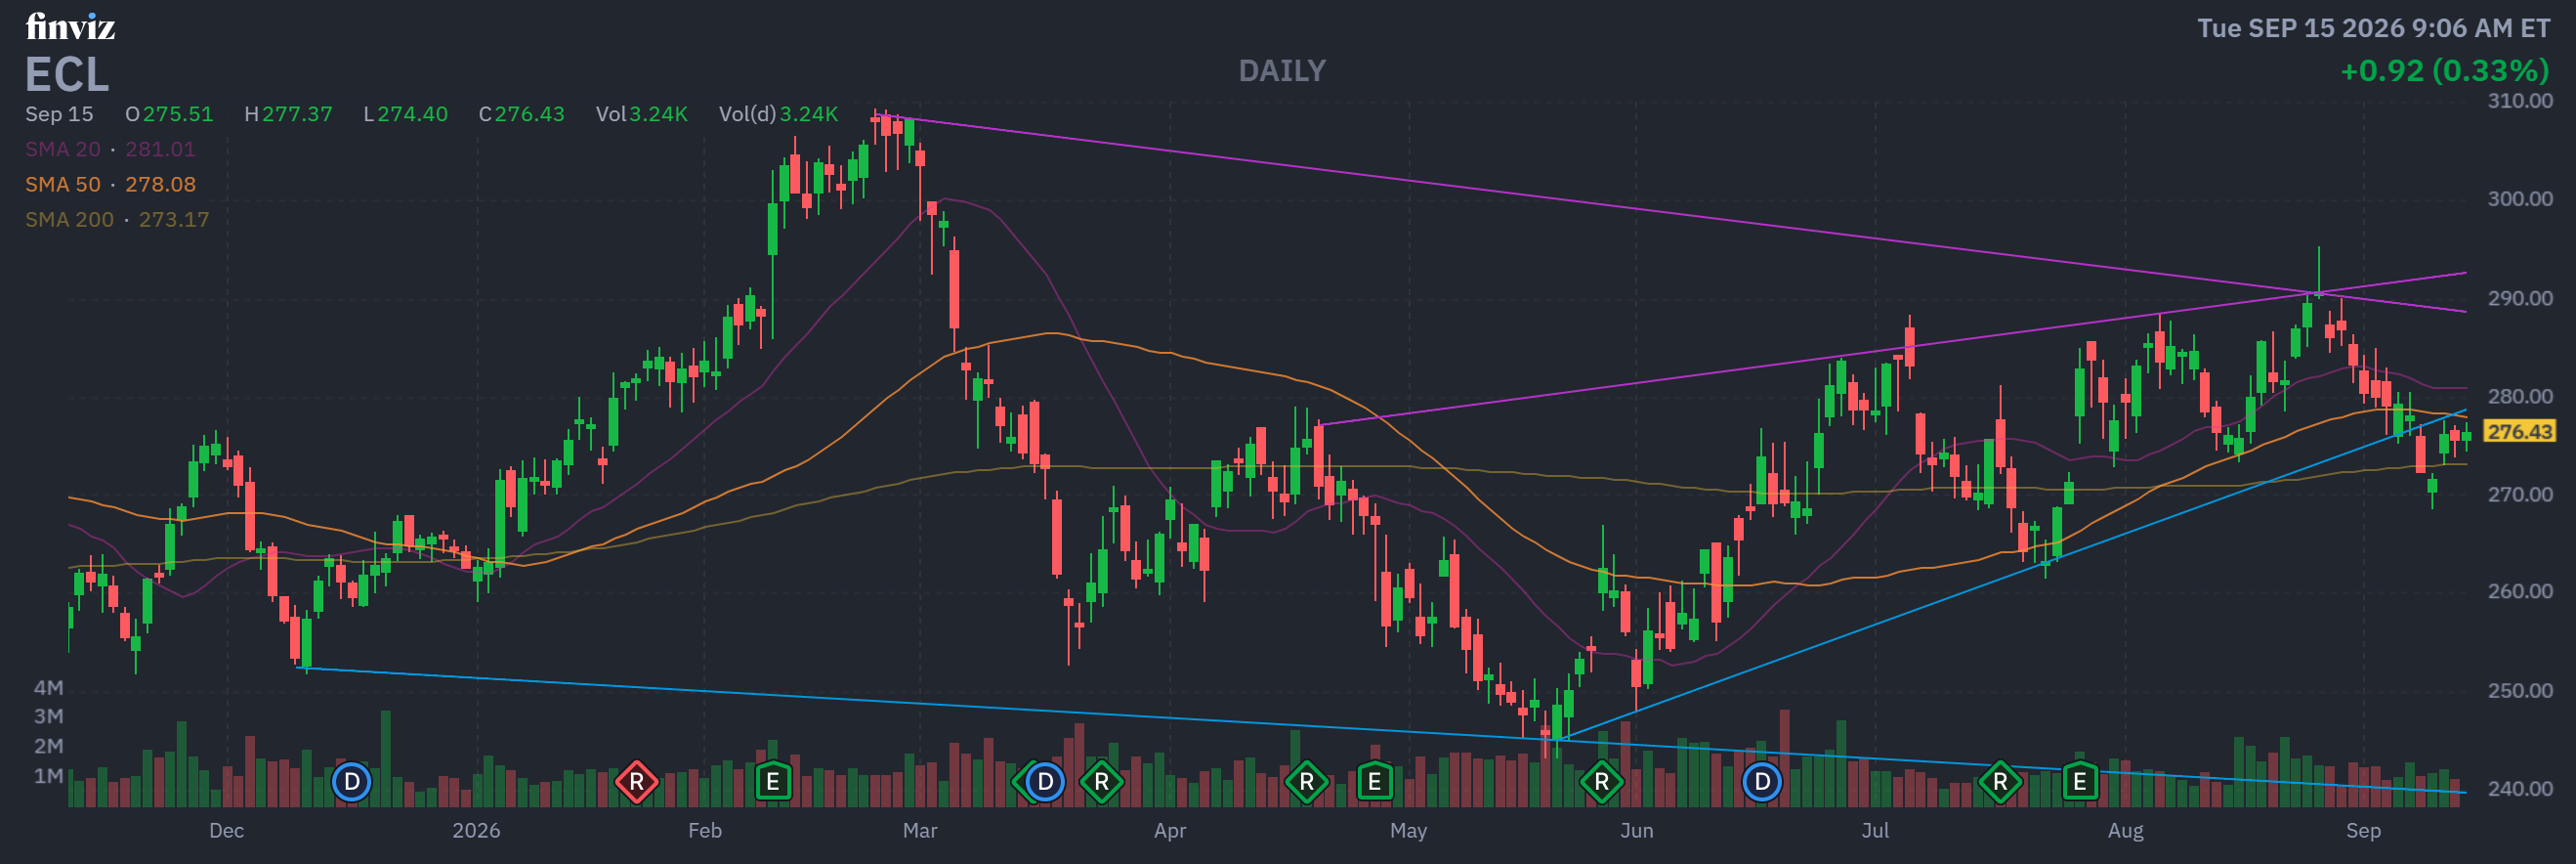
Transaction Date: 09-11-2026 Shares Bought: 3,690 shares an average price paid of $276.64 for Cost: $1,020,798
Company: Ecolab Inc. (ECL)
Ecolab Inc. offers water, hygiene, and infection prevention solutions and services in the United States and abroad. The company operates in four segments: Global Water, Global Institutional & Specialty, Global Pest Elimination, and Global Life Sciences. The Global Water business provides water treatment and processing applications, as well as cleaning and sanitation solutions. The Global Institutional & Specialty section offers cleaning and sanitizing solutions to the foodservice, healthcare, hospitality, lodging, government, education, and retail sectors. The Global Pest Elimination segment offers pest elimination services for detecting, preventing, and eliminating pests. The Global Life Sciences section offers cleaning and contamination control solutions for pharmaceuticals and personal care. Ecolab Inc. was formed in 1923 and is based in St. Paul, Minnesota.
Eric Mark Green has served as an Independent Director of Ecolab Inc. since December 8, 2022, when he was named to the company’s Board of Directors. He did not join Ecolab as an employee; his involvement with the company began with his Board appointment. Green has approximately 30 years of expertise in the life sciences business and presently serves as the Chairman, President, and CEO of West Pharmaceutical Services. Throughout his 20-year tenure at Sigma-Aldrich, he held a variety of leadership responsibilities. He received his undergraduate degree from Bethel University and his MBA from Washington University’s Olin Business School in St. Louis.
Insomniac Hedge Fund Guy Opinion: Ecolab is a wonderful business trading at a full price. The moat is real, the recurring-revenue engine is durable, and the AI data-center cooling pivot gives this “boring” chemicals company a legitimate second act. But a PEG of 2.48 and a DCF that lands right around the current price tell you the market has already priced in a lot of that good news. The Perfect10 composite came in at a mixed +1.8 (bullish analysts and insider buying offset by a stretched valuation and a weak sector backdrop), the score sums each dimension on a -10 to +10 scale). This is a hold for existing owners and a “wait for a real pullback” name for new money, not a stock I’d chase at $275 with the sector working against it.
Name: Kenneth S. Courtis.
Position: Director
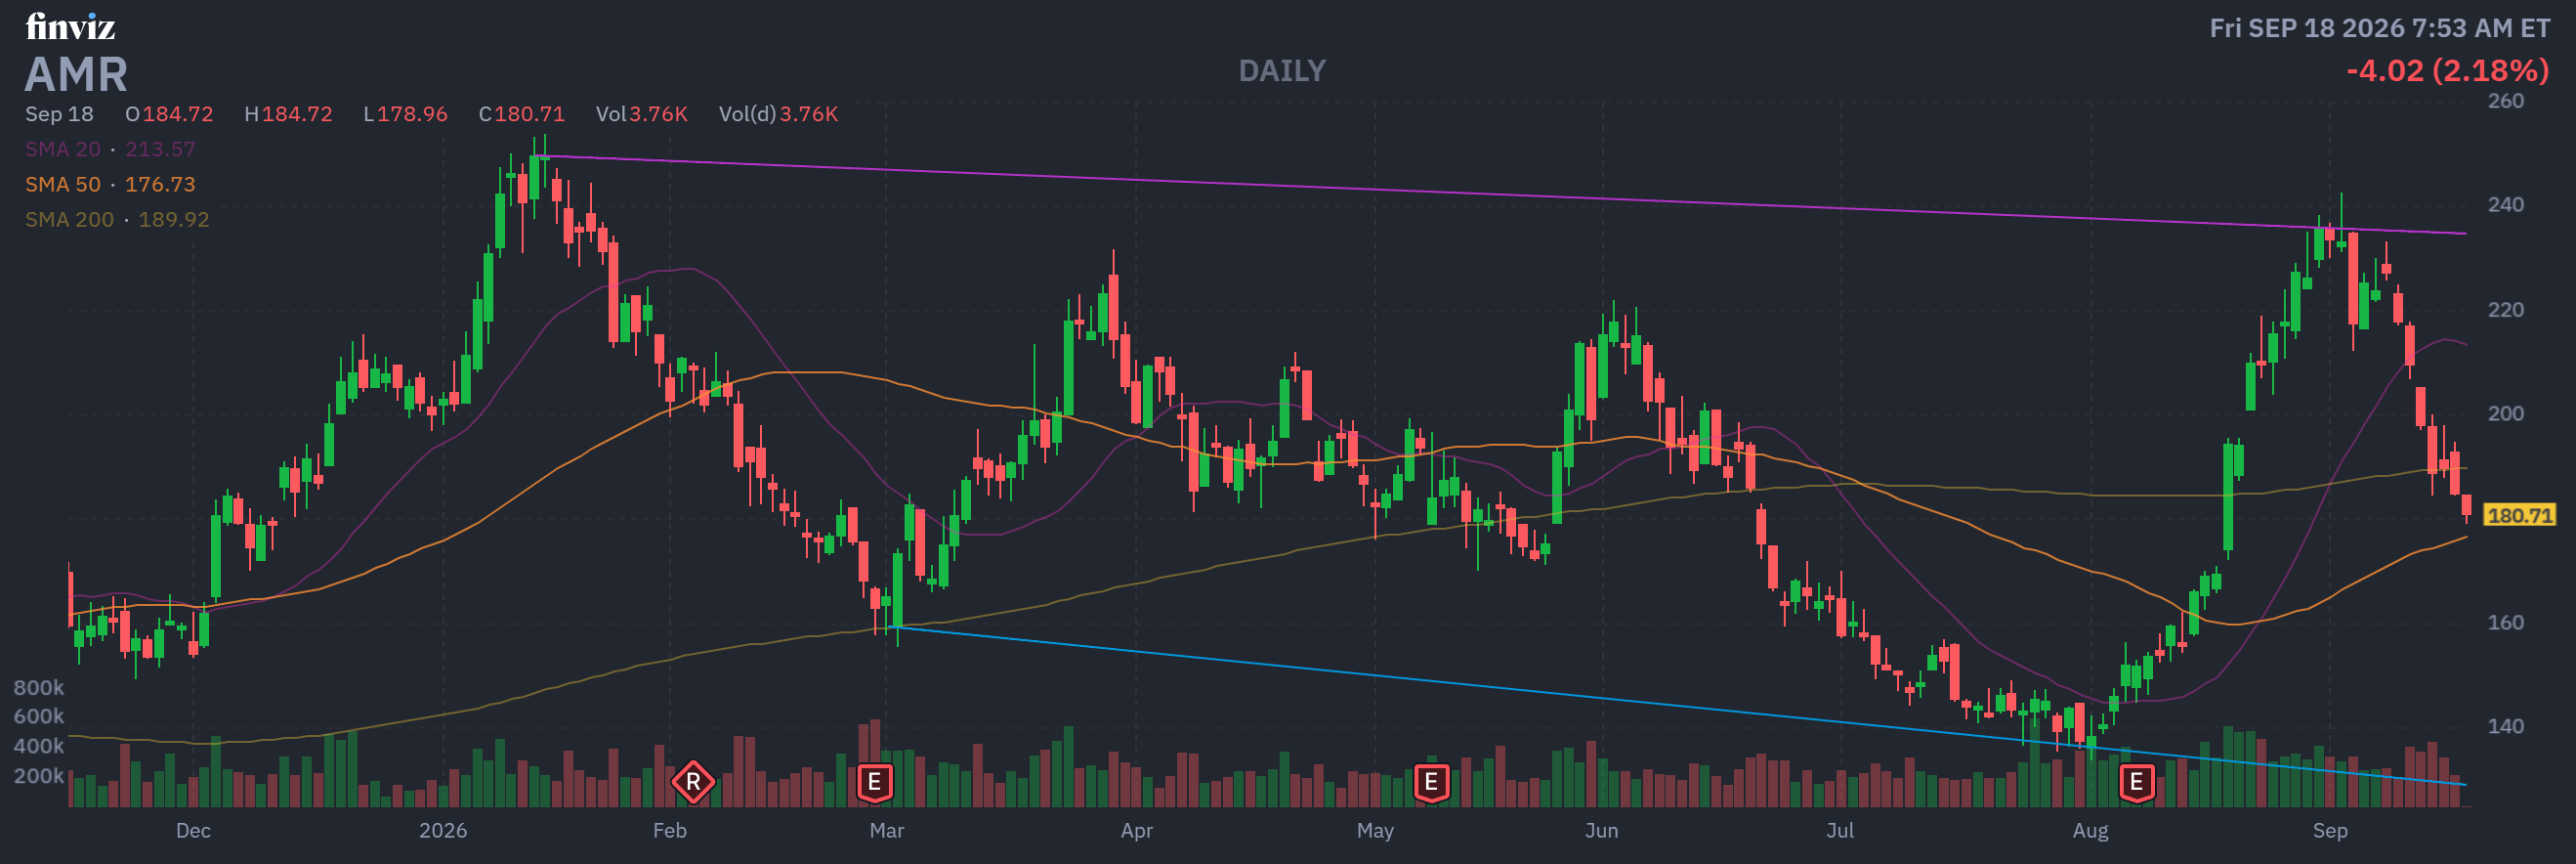
Transaction Date: 03-12-2026 Shares Bought: 8,000 shares an average price paid of $191.07 for Cost: $1,528,550
Company: Alpha Metallurgical Resources Inc. (AMR)
Alpha Metallurgical Resources, Inc. is a mining firm that produces, processes, and sells met and thermal coal in Virginia and West Virginia. The company offers metallurgical coal products. It runs nineteen operating mines and eight active coal processing and loading facilities. The company was formerly known as Contura Energy, Inc. before changing its name to Alpha Metallurgical Resources, Inc. in April 2017. Alpha Metallurgical Resources, Inc. was established in 2016 and is based in Bristol, Tennessee.
Kenneth S. Courtis has been serving as director of Alpha Metallurgical Resources Inc. since February 2021. He has also been chairman of Starfort Investment Holdings since 2009. Mr. Courtis has more than 30 years of experience in corporate finance, investments, and nearly every facet of the commodity sector. Throughout his career, he has served on the boards or advisory councils of several significant worldwide corporations. Mr. Courtis holds an undergraduate degree from Glendon College in Toronto and a master’s degree in international relations from Sussex University in the UK. He holds a master’s degree in business administration from the European Institute of Business Administration as well as a doctorate with highest distinction from Sciences Po in Paris.
Insomniac Hedge Fund Guy Opinion: AMR is a coal miner riding the down-leg of a commodity cycle: revenue is cut nearly in half from the 2022 peak, guidance just got trimmed again, and the stock carries a chunky 12%+ short interest. On paper that’s a “stay away” setup. But the Perfect Ten composite comes in essentially flat at -0.2 on the -10 to +10 scale (a neutral, mixed read), and the detail matters more than the headline: management is buying back stock aggressively and 16 insider purchases totaling $11.7 million just hit the tape while the stock was under pressure from the guidance cut. That’s not noise, that’s people with the best information in the building putting money on the table. My take: this is a hold-to-speculative-buy for anyone who believes met coal pricing troughs here rather than falls further, the DCF backs up “fairly valued, not cheap, not expensive.” I wouldn’t chase it, but I also wouldn’t bet against the insiders. Do your own homework before sizing a position in a name this cyclical.
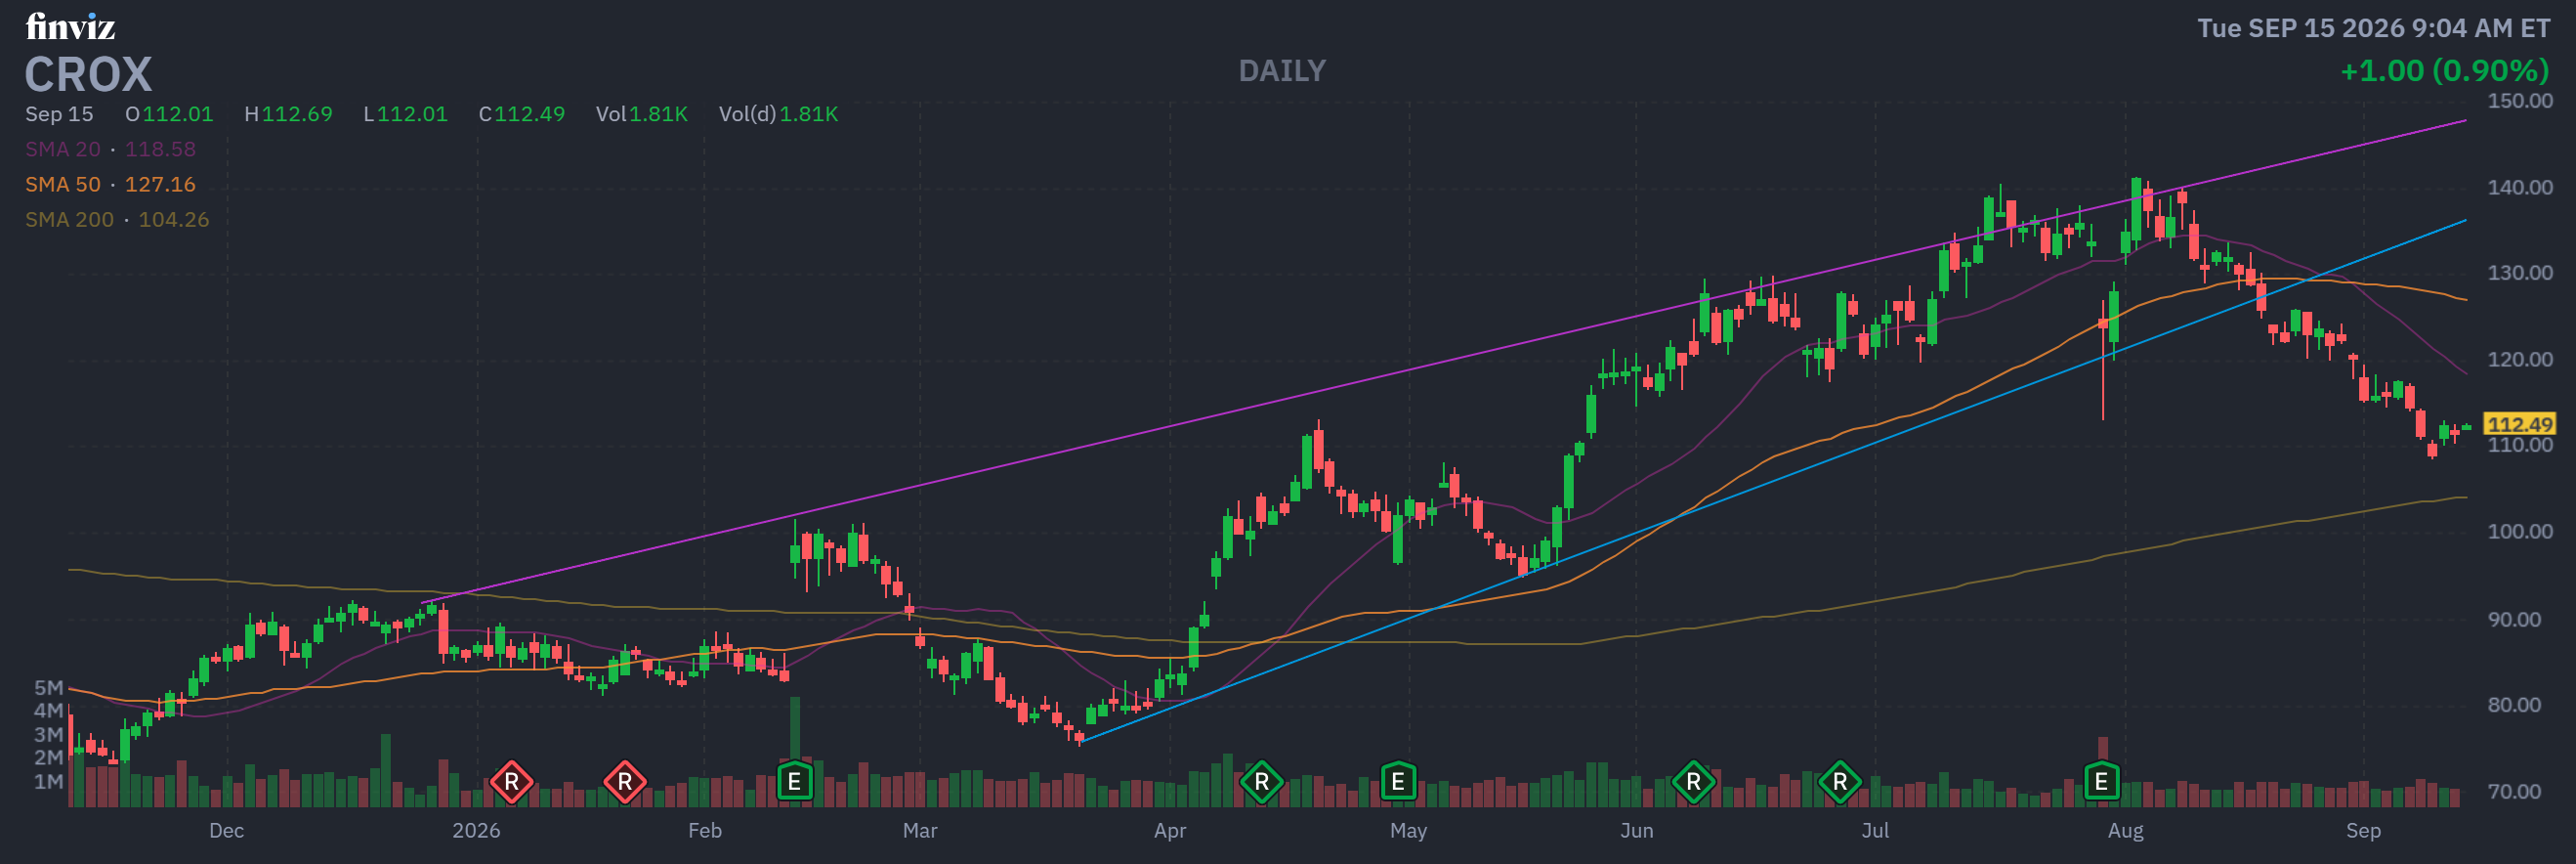
Name: Thomas J. Smach
Position: Director
Transaction Date: 09-10-2026 Shares Bought: 4,000 shares an average price paid of $109.38 for Cost: $437,530
Company: Crocs Inc. (CROX)
Crocs, Inc. and its subsidiaries design, develop, manufacture, market, distribute, and sell casual lifestyle footwear and accessories for men, women, and children under the Crocs and HEYDUDE brands in the United States and around the world. The company sells a wide range of footwear, such as clogs, sandals, loafers, classics, fuzz, platforms, boots, sandals, slides, slippers, sneakers, flip flops, and flats, as well as totes, backpacks, belt bags, socks, bag charms, cases, attachments, cartoon character products, touchland, and other accessories. It offers its goods through wholesalers, retail stores, e-commerce sites, third-party marketplaces, outlet stores, and kiosks/store-in-stores. Crocs, Inc. was formed in 1999 and is based in Broomfield, Colorado.
Thomas J. Smach has been a Director of Crocs, Inc. since April 2005, and he has served as chairperson of the board since June 2011. He is a co-founder of Riverwood Capital Management, which he has led since 2008, and he previously worked as Flextronics International’s Chief Financial Officer. He has vast experience in finance, accounting, technology, and serving on public business boards. Mr. Smach earned a B.Sc. in Accounting from the State University of New York at Binghamton and is a certified public accountant.
Insomniac Hedge Fund Guy Opinion: Crocs is a cheap stock attached to a real brand that’s still growing, wrapped in a legal and turnaround story that’s scaring more people than it should. The core Crocs brand just posted its first $1 billion quarter, HEYDUDE’s decline is narrowing instead of worsening, and management is buying back stock like it means it. At under 8x forward earnings with double-digit free cash flow yield, this looks priced for permanent HEYDUDE failure, not the gradual stabilization actually showing up in the numbers. I’m calling CROX a buy here, with the caveat that the securities litigation is a real tail risk worth watching, not dismissing. This isn’t investment advice, do your own homework before sizing a position.
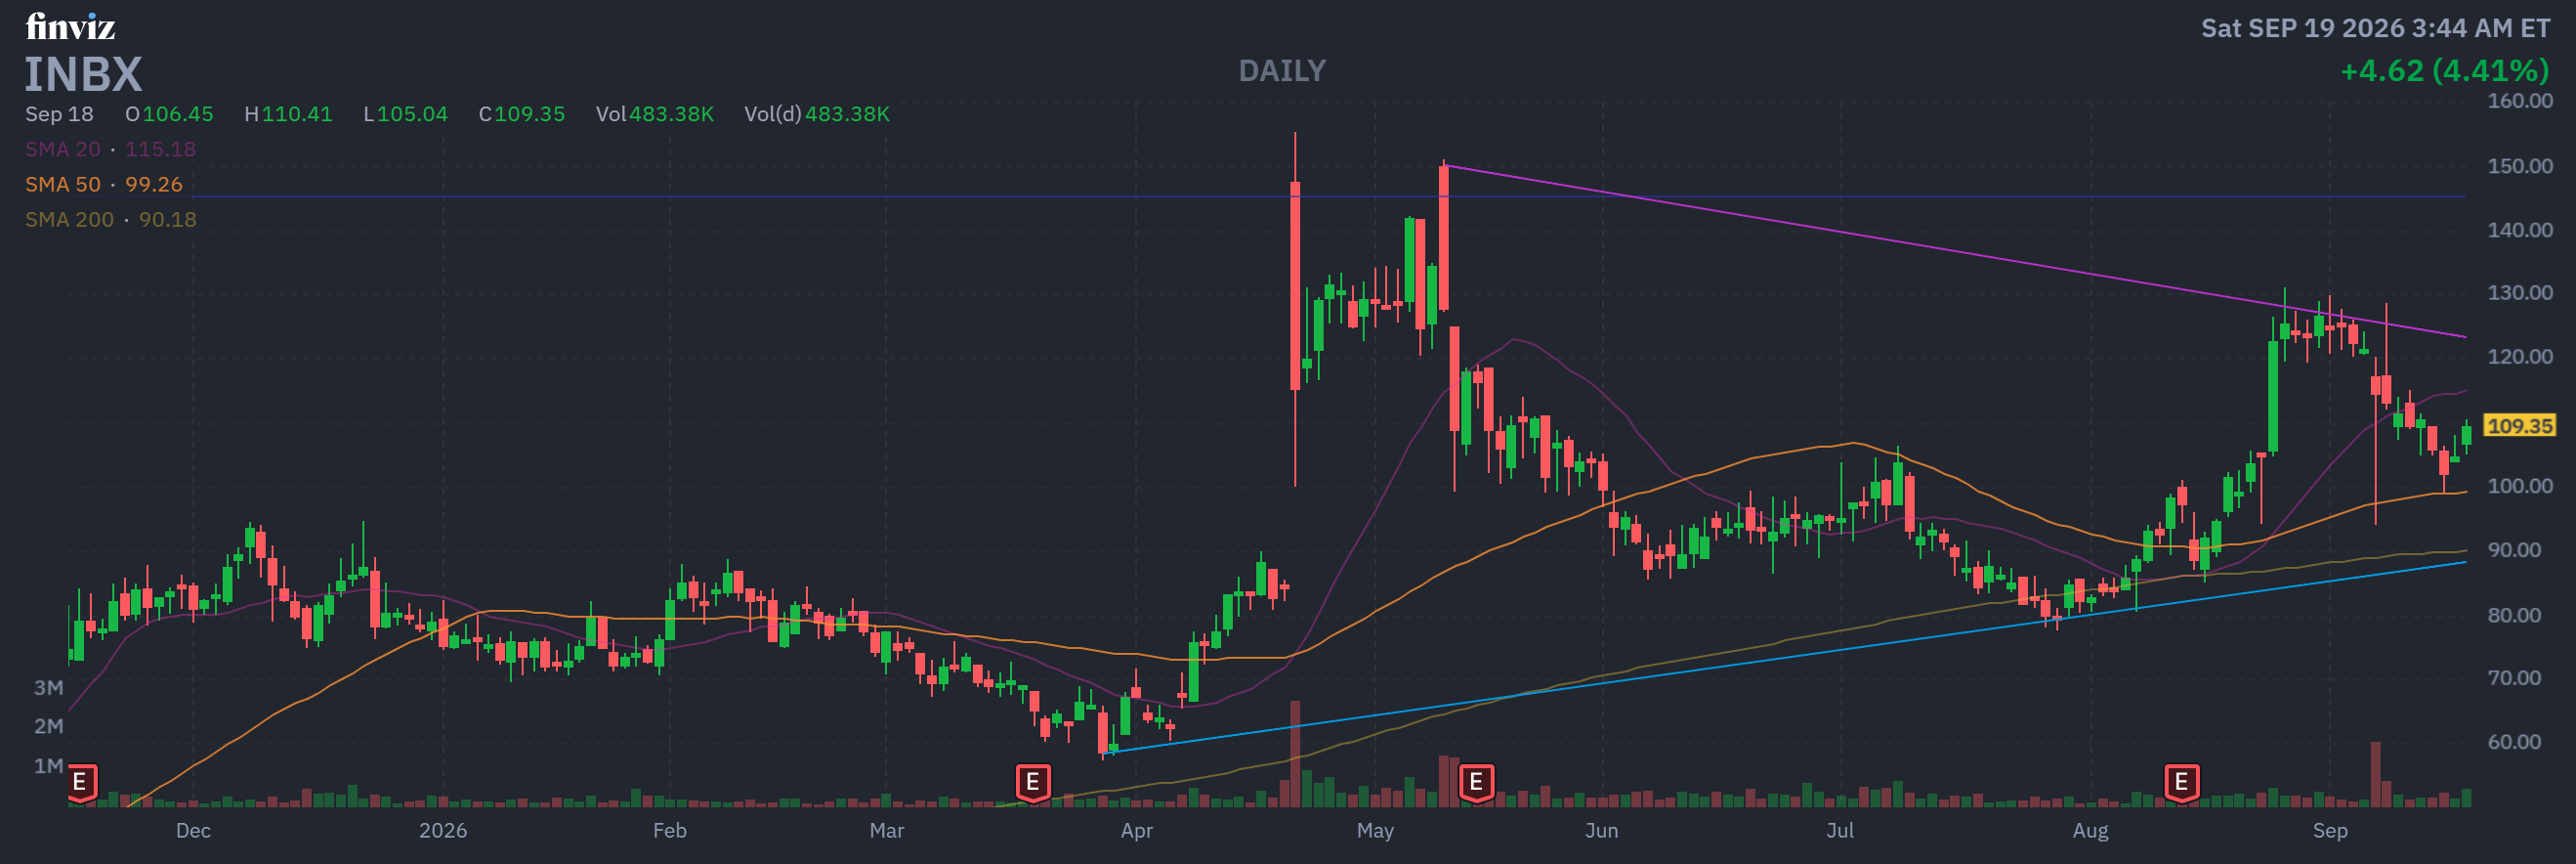
Name: Jon Faiz Kayyem
Position: Director
Transaction Date: 09-16-2026 Shares Bought: 5,000 shares an average price paid of $100.00 for Cost: $500,000
Company: Inhibrx Biosciences Inc. (INBX)
Inhibrx Biosciences, Inc. is a clinical-stage biopharmaceutical firm that develops biologic therapies for patients with life-threatening illnesses. INBRX-109, a tetravalent therapeutic candidate targeting death-receptor 5 to treat unresectable or metastatic conventional chondrosarcoma, and INBRX-106, a hexavalent sdAb-based therapeutic candidate targeting OX4 for the treatment of metastatic solid tumor, non-small cell lung cancer, melanoma, head non-small cell lung cancer cell carcinoma, gastric or gastroesophageal junction adenocarcinoma, renal cell carcinoma, Inhibrx Biosciences, Inc. was established in 2024 and is headquartered in La Jolla, California.
Jon Faiz Kayyem, Ph.D., has been a Director of Inhibrx Biosciences Inc. since May 2024, when he joined the board following the company’s split from its former parent. He has previously sat on the former parent’s board since April 2018. Kayyem founded GenMark Diagnostics and has held various high leadership positions, including President and Chief Executive Officer. He has considerable biotechnology and life sciences experience from leadership, investment, and board positions. He earned a B.S. and M.S. in Molecular Biophysics and Biochemistry from Yale University, as well as a Ph.D. in Molecular Biology from Caltech.
Insomniac Hedge Fund Guy Opinion: INBX is a high-risk, high-conviction binary bet dressed up as a stock. There’s no revenue, no moat in the traditional sense, and cash burn that would scare off anyone looking for a boring compounder. But stack up the pieces: a well-funded balance sheet, a BLA already accepted with the FDA, strong Phase 2 data on the second asset, a Strong Buy analyst consensus with real upside room, and management buying nearly $3.7 million of stock with their own cash while insiders sold nothing. Add 27%+ short interest and 10+ days to cover, and you’ve got dry tinder sitting next to a lit match in the form of the April 2027 PDUFA date. I’d call this a speculative buy for risk-tolerant investors who understand binary biotech outcomes, not a core holding, size it like the lottery ticket it structurally is, because a single FDA letter can cut this stock in half or send it through the roof.
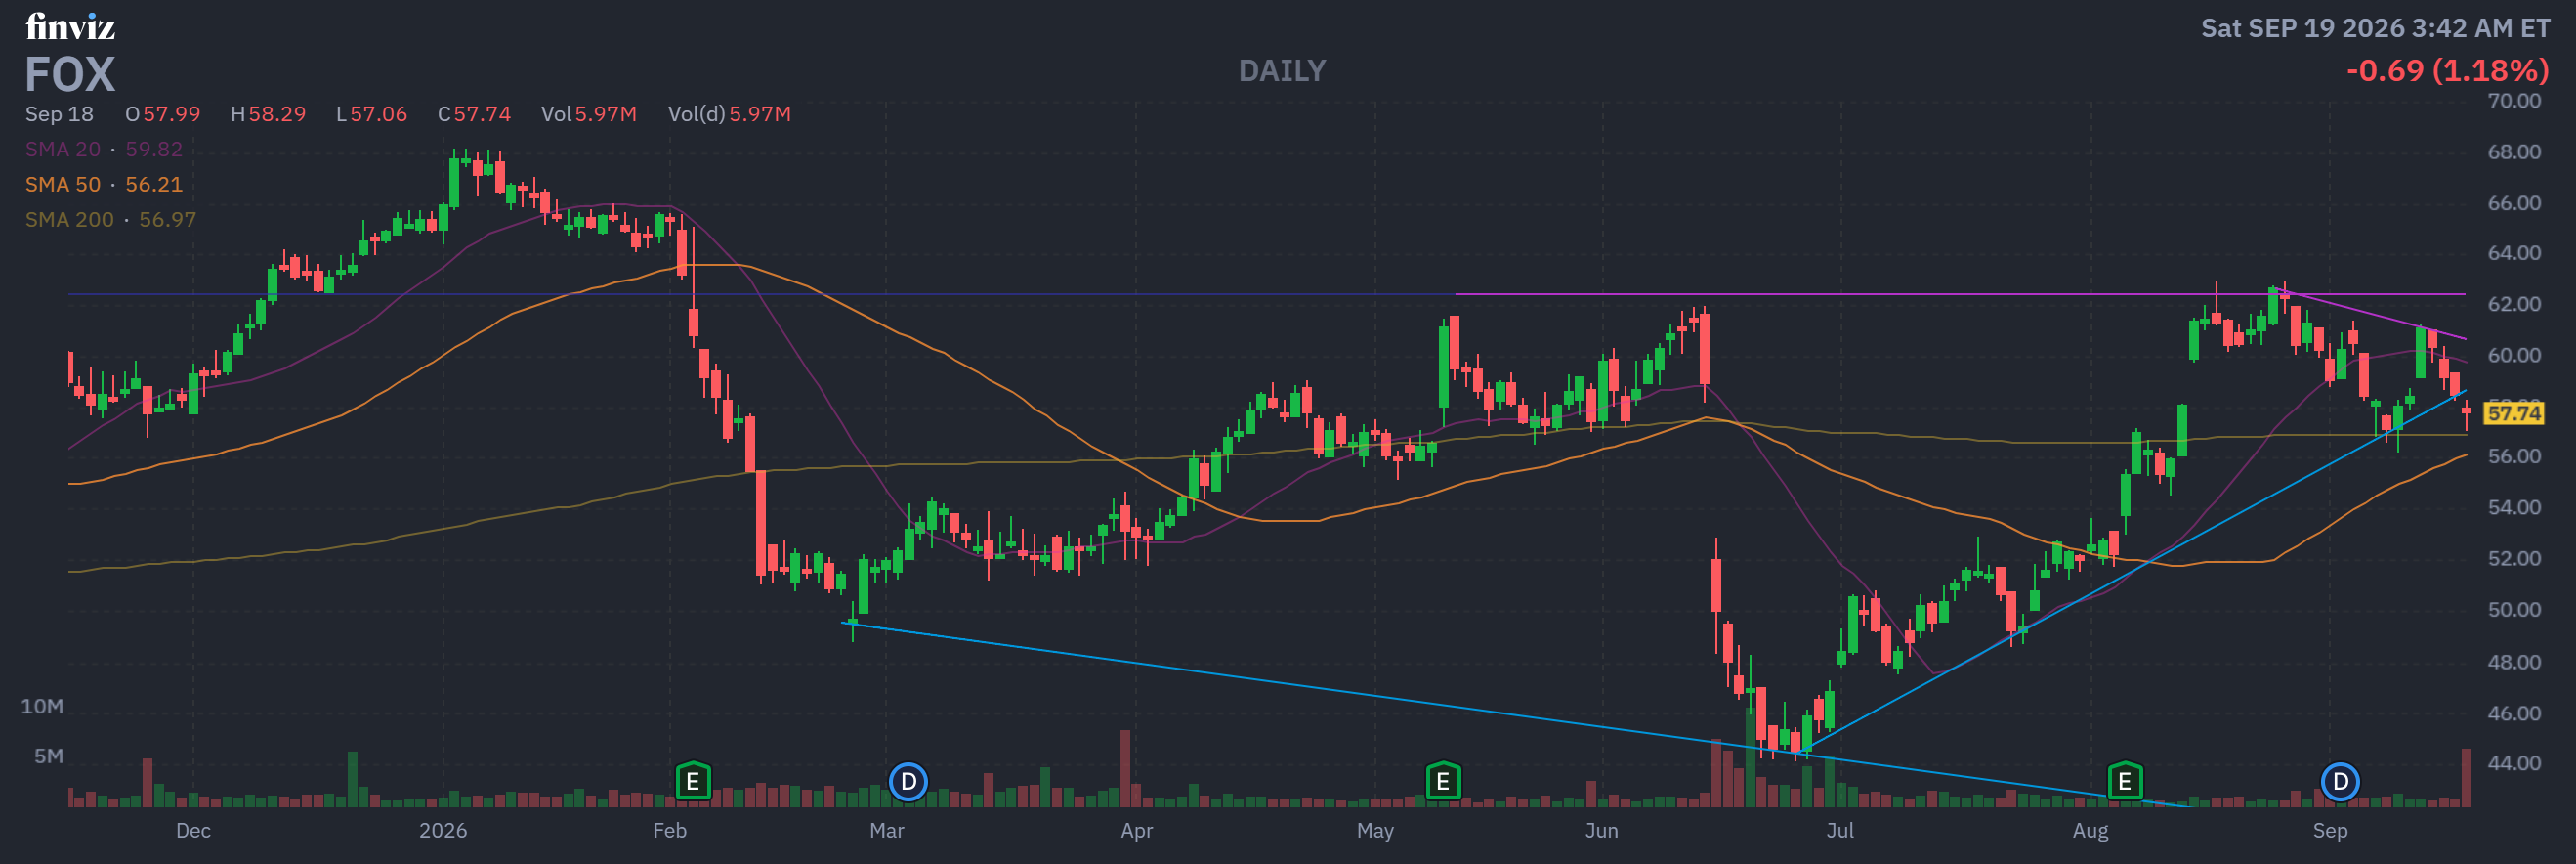
Name: Lachlan K. Murdoch
Position: Executive Chair, CEO
Transaction Date: 09-15-2026 Shares Bought: 149,934 shares an average price paid of $68.53 for Cost: $10,274,977
Company: Fox Corp. (FOX)
Fox Corporation is a news, sports, and entertainment company in the United States. It operates in two segments: Cable Network Programming and Television. The Cable Network Programming division creates and licenses sports and news content for distribution via traditional cable television systems, direct broadcast satellite operators, telecommunications firms, virtual multi-channel video programming distributors, and other digital platforms. The Television division creates, acquires, markets, and distributes content via the FOX broadcast network, the advertising-supported video-on-demand service Tubi, and full-power broadcast television stations, including duopolies and other digital platforms. Fox Corporation was founded in 2018 and is headquartered in New York, NY.
Lachlan K. Murdoch has been with Fox Corp. since 1994, when he began working in senior management positions for the company’s predecessor, News Corporation. He became Fox’s CEO in October 2018 and joined the Board of Directors in January 2019, when he was designated Executive Chair. He formerly served as Executive Chairman of 21st Century Fox and has held various senior positions in the television, publishing, and media industries. Murdoch has vast experience in global media and business strategy. He has a Bachelor of Arts degree from Princeton University.
Insomniac Hedge Fund Guy Opinion: Fox is a cheap, cash-generative media franchise trading roughly in line with fair value on a standalone basis, with the entire near-term thesis hinging on whether regulators let the Roku deal through. The Perfect10 composite score comes in at +2.8 (Constructive), insider buying is real, cash flow quality is real, and the valuation discount to peers is real. I’d call this a cautious buy for anyone comfortable holding through binary antitrust-outcome risk, but not a stock to chase into the mid-$60s while the DOJ still has its pen out. Buy the dip on Roku uncertainty, don’t buy the rumor of a clean approval.
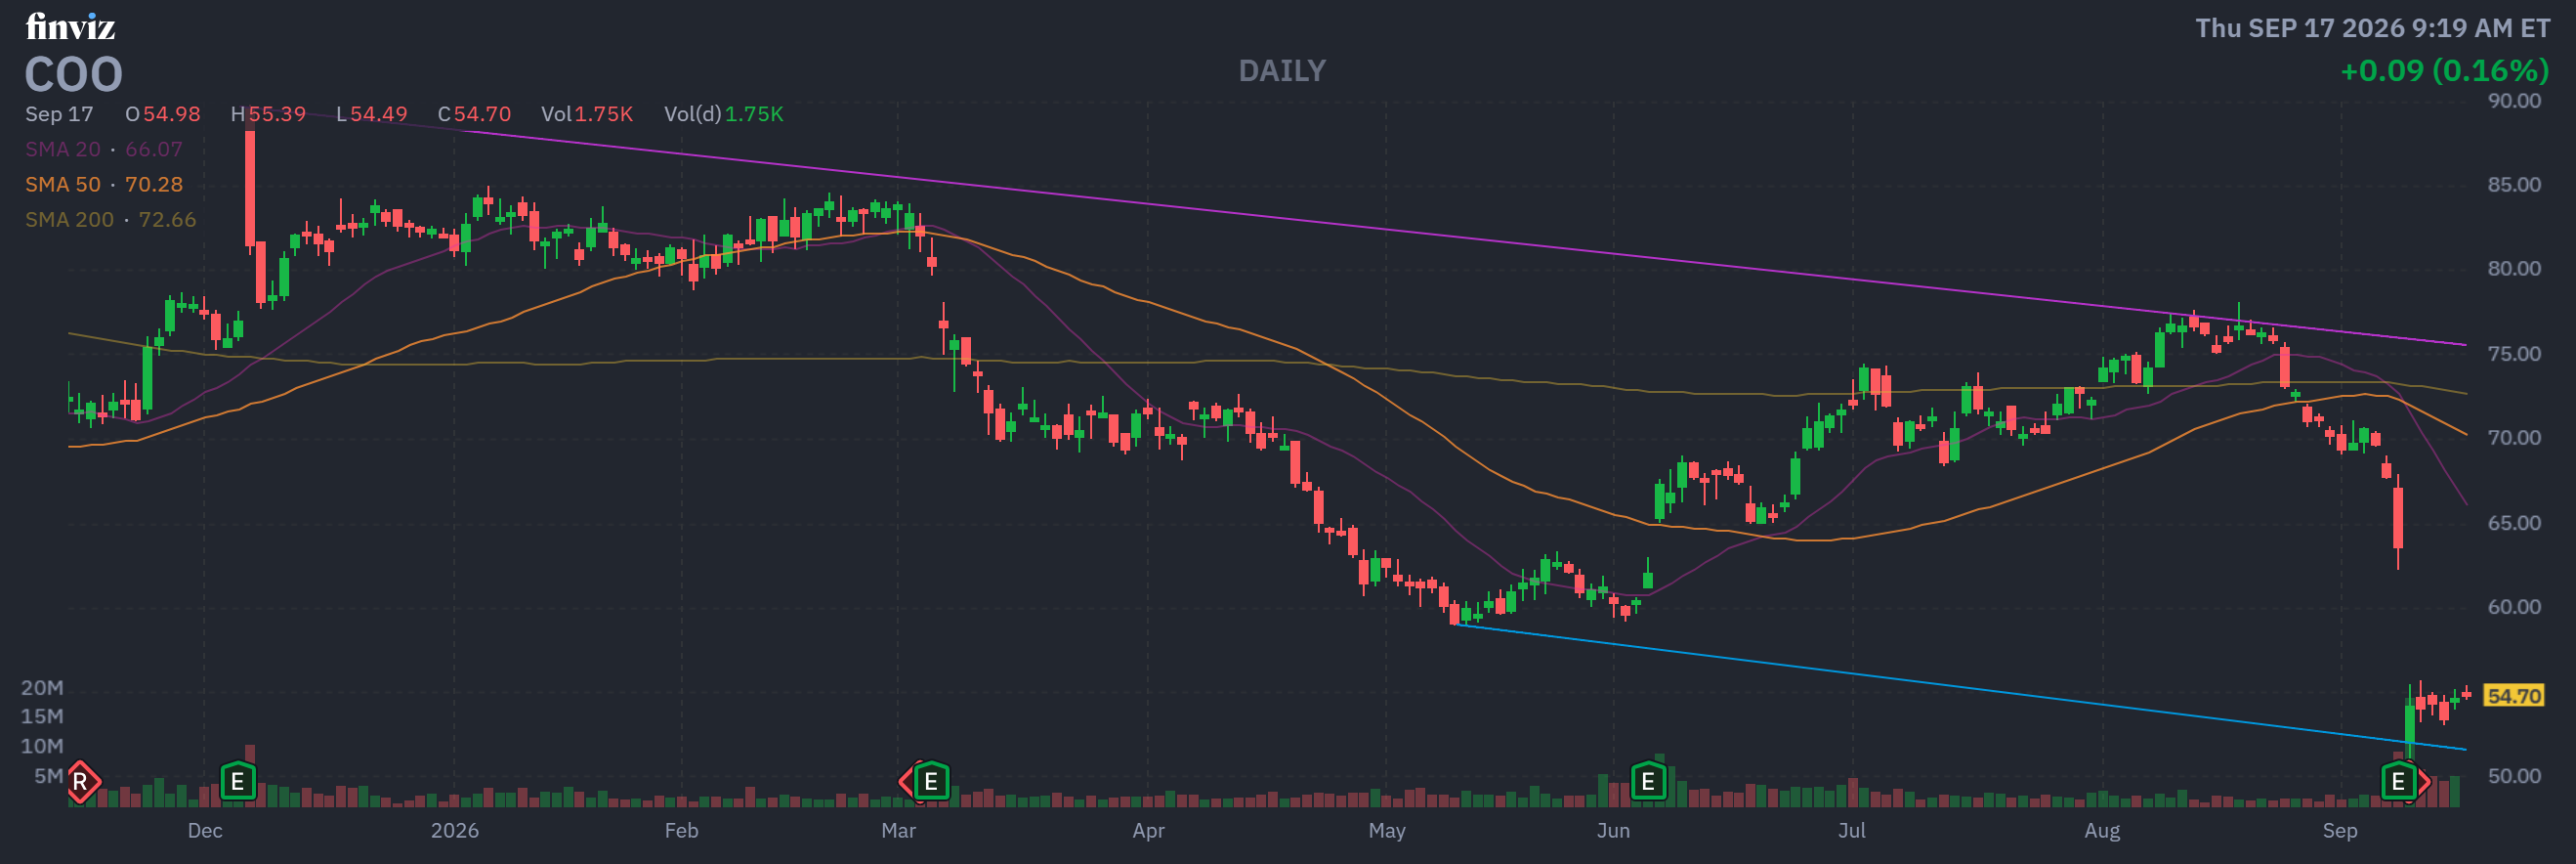
Name: Lawrence Erik Kurzius
Position: Director
Transaction Date: 09-16-2026 Shares Bought: 10,000 shares an average price paid of $54.93 for Cost: $549,320
Transaction Date: 09-14-2026 Shares Bought: 10,000 shares an average price paid of $53.91 for Cost: $539,150
Name: Paul A. Keel
Position: Director
Transaction Date: 09-11-2026 Shares Bought: 4,701 shares an average price paid of $53.18 for Cost: $250,000
Name: Walter M. Rosebrough Jr
Position: Director
Transaction Date: 09-11-2026 Shares Bought: 10,000 shares an average price paid of $54.16 for Cost: $541,640
Company: Cooper Companies Inc. (COO)
The Cooper Companies, Inc. and its subsidiaries design, produce, and market contact lens wearers. CooperVision and CooperSurgical are the company’s two operating segments. CooperVision provides spherical, toric, and multifocal contact lenses to treat visual issues such as astigmatism, presbyopia, and myopia. CooperSurgical specializes in family and women’s health care, offering reproductive products and services, medical devices, and contraception, as well as cryostorage options such as cord blood and cord tissue storage. This division provides a hormone-free intrauterine device called Paragard, as well as fertility consumables and equipment, donor gamete services, and genomic services such as genetic testing. The Cooper Companies, Inc. was founded in 1958 and is based in San Ramon, California.
Lawrence Erik Kurzius has served as a Director of The Cooper Companies, Inc. since December 2023, when he joined the company’s Board of Directors as an independent director. He brings extensive global leadership experience, having served as Chief Executive Officer of McCormick & Company and previously held several senior executive roles there. He also has experience serving on the boards of other publicly traded companies, including Elanco Animal Health and Lamb Weston. Kurzius holds an A.B. in Economics from Princeton University, where he graduated magna cum laude.
Paul A. Keel has served on the Board of Directors of The Cooper Companies, Inc. (COO) since July 1, 2026, when he was appointed as an independent director. He had not previously worked for Cooper Companies. Keel has been the President and CEO of Envista Holdings since 2024, having previously served as CEO of Smiths Group from 2021 to 2024. Previously, he spent 16 years with 3M in different leadership positions, including President of 3M Medical. He has a B.A. in economics from Carleton College and an MBA from Harvard Business School.
Walter M. Rosebrough Jr. has been a Director of The Cooper Companies, Inc. since January 2026, when he joined the company’s Board of Directors as an independent director. He has over four decades of healthcare business experience, including considerable leadership in medical devices. He formerly served as CEO of STERIS and held many senior executive positions at Hill-Rom, including President and CEO. He is currently the CEO Emeritus and Senior Advisor of STERIS, as well as Varex Imaging’s Independent Chair. Rosebrough earned a Bachelor of Industrial Engineering from Kettering University and an MBA from Stanford University.
Insomniac Hedge Fund Guy Opinion: COO is a quality business having an ugly quarter, not a broken one. The five-year growth deceleration is real and the market was right to punish weak guidance, but a 15% single-day drop for a temporary channel-inventory issue, paired with a $3 billion buyback and three directors buying six figures each right after the crash, tells me this looks more like an overreaction than a structural collapse. My DCF and the Street’s target both land meaningfully above the current price. I’d call this a cautious buy for patient investors willing to look past one or two soft quarters, not a name to chase for a quick trade. Watch the December Q4 print closely: if destocking is truly resolved, this stock has room to run back toward $65 plus; if it isn’t, the “temporary” story starts looking like wishful thinking.
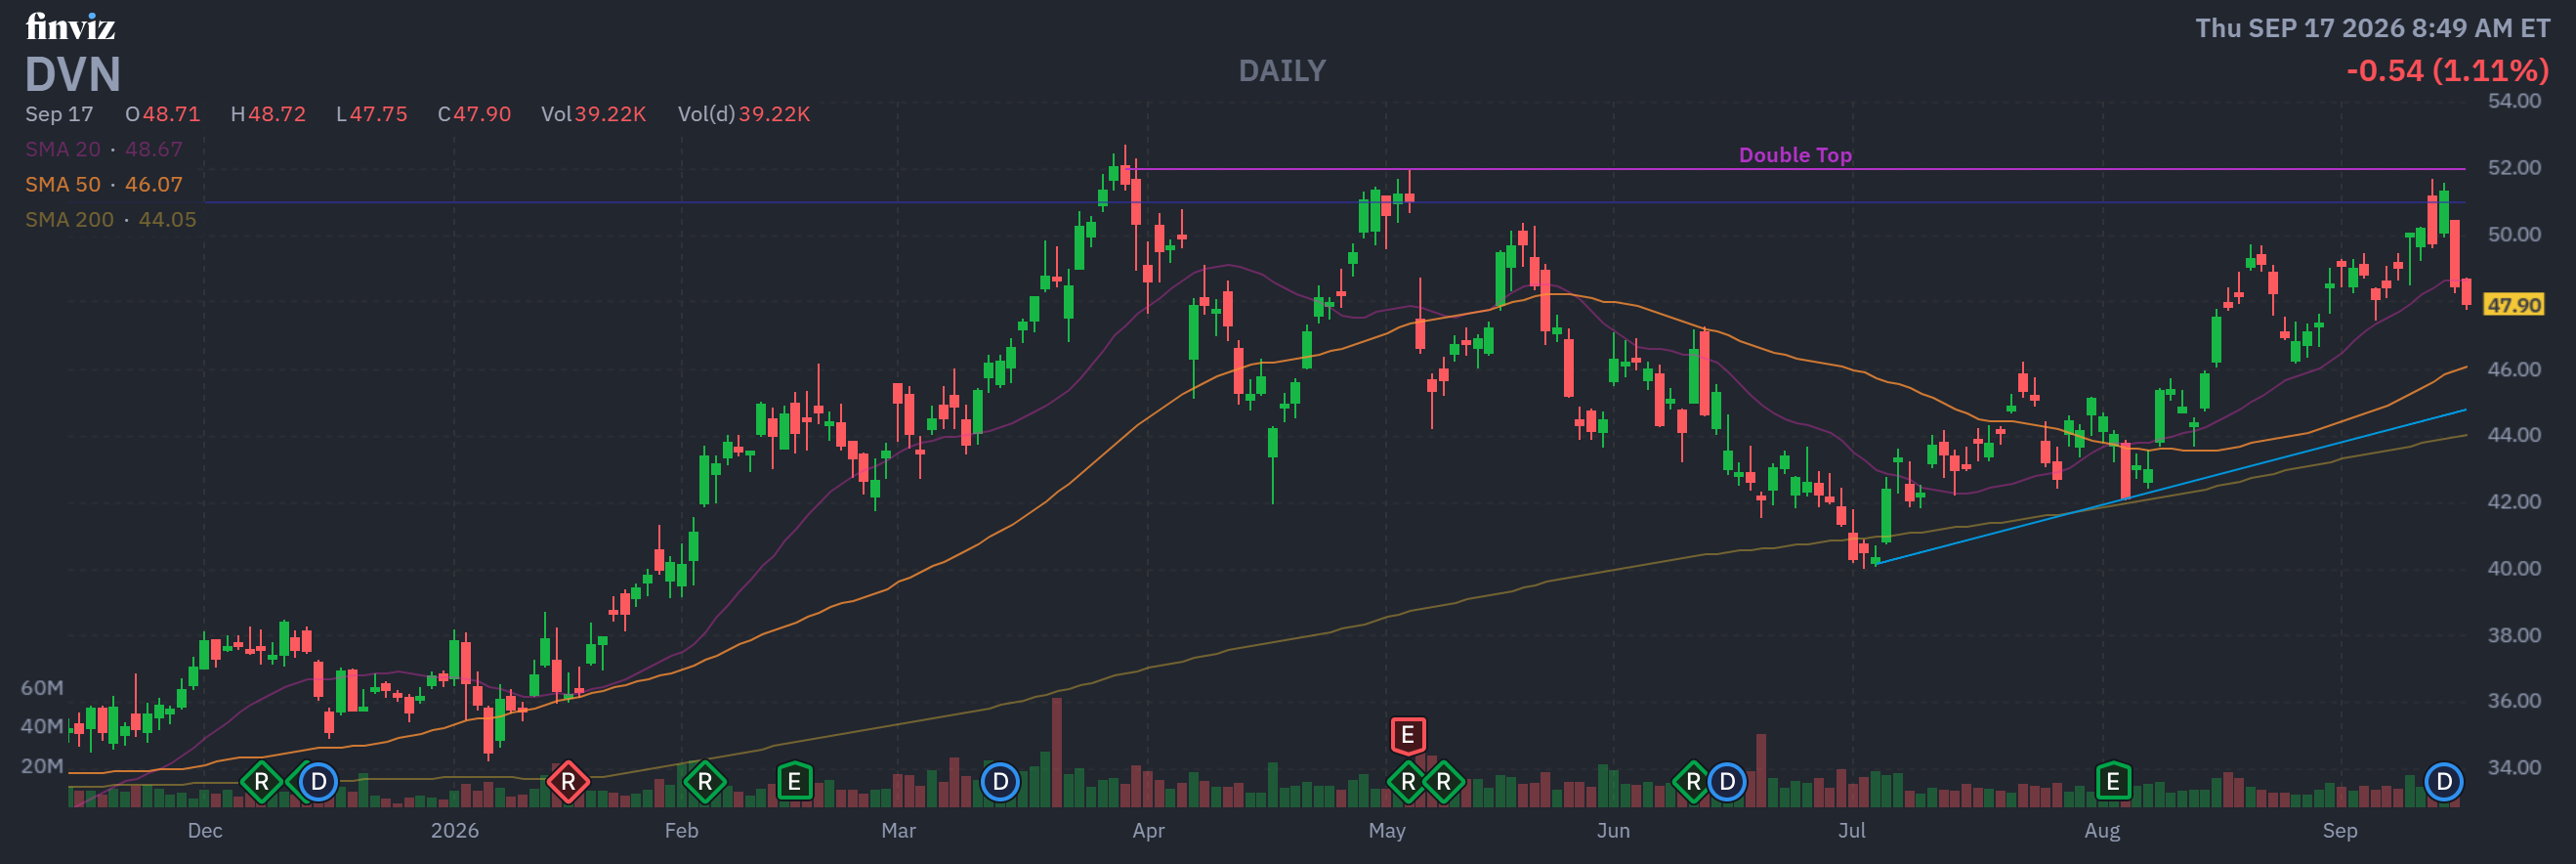
Name: Clay M. Gaspar
Position: President and CEO
Transaction Date: 09-14-2026 Shares Bought: 3,913 shares an average price paid of $51.08 for Cost: $199,876
Company: Devon Energy Corp. (DVN)
Devon Energy Corporation is an independent energy business in the United States that explores, develops, and produces oil, natural gas, and natural gas liquids. The business operates in numerous key production regions, including the Delaware Basin in southeast New Mexico and west Texas, the Eagle Ford in North America, the Anadarko Basin in western Oklahoma, the Williston Basin in North Dakota, and the Powder River Basin in Wyoming. Its operations are focused on developing and extracting hydrocarbons from these critical U.S. resource areas. Devon Energy Corporation was created in 1971 and is based in Houston, Texas.
Clay M. Gaspar has been with Devon Energy Corp. since January 2021, when he was appointed Executive Vise President and Chief Operating Officer following the merger with WPX Energy. He was named President and CEO and joined Devon’s Board of Directors on March 1, 2025. Gaspar formerly worked as WPX Energy’s President and Chief Operating Officer, as well as technical and executive positions at Newfield Exploration, Anadarko Petroleum, and Mewbourne Oil. He received a bachelor’s degree in petroleum engineering from Texas A&M University and a master’s degree in petroleum and geosciences engineering from the University of Texas.
Insomniac Hedge Fund Guy Opinion: Devon is a well-run, disciplined operator sitting on good rock, but it’s still a commodity stock wearing a growth-stock valuation multiple (PEG north of 2.9 is a real yellow flag). The DCF says fair value is roughly where it’s trading now, not a bargain. The Strong Buy analyst consensus and 25% upside to target are tempting, but that view leans on oil prices and merger synergies cooperating, neither of which is guaranteed. I’d call this a hold, lean toward accumulate on dips below $46, not a chase at current levels after a 30%+ year-to-date run. This is a stock for someone who wants energy sector exposure through a quality operator, not a stock offering a clear mispricing today.
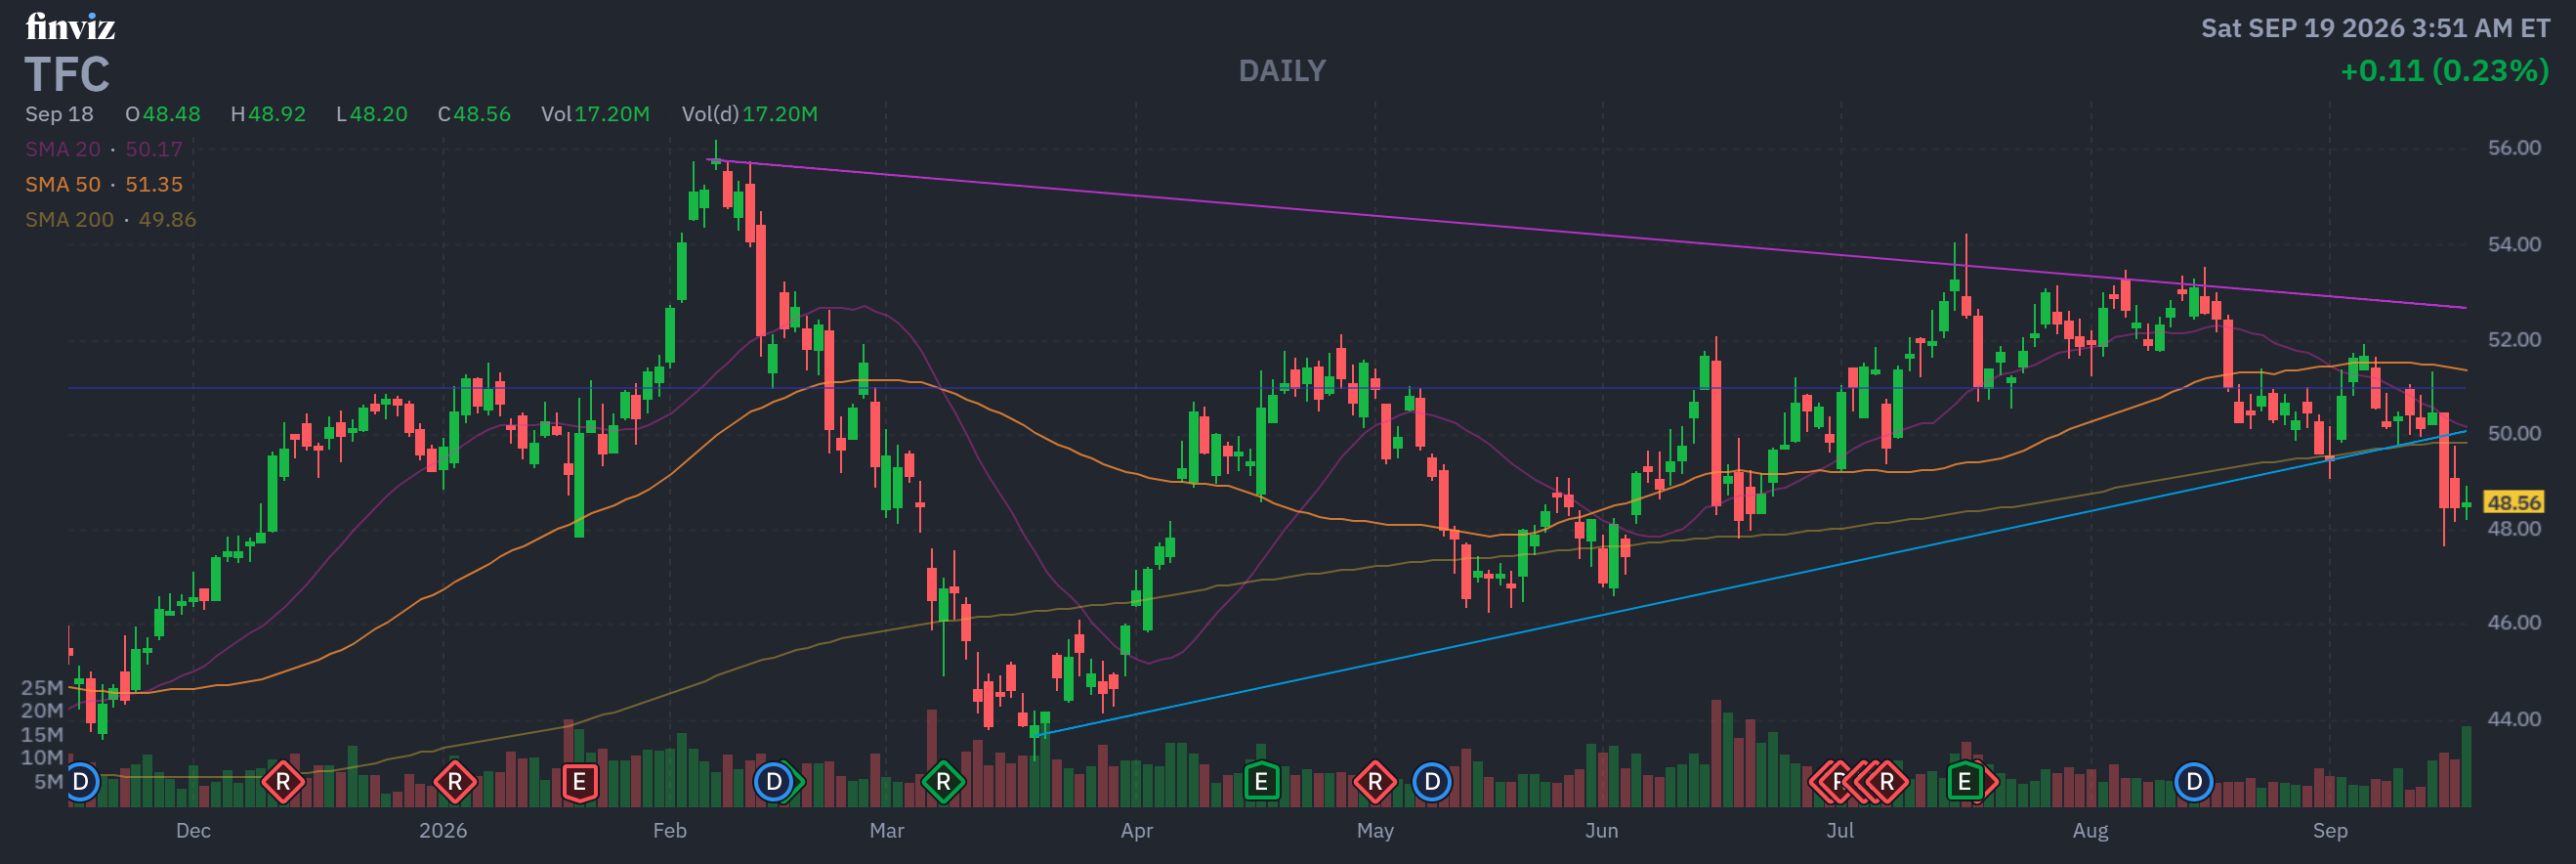
Name: Michael P. Lyons
Position: President & CEO
Transaction Date: 09-17-2026 Shares Bought: 21,000 shares an average price paid of $48.36 for Cost: $1,015,577
Company: Truist Financial Corp (TFC)
Truist Financial Corporation is a financial services company that provides banking, lending, investment, trust, and wealth management services across the Southeastern and Mid-Atlantic United States. The company operates through Consumer and small business banking and wholesale banking segments. Its services include deposit accounts, credit cards, mortgage and home equity lending, small business banking, commercial lending, asset management, investment banking, insurance, treasury services, wealth management, and private banking. The company also provides digital banking, payment solutions, leasing, merchant services, real estate lending, and capital markets services. The company was formerly known as BB&T Corporation before changing its name to Truist Financial Corporation in December 2019. Truist Financial Corporation was founded in 1872 and is headquartered in Charlotte, North Carolina.
Michael P. Lyons joined Truist Financial Corp. as President and Chief Executive Officer in September 2026 and became a member of the Boards of Directors of Truist Financial Corporation and Truist Bank at the same time. Before joining Truist, he served as Chief Executive Officer of Fiserv and previously as President of The PNC Financial Services Group. Earlier in his career, he held senior leadership roles at Bank of America, including global head of corporate development and strategic planning. Lyons brings extensive experience across banking, payments, and financial technology. He earned a bachelor’s degree from the University of Pennsylvania.
Insomniac Hedge Fund Guy Opinion: Truist is a cheap, boring bank with a CEO putting his own money where his mouth is and cash flow quality that’s actually improving. The Perfect10 composite lands at +1.9 on the -10 to +10 scale, a mixed-to-neutral read, and that’s fair: this isn’t a screaming buy, but it’s not a value trap either. Trading at book value with a 68 Attaboy sentiment score and modest analyst upside to $54.93, I’d call this a cautious buy for value and income investors, not a trade, a name to accumulate on weakness and collect the dividend while you wait for NIM pressure to ease. It won’t excite you, but at these multiples, it doesn’t have to.
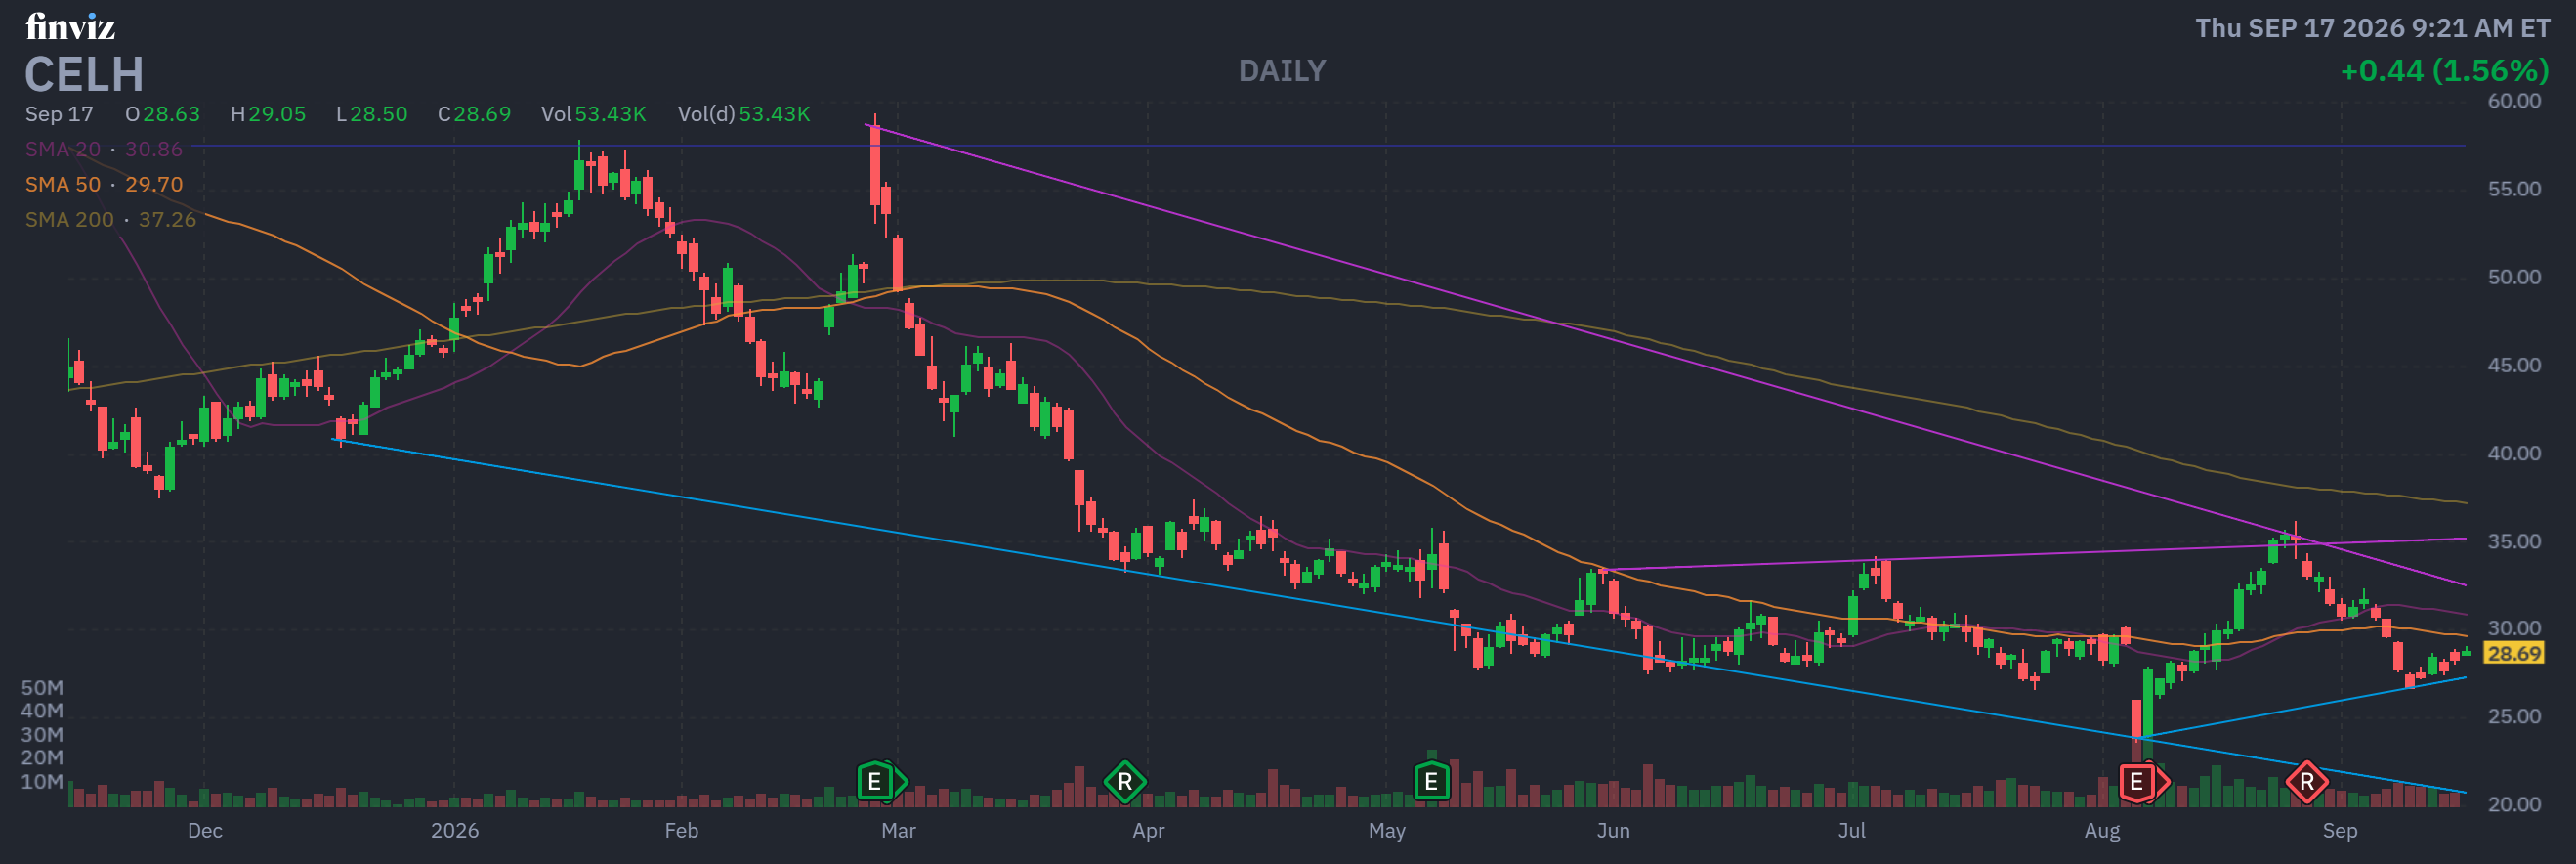
Name: Hal Kravitz
Position: Director
Transaction Date: 09-15-2026 Shares Bought: 12,000 shares an average price paid of $28.00 for Cost: $336,000
Company: Celsius Holdings Inc. (CELH)
Celsius Holdings, Inc. develops, processes, produces, markets, sells, and distributes functional energy drinks in the United States, North America, Europe, Asia Pacific, and around the world. The company provides CELSIUS ESSENTIALS, a functional energy drink formulated with aminos, and CELSIUS Hydration, a line of zero-sugar hydration powders featuring electrolytes in various fruit-forward flavors, as well as ready-to-drink energy beverages, on-the-go powder and hydration sticks, and nutrition and wellness products under the CELSIUS, Alani Nu, and Rockstar brand names. The company was previously known as Vector Ventures, Inc. before changing its name to Celsius Holdings, Inc. in January 2007. Celsius Holdings, Inc. was created in 2004 and is based in Boca Raton, Florida.
Hal Kravitz has been a Director of Celsius Holdings Inc. since December 2023, when he was named to the company’s Board of Directors. Kravitz is the founder and Managing Partner of Kravitz Capital Management, with decades of experience in investment management, consumer brands, and business strategy. Before joining the Celsius board, he was an early investor in the firm and has contributed significantly to its long-term success and expansion in the functional beverage market. Kravitz holds a bachelor’s degree in finance and business administration from the University of Florida.
Insomniac Hedge Fund Guy Opinion: CELH is a speculative buy for patient investors, not a table-pounding no-brainer. The core brand is stumbling through an ugly integration year, profitability is compressing, and nearly half of revenue still funnels through a single distribution partner. But the cash flow is real, insiders are buying with their own money while the stock sits near 52-week lows, short interest has already started unwinding, and my rough DCF suggests the stock isn’t dramatically overpriced at $28 even before you factor in a 2027 recovery story. I’d call this a name to nibble on the dips and watch Q3 earnings closely, not one to back up the truck on until the core brand actually stops shrinking.
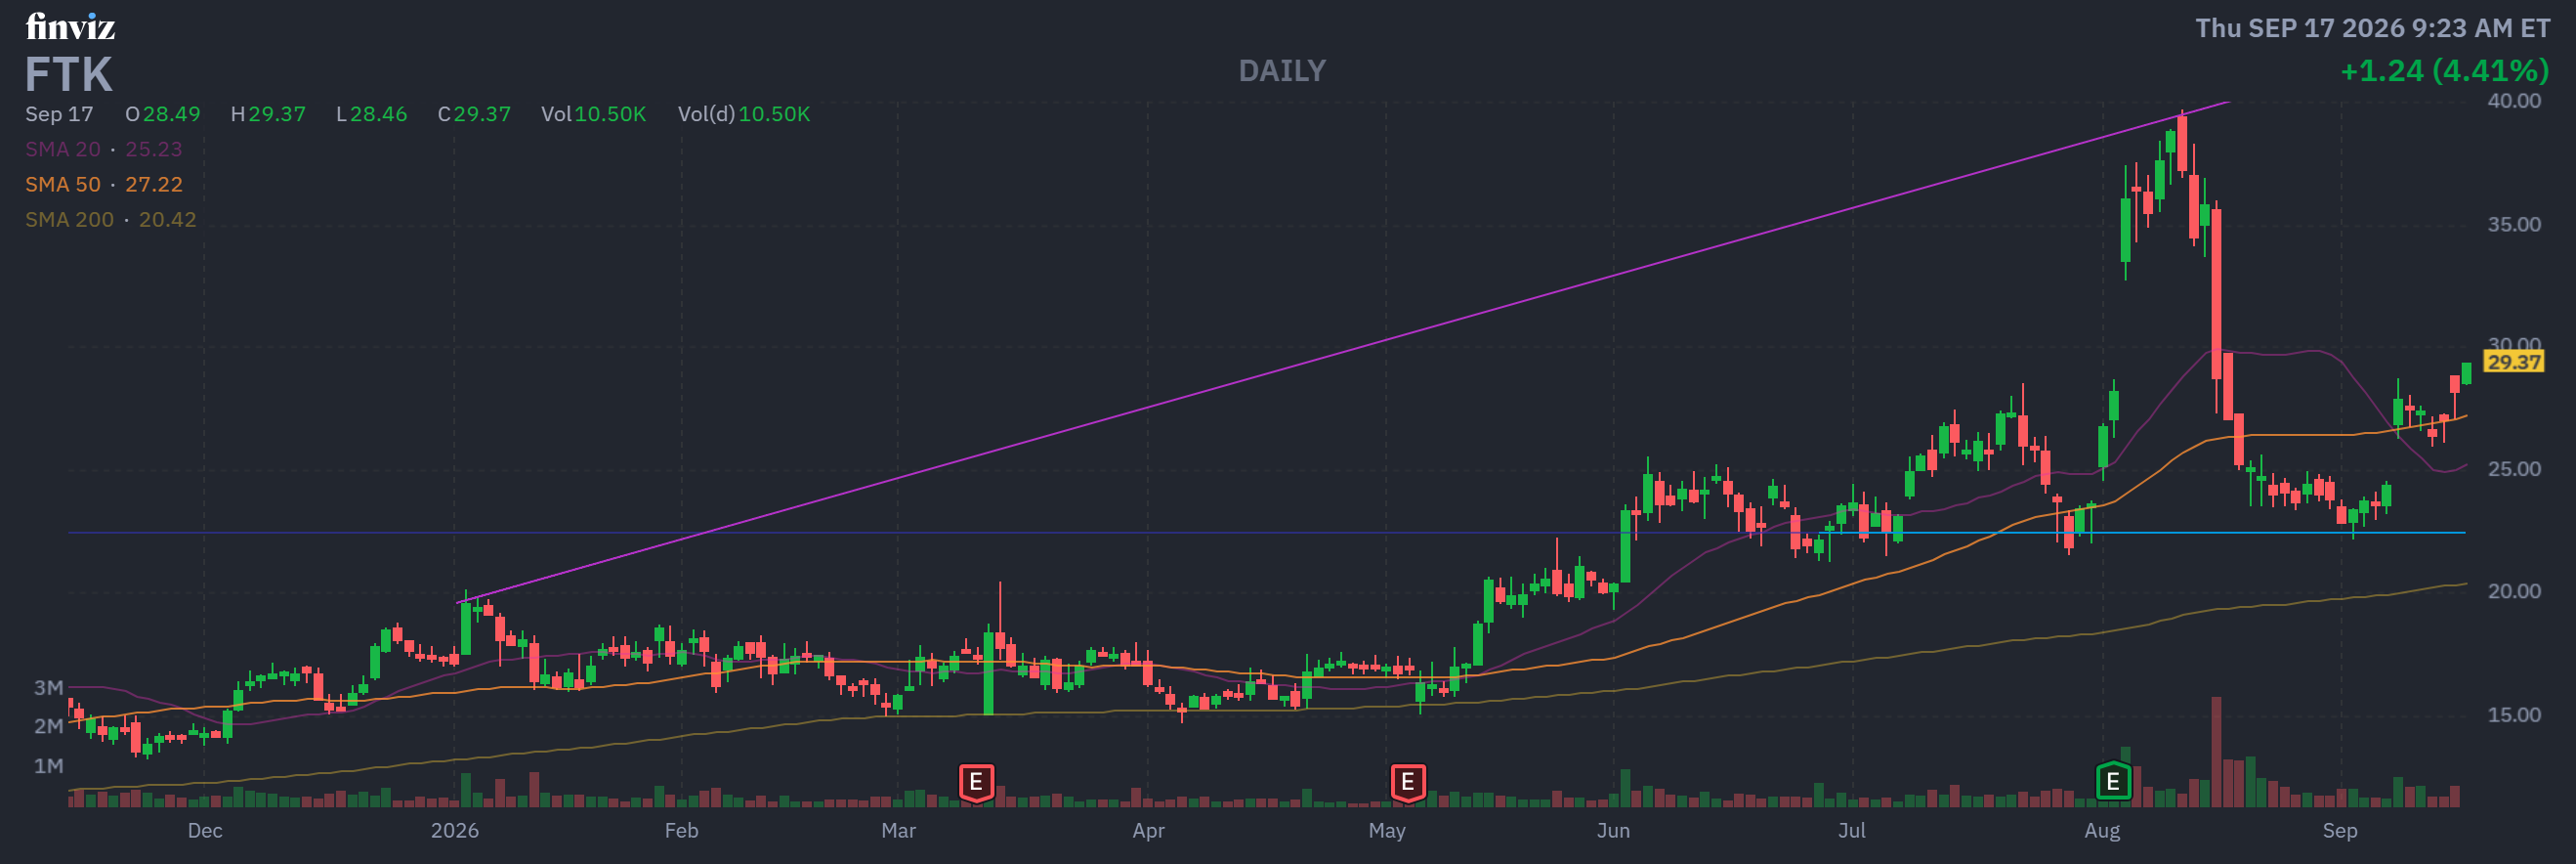
Name: Matthew Wilks
Position: Director
Transaction Date: 09-11-2026 Shares Bought: 1,319,493 shares an average price paid of $26.01 for Cost: $34,320,013
Company: Flotek Industries Inc. (FTK)
Flotek Industries, Inc. is a chemical and data analytics company that delivers energy industry solutions in the United States, the UAE, and across the world. The company operates in two segments: Chemistry Technologies and Data Analytics, which provide unique and specialty chemistries, logistics, technological services, analytical measurement, digital solutions, and equipment rentals. Its solutions assist energy firms in optimizing operations, improving decision-making, lowering emissions, and minimizing environmental consequences. Flotek’s clients include oil and gas firms, oilfield service providers, national and state-owned energy companies, geothermal and solar energy companies, and other alternative energy businesses. Flotek Industries, Inc. was established in 1985 and is based in Houston, Texas.
Matthew D. Wilks has been a Director of Flotek Industries, Inc. since June 2022, when he joined the company’s Board of Directors. He has vast experience in the petroleum and oilfield services industries and presently serves as Executive Chairman of ProFrac Holding Corp., President of ProFrac Services, and Vise President of Investments for Wilks Brothers. He has held executive positions with Wilks Masonry, VERTEX Solutions, and FTS International, as well as serving on the board of Approach Resources.
Insomniac Hedge Fund Guy Opinion: Flotek is a legitimate turnaround story with real operating momentum, raised guidance twice in weeks, a 70% revenue jump last quarter, and a large insider buy backing the story with real money. But the stock isn’t cheap: a PEG ratio above 4, an EV/EBITDA near 26x, and my own DCF landing right around today’s price tell me the growth is already priced in, not undiscovered. Add in weak cash flow conversion, heavy customer concentration with a related party, and nearly 10% of the float sold short, and this is a stock where the bulls and the skeptics both have real ammunition. I’d call this a speculative hold, or a buy only for those comfortable underwriting continued 20%+ growth and treating the ProFrac relationship as a real, monitored risk rather than a footnote. This isn’t the “sleepy value stock” pile, it’s a high-conviction bet on execution.
Name: Paul Gu
Position: Chief Executive Officer
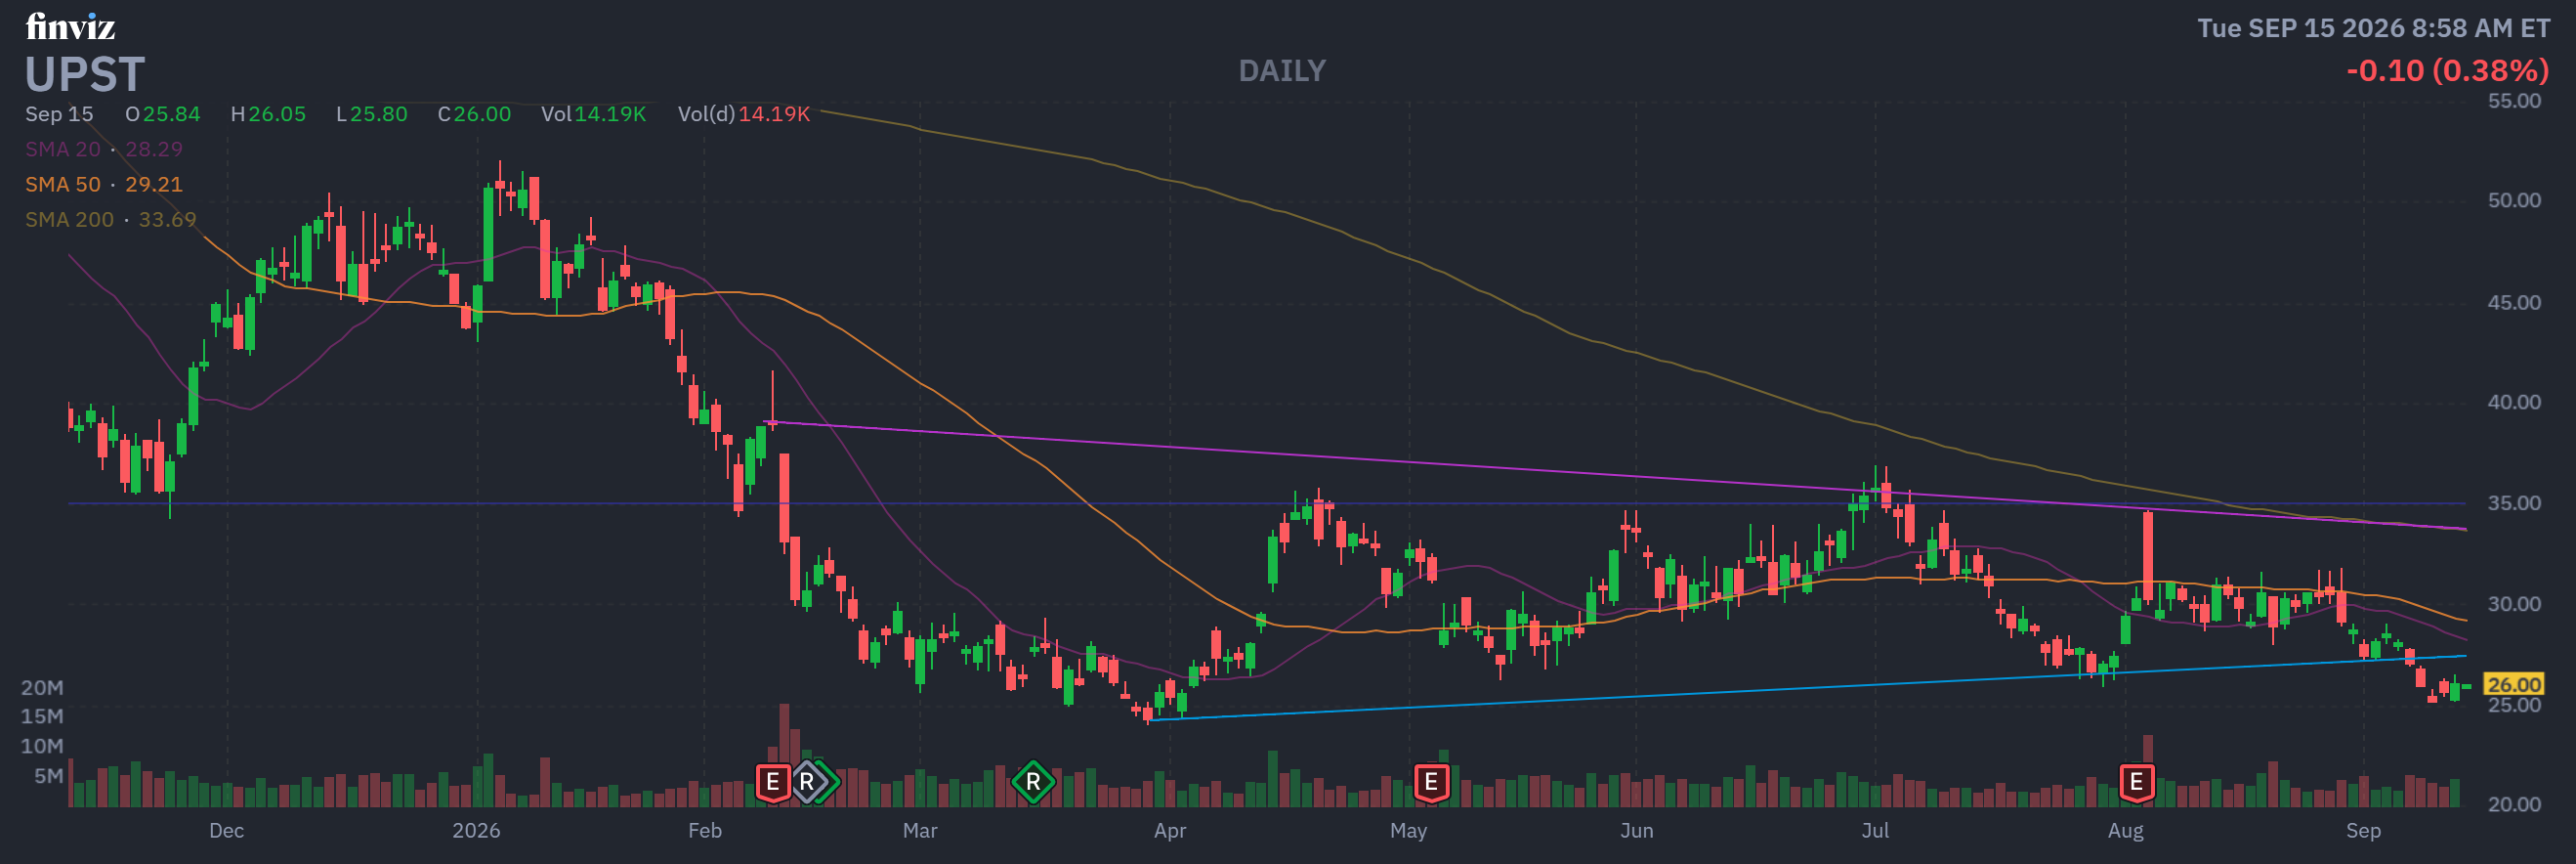
Transaction Date: 09-10-2026 Shares Bought: 50,000 shares an average price paid of $25.55 for Cost: $1,277,500
Company: Upstart Holdings Inc. (UPST)
Upstart Holdings, Inc. operates a cloud-based artificial intelligence lending platform in the United States through its subsidiaries. The company has three business segments: personal lending, auto lending, and other. Its AI-powered technology enables banks and credit unions to assess borrower risk and automate loan approvals. Upstart provides unsecured personal loans, small-dollar loans, auto refinance loans, auto retail loans, vehicle-secured personal loans, and home equity lines of credit. The company focuses on applying advanced data models and machine learning to improve credit availability and loan efficiency. Upstart Holdings, Inc., founded in 2012, is based in San Mateo, California.
Paul Gu is the co-founder and CEO of Upstart Holdings, Inc., having joined the firm in April 2012 as a co-founder alongside Dave Girouard and Anna Counselman. He joined Upstart’s Board of Directors in April 2015 and became CEO on May 1, 2026, following Dave Girouard. Prior to becoming CEO, Gu was Chief Technology Officer, overseeing the company’s product, engineering, and machine-learning divisions. He studied economics and computer science at Yale University before accepting the Thiel Fellowship.
Insomniac Hedge Fund Guy Opinion: UPST is a high-beta bet on the credit cycle bending in your favor. The growth numbers (35-64% recent revenue reacceleration) and a CEO buying stock with his own money on the open market are real bullish signals, and the DCF math (roughly $48-58/share) plus a $40 average analyst target both suggest meaningful upside from ~$25.60. But the negative operating cash flow despite positive net income, a stretched valuation multiple, and short interest north of 30% of float tell you the market is genuinely split on whether this recovery is durable or another head-fake before the next credit-cycle gut punch. I’d call this a speculative buy for investors who can stomach volatility and are betting on continued credit normalization, not a core holding for anyone who wants to sleep well through earnings season. Do your own diligence before sizing a position here.
Name: H. Sanford Riley
Position: Non-Executive Chairman
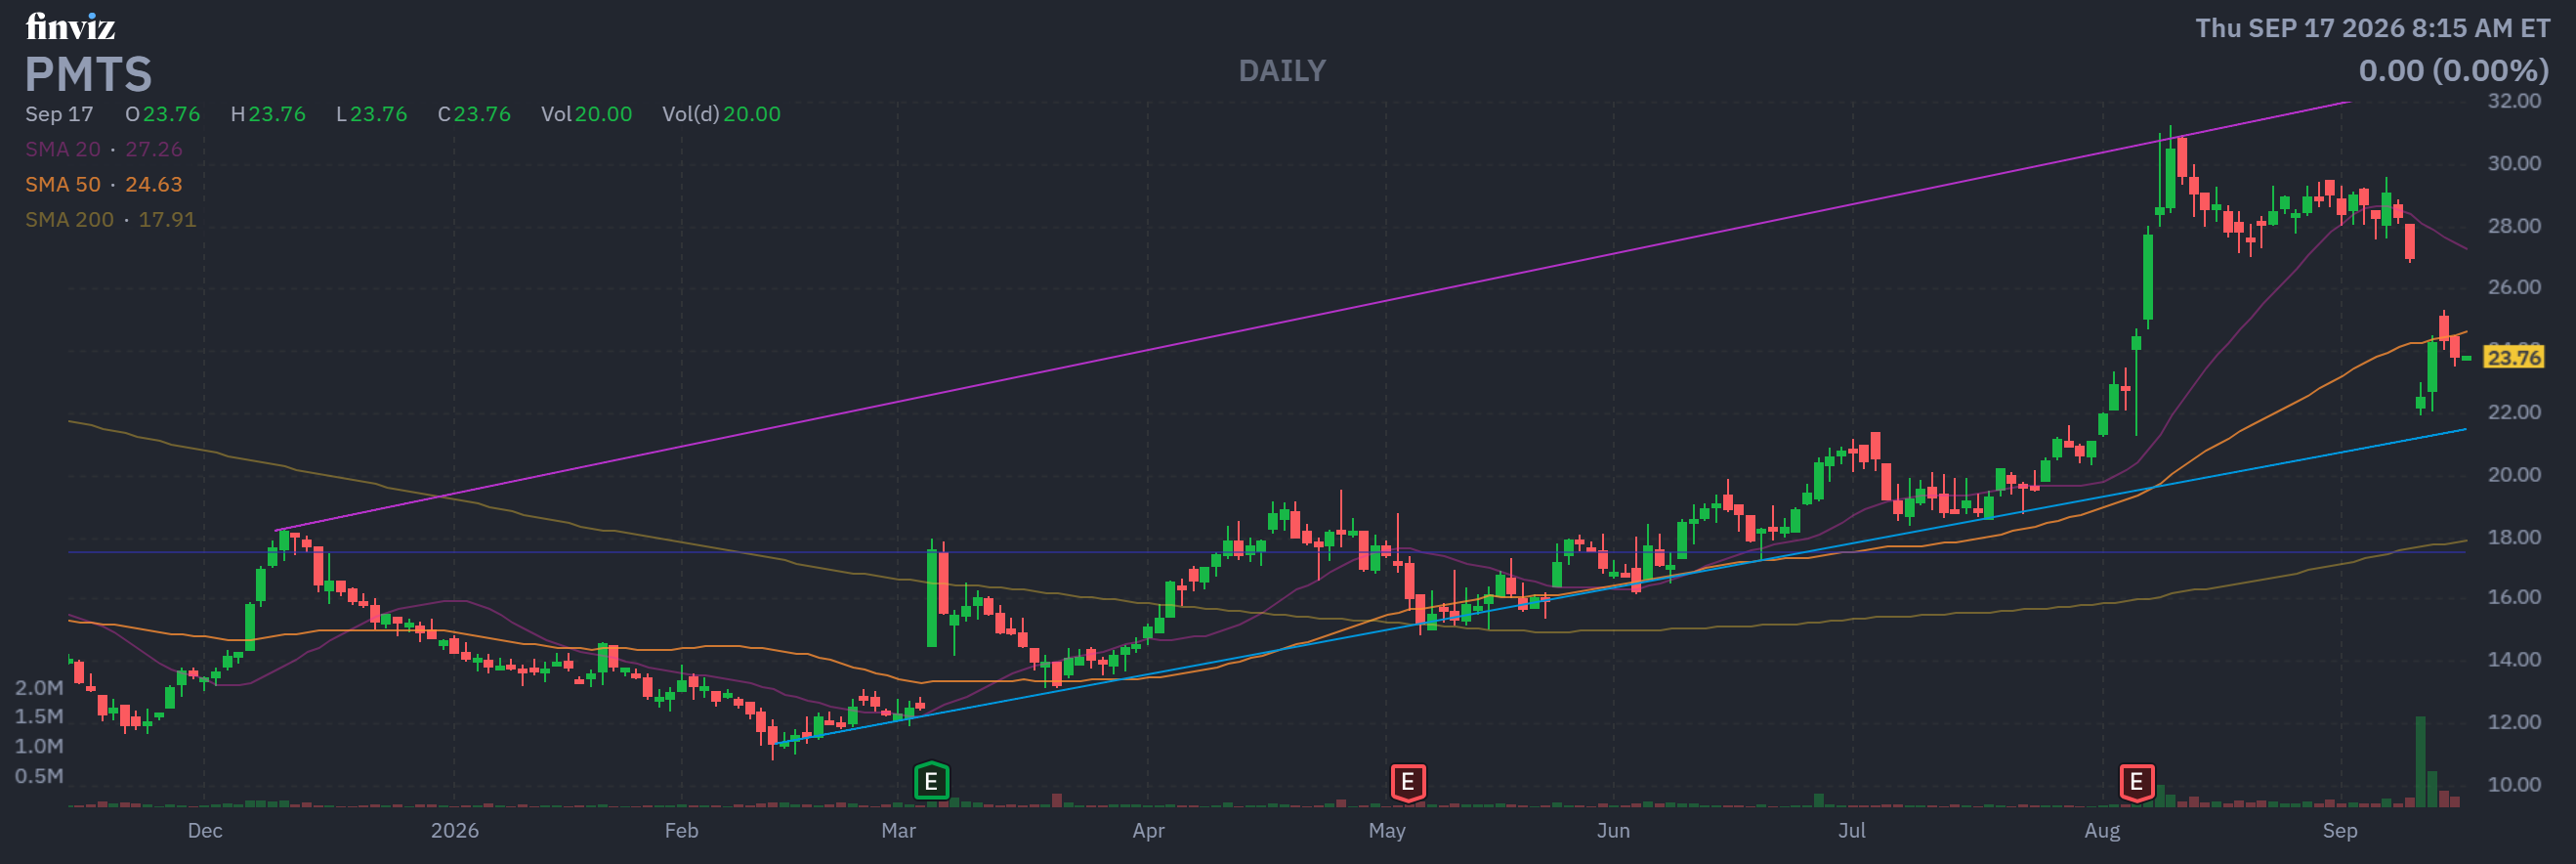
Transaction Date: 09-14-2026 Shares Bought: 13,953 shares an average price paid of $21.50 for Cost: $299,990
Name: Nicholas Peters
Position: Director
Transaction Date: 09-14-2026 Shares Bought: 11,628 shares an average price paid of $21.50 for Cost: $250,002
Name: Marc Sheinbaum
Position: Director
Transaction Date: 09-14-2026 Shares Bought: 4,651 shares an average price paid of $21.50 for Cost: $99,997
Company: CPI Card Group Inc. (PMTS)
CPI Card Group Inc. offers physical and digital payment solutions to financial institutions, processors, fintechs, prepaid program managers, and other organizations in the United States. The company operates in two segments: debit and credit, and prepaid debit. It provides secure payment cards, personalization services, instant card issuance solutions, digital payment services, and tamper-evident security packaging. It also offers SaaS-based digital solutions and integrated payment card services for debit, credit, and prepaid accounts. The company was previously known as CPI Holdings I, Inc. before changing its name to CPI Card Group Inc. in August 2015. CPI Card Group Inc. was established in 2007 and is based in Littleton, Colorado.
H. Sanford Riley has served as a Director of CPI Card Group Inc. since May 2023 and was appointed Independent Non-Executive Chairman of the Board in June 2023. He has substantial experience in financial services and corporate governance, having co-founded Richardson Financial Group Limited in 2003 and served as its President and CEO until January 2026. He previously served as President, CEO, and eventually Chairman of Investor Group Inc. for ten years. Riley has served on a number of public business boards and provides extensive leadership and governance experience. He has a Bachelor of Arts degree from Queen’s University and a Juris Doctorate from Osgoode Hall Law School.
Nicholas Peters has been a Director of CPI Card Group Inc. since 2007, when he joined the company’s Board of Directors. He has been a Managing Director of Parallel49 Equity, originally Tricor Pacific Capital, since 2002 and its Chief Financial Officer since 2012. He is also the Managing Member of EXI Investment Partners, which he joined in January 2020, and serves on the boards of many portfolio businesses. Peters has vast experience in finance, accounting, capital markets, and private equity. He has a Bachelor of Science degree in Business Administration from the University of Dayton, Ohio, and is a Certified Public Accountant.
Marc Sheinbaum has been a Director at CPI Card Group Inc. since November 2019, when he joined the company’s Board of Directors. Since 2017, he has advised venture capital and private equity firms. Previously, he was President, CEO, and Director of Higher One Holdings from 2014 to 2016, and he held senior executive positions at JPMorgan Chase from 2007 until 2013. He has over 30 years of expertise in payments, consumer financial services, public company leadership, and business turnarounds. Sheinbaum earned a Bachelor of Science in Management Science from the State University of New York at Albany and an MBA from New York University.
Insomniac Hedge Fund Guy Opinion: This is a growing, cash-generative, cheaply-priced small-cap that just got kicked in the shins by a secondary offering, and the people who know the company best responded by buying nearly $12 million worth of stock at that exact moment. Growth is accelerating, the valuation (PEG 0.57, EV/EBITDA 7.4x) is not pricing in that growth, and my rough DCF and the Street’s $32.50 target both land meaningfully above the current $23.76 price. The knock is real: no recurring-revenue transparency, declining net income, and customer concentration risk. But when a 10% owner and the board chairman put real money behind the stock during a sell-off, that’s not noise, that’s conviction. I’d call PMTS a buy here, small-cap, so size any position accordingly and expect volatility, but the setup favors the bulls.
Name: Homer John Livingston III
Position: Director
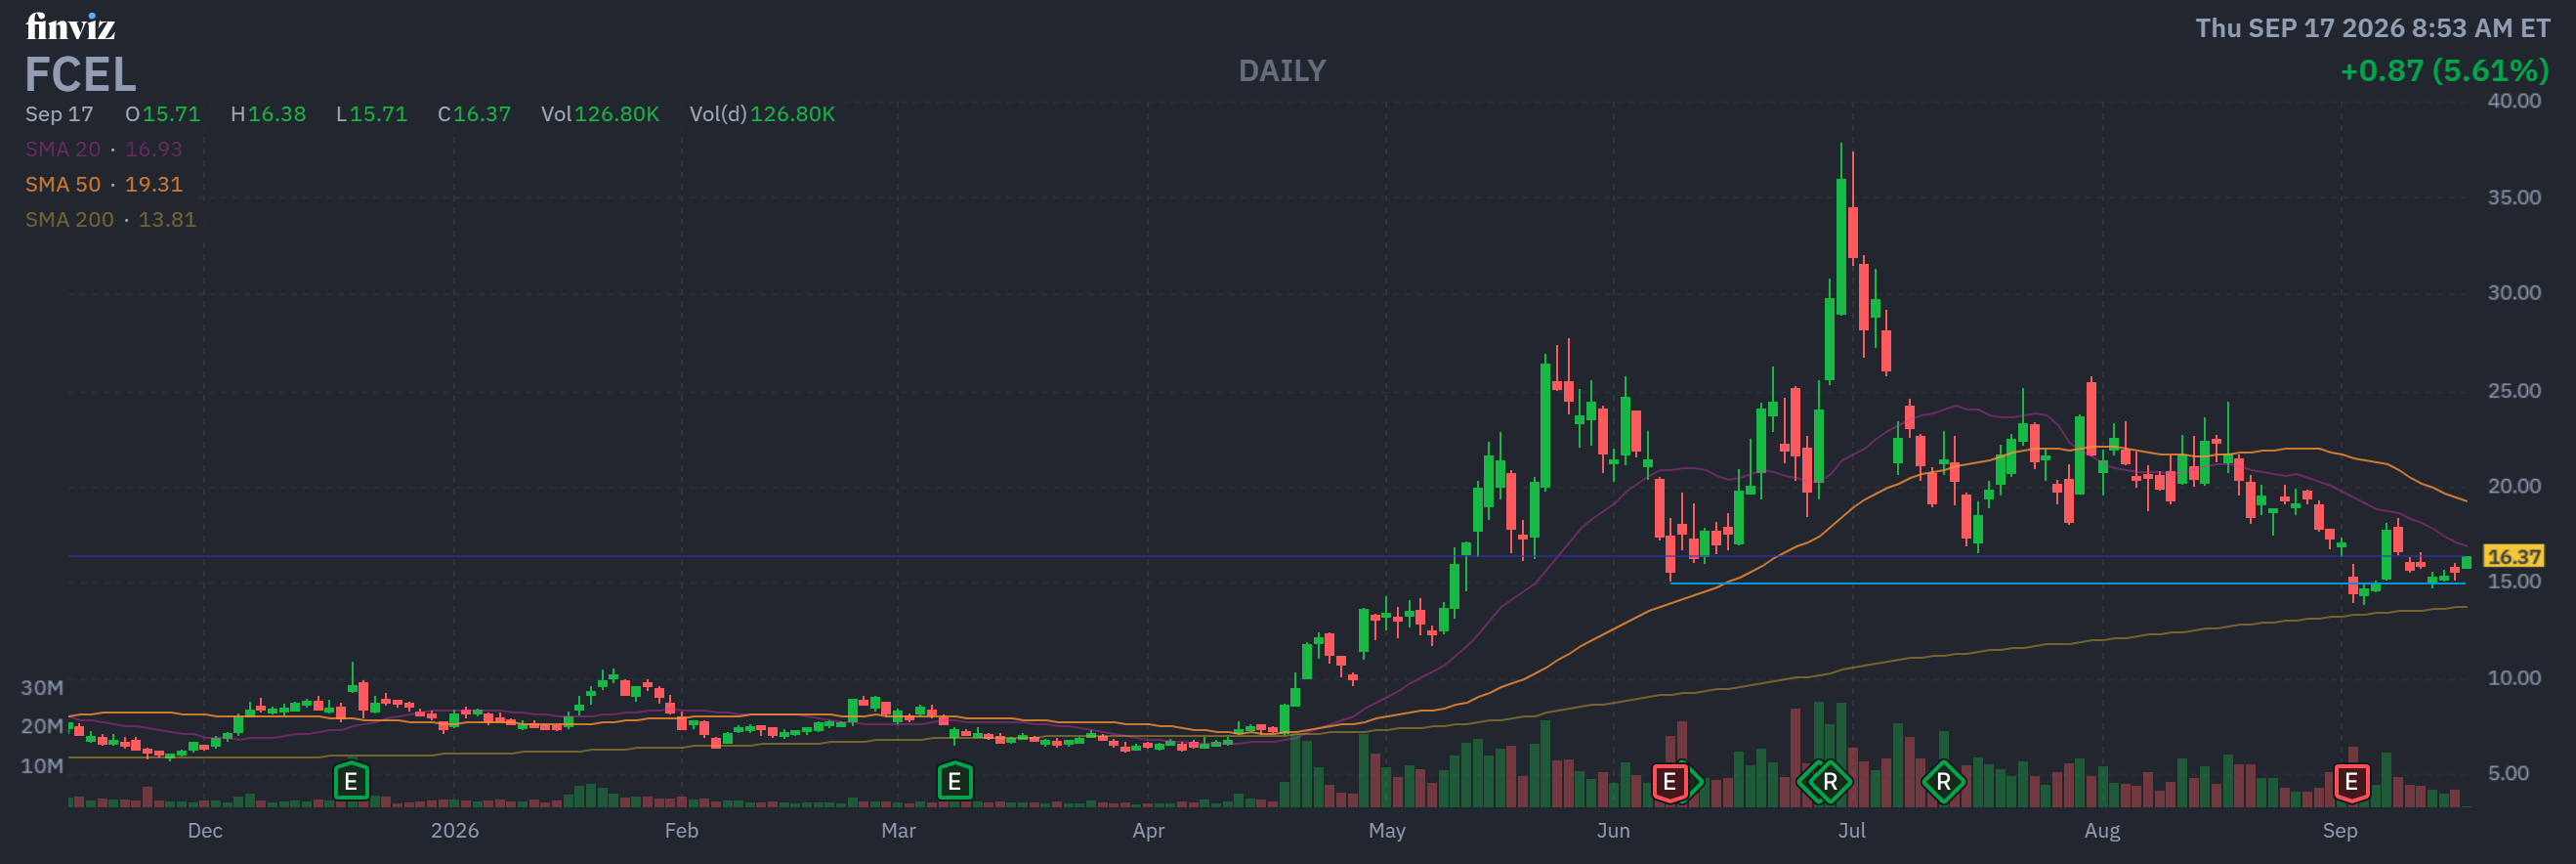
Transaction Date: 09-14-2026 Shares Bought: 16,404 shares an average price paid of $15.05 for Cost: $246,955
Company: Fuelcell Energy Inc. (FCEL)
FuelCell Energy, Inc. and its subsidiaries design, develop, manufacture, build, operate, and service high temperature fuel cells for clean electricity generation. In addition, the corporation offers power, heat, steam, capacity, and renewable energy credits. In addition, the company offers turnkey solutions for fuel cell projects, such as development, engineering, procurement, construction, interconnection, and operation. It provides services to utilities and independent power producers, data centers, wastewater treatment, commercial and hospitality, and microgrids, as well as industrial, commercial, municipal, and government customers such as manufacturing facilities, pharmaceutical processing facilities, universities, and hospitals. The corporation primarily serves the United States, South Korea, Europe, and Canada. FuelCell Energy, Inc. was founded in 1969 and is based in Danbury, Connecticut.
John Livingston has served as an Independent Director of FuelCell Energy, Inc. since May 19, 2026, when he was elected to the company’s Board of Directors. He brings more than 25 years of experience in strategy, industrial technology, and cybersecurity, having founded and served as Chief Executive Officer of Verve Industrial Protection before its acquisition by Rockwell Automation. Prior to that, Livingston spent more than two decades at McKinsey & Company, advising industrial, technology, and infrastructure clients. He holds degrees from Princeton University and the Northwestern University Pritzker School of Law and Northwestern University Kellogg School of Management.
Insomniac Hedge Fund Guy Opinion: FCEL is a wounded animal with a live tail. The core financials are bad: negative gross margins that make Plug Power look healthy by comparison, a revenue base that swings 40% in either direction year to year, and a DCF that doesn’t come close to justifying a $15.50 share price on fundamentals alone. Add a 26.6% short float and you’ve got a stock the market has already voted “no” on with real money. But the data center power story isn’t nothing, and $737 million in cash buys time to execute on it. The insider buy after the earnings miss is a small, genuine signal worth noting, not a reason to chase the stock.
This is a speculative, story-driven trade, not an investment grounded in current fundamentals. I wouldn’t touch it here on valuation, but I wouldn’t short it blind into a 26% short interest either, that’s a crowded trade that can squeeze violently on any real contract news. Watch for actual signed, binding data center agreements, not pipeline talk, before this earns anything better than a pass.
Name: Lawrence Hugh Wilt Jr.
Position: Chief Financial Officer
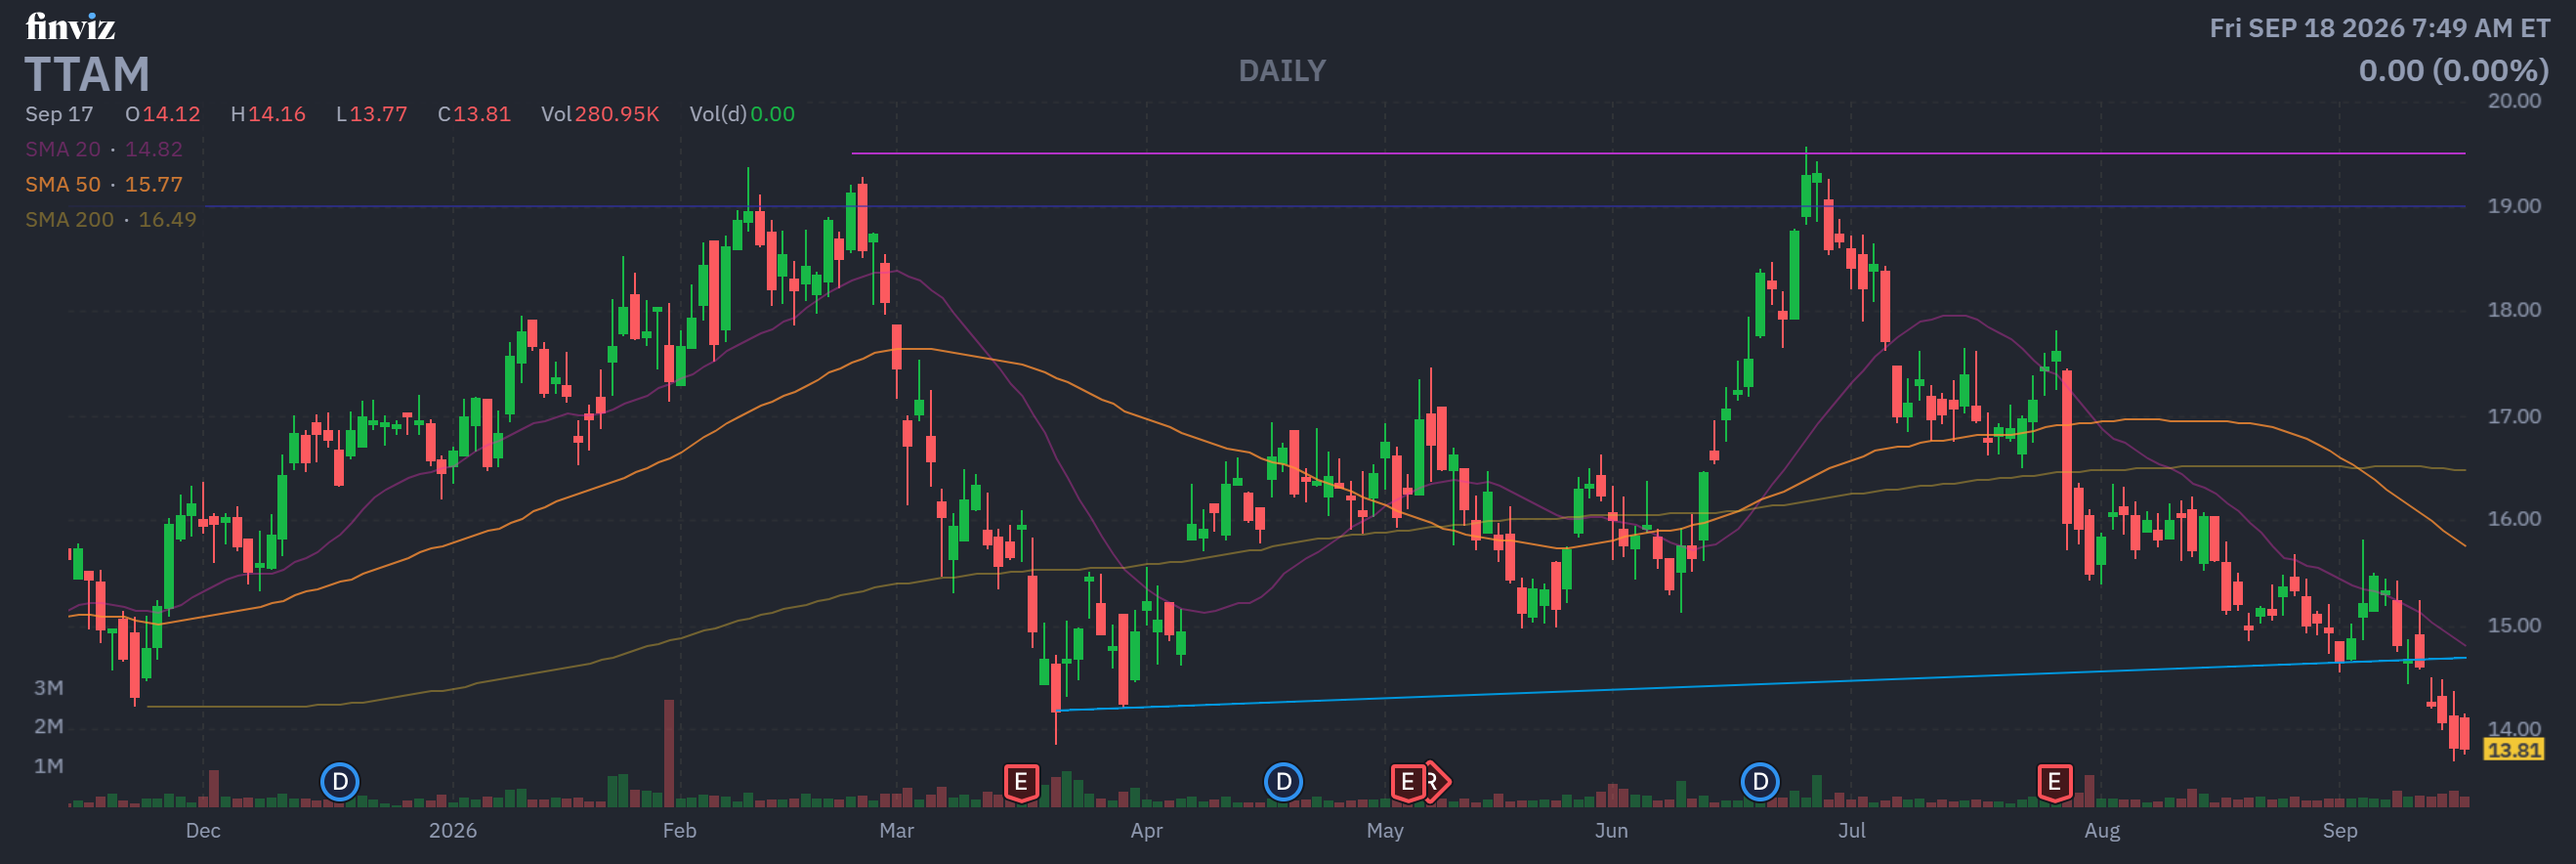
Transaction Date: 03-19-2026 Shares Bought: 20,000 shares an average price paid of $14.93 for Cost: $298,600
Company: Titan America SA (TTAM)
Titan America SA manufactures and supplies heavy building materials and related services in the United States through its subsidiaries. The company offers cement and cementitious materials, ready-mix concrete, aggregates, concrete blocks, fly ash, and other construction products. It also engages in trading, real estate holdings, insurance brokerage, and transportation brokerage activities. The company serves the construction industry through its portfolio of building materials and related services. Titan America SA operates as a subsidiary of Titan Cement International S.A. The company was founded in 1989 and is based in Brussels, Belgium.
Lawrence Hugh Wilt Jr. has worked with Titan America SA since 2000, and he has served as Chief Financial Officer since joining the company’s senior management team. He has vast experience in financial management and has held senior finance positions at Titan America, including vice president and CFO. He has also been an executive member of the board of a Titan-related company since 2010. Wilt earned a Bachelor of Science in Commerce from the University of Virginia, with a focus on business and finance.
Insomniac Hedge Fund Guy Opinion: Titan America is a decent regional operator with a real, if unglamorous, geographic moat, but it’s caught in a growth deceleration and margin squeeze at the same time the whole basic materials sector is out of favor. My DCF lands right around the current price, not a screaming bargain, and the market apparently agrees, sitting near 52-week lows with nearly 12% of the float sold short. This is a Hold, lean cautious, not a stock I’d chase here waiting for the Street’s $18 target to materialize, but also not one I’d short into an infrastructure-spending tailwind that could bail out the Mid-Atlantic segment. Wait for a clean quarter free of one-off maintenance charges before committing new capital either direction.
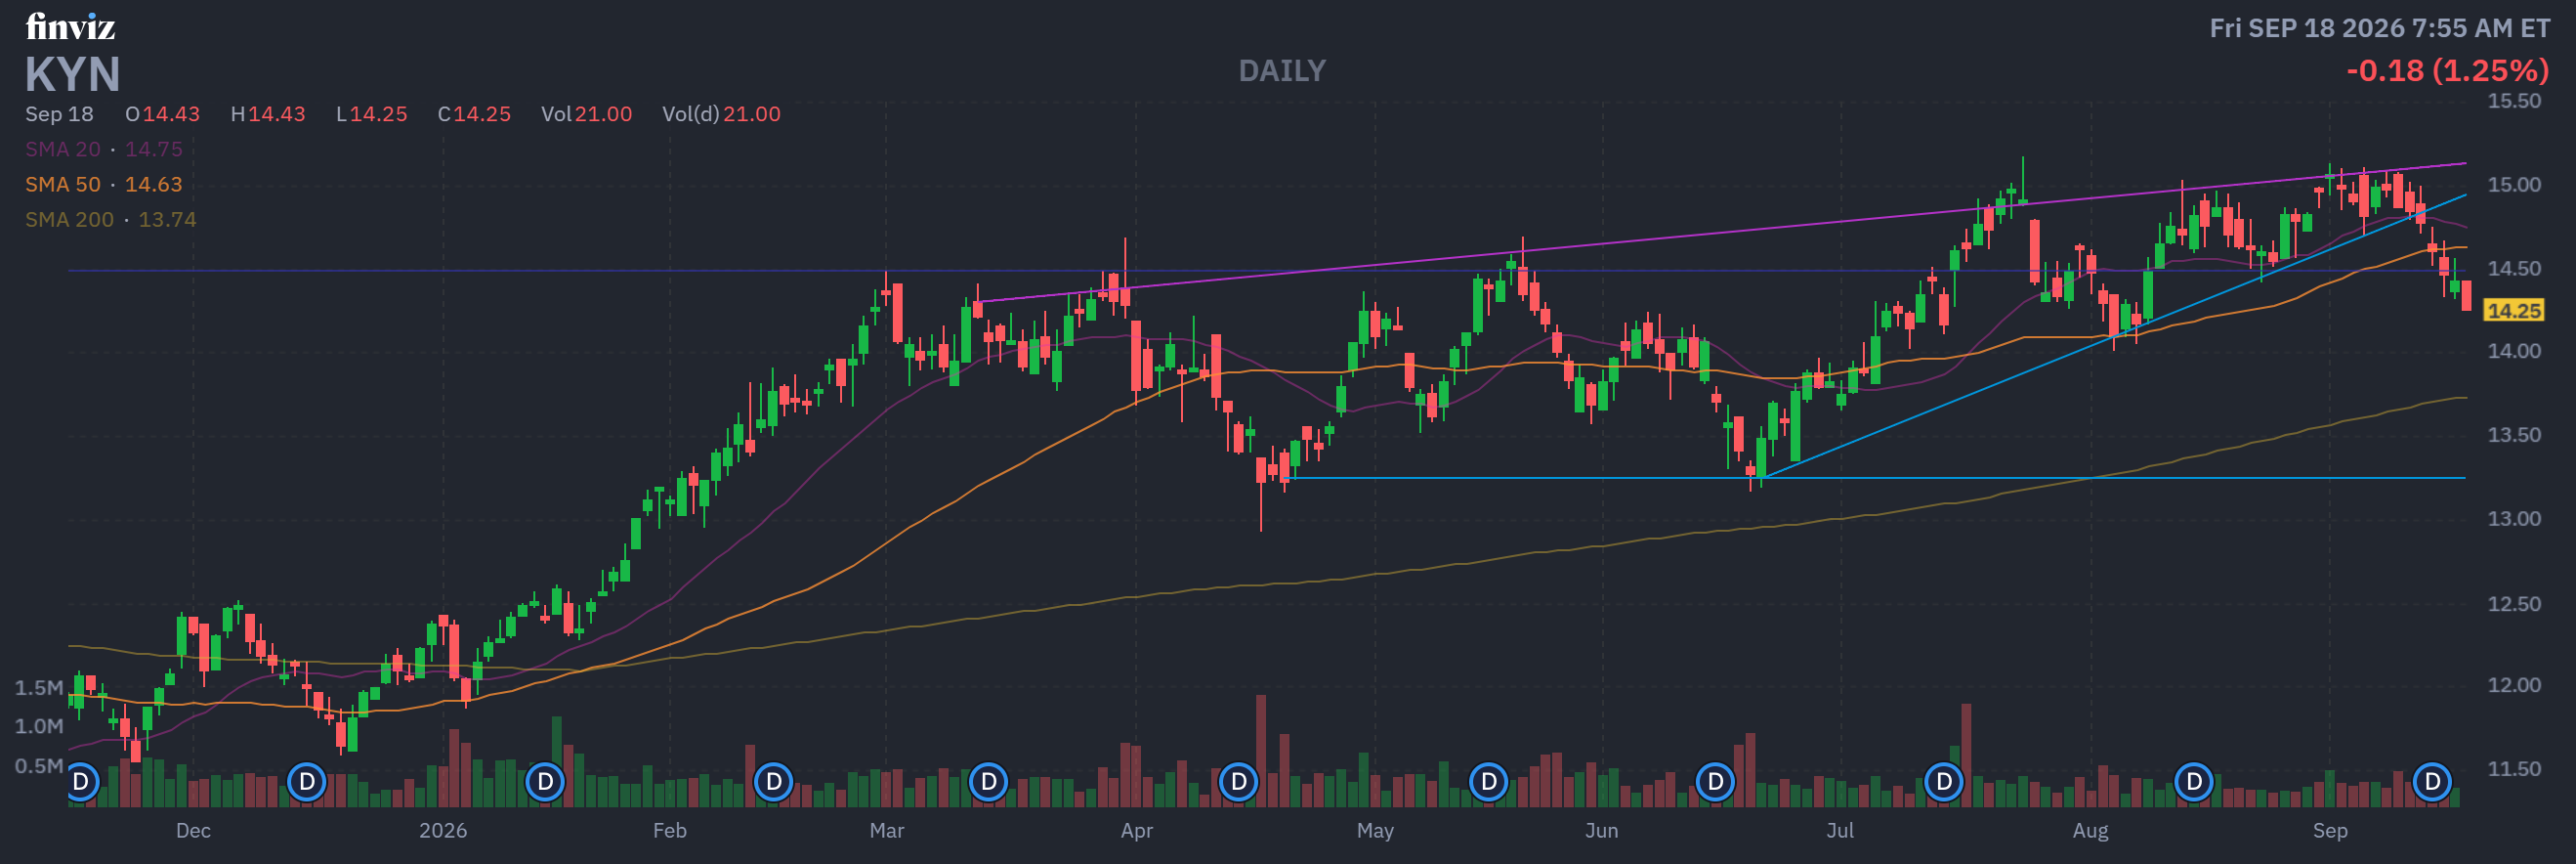
Name: James C. Baker
Position: President
Transaction Date: 03-20-2026 Shares Bought: 25,000 shares an average price paid of $13.99 for Cost: $349,643
Company: Kayne Anderson Energy Infrastructure Fund Inc. (KYN)
Kayne Anderson Energy Infrastructure vehicle, Inc. is a closed-end equity investment vehicle led by KA Fund Advisors, LLC and co-managed by Kayne Anderson Capital Advisors, L.P. The fund primarily invests in US public equity markets, with an emphasis on companies in the energy infrastructure sector. Its primary investments are in energy-related master limited partnerships and other energy infrastructure instruments. The fund aims to give investors exposure to the energy sector by investing in publicly traded firms and partnerships. Kayne Anderson Energy Infrastructure Fund, Inc. was established on June 4, 2004, and is based in the United States.
James C. Baker Jr. has worked with Kayne Anderson Energy Infrastructure Fund Inc. since June 2005, when he became an officer, and has served as President since June 2016. He has served as a Director since June 2005, and Chairman of the Board since June 2020. Baker is also a Managing Partner and Senior Managing Director of Kayne Anderson, with substantial experience in energy investment banking and infrastructure. Before joining Kayne Anderson, he worked as a director in UBS Securities’ energy investment banking group. He earned a BBA in Finance from the University of Texas and an MBA from Southern Methodist University.
Insomniac Hedge Fund Guy Opinion: KYN is a leveraged, high-yield way to get midstream energy exposure at a real discount to its underlying asset value, and the yield (7%+) is currently well-covered by cash flow. That’s the bull case, and it’s not nothing. But there’s no growth story, no moat beyond the underlying holdings’ pipelines, and the “cheap” NAV discount has no obvious catalyst to close it soon. I’d call this a hold for income seekers who already want energy infrastructure exposure and are comfortable with leverage risk, not a stock I’d chase for capital appreciation. If you want the yield and can stomach commodity-driven swings, fine. If you’re looking for a growth trade, look elsewhere.
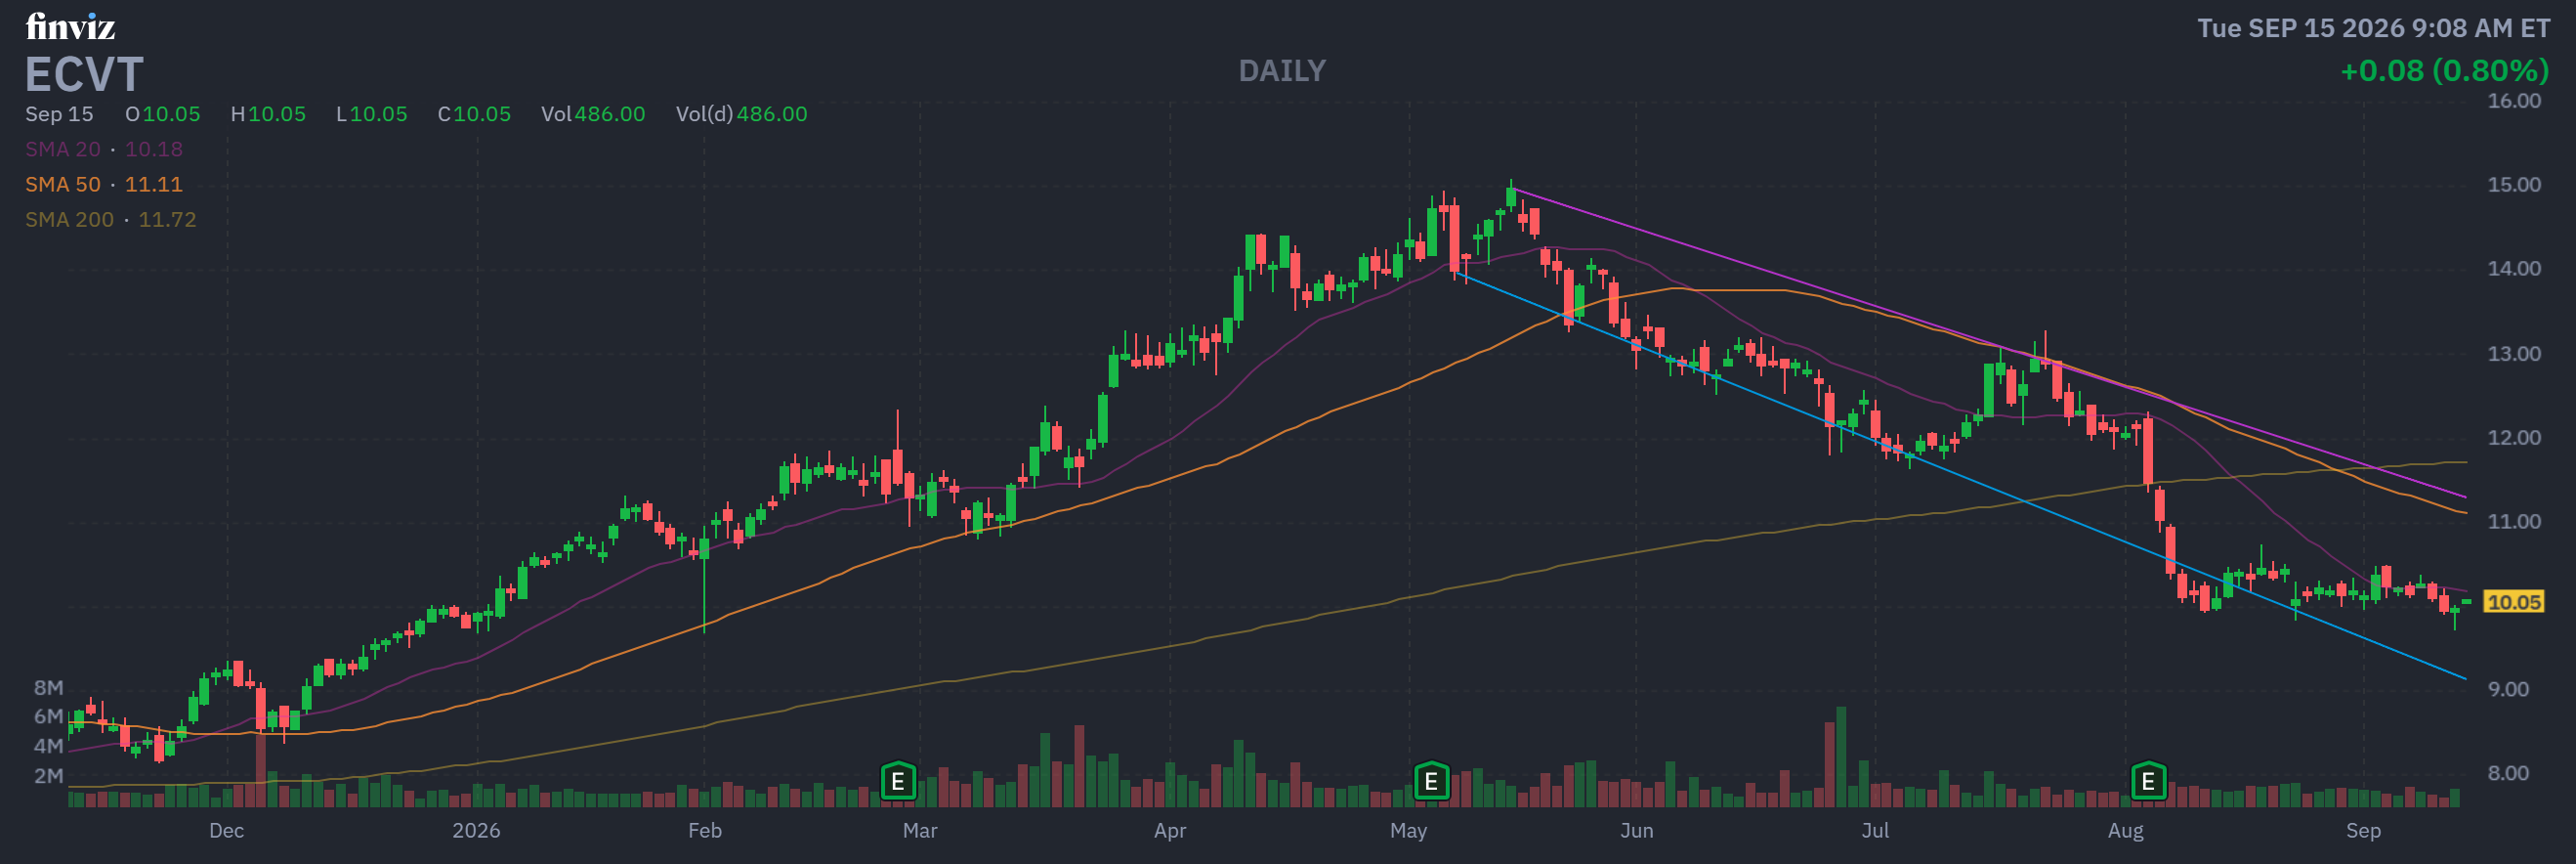
Name: Patti A. Humble
Position: Director
Transaction Date: 09-10-2026 Shares Bought: 24,875 shares an average price paid of $10.05 for Cost: $249,994
Company: Ecovyst Inc. (ECVT)
Ecovyst Inc. offers virgin and regenerated sulfuric acid goods and services in the United States and around the world. The company provides comprehensive logistics and sulfuric acid solutions for refineries, mining, water treatment, and industrial applications. It also facilitates the manufacturing of alkylate for refineries and offers specialized solutions for a variety of industrial operations. Ecovyst’s specialized chemical manufacturing and service capabilities benefit customers across a wide range of sectors. The company was previously known as PQ Group Holdings Inc. before changing its name to Ecovyst Inc. in August 2021. Ecovyst, Inc. was founded in 1831 and is headquartered in Wayne, Pennsylvania.
Patti A. Humble has been a Director of Ecovyst Inc. since May 2026, when she joined the company’s Board of Directors and the Audit Committee. She has over 30 years of accounting and finance experience, most recently serving as United Parcel Service’s Chief Accounting Officer from August 2019 until her retirement in December 2024. She has also held different financial leadership positions at UPS and currently serves on the Institute of Management Accountants’ Board of Directors. Humble earned a Bachelor of Business Administration in Accounting with good distinction from the University of Iowa.
Insomniac Hedge Fund Guy Opinion: Ecovyst is a cheap-on-cash-flow, structurally-moated, but genuinely risky industrial chemicals name getting dragged down by a sector nobody wants right now. The fundamentals (raised guidance, EPS beat, insider buying, reasonable EV/EBITDA) argue for value here; the concentrated customer base, leverage, and choppy revenue history argue for caution. My DCF says it’s roughly fairly valued near $10, Wall Street says there’s 50%+ upside to the mid-teens. I’ll split the difference: this is a speculative buy for investors comfortable with cyclical, customer-concentrated industrial names, not a name I’d back up the truck on, but one worth a starter position if you believe the sector rotation turns and Calabrian synergies land on schedule.
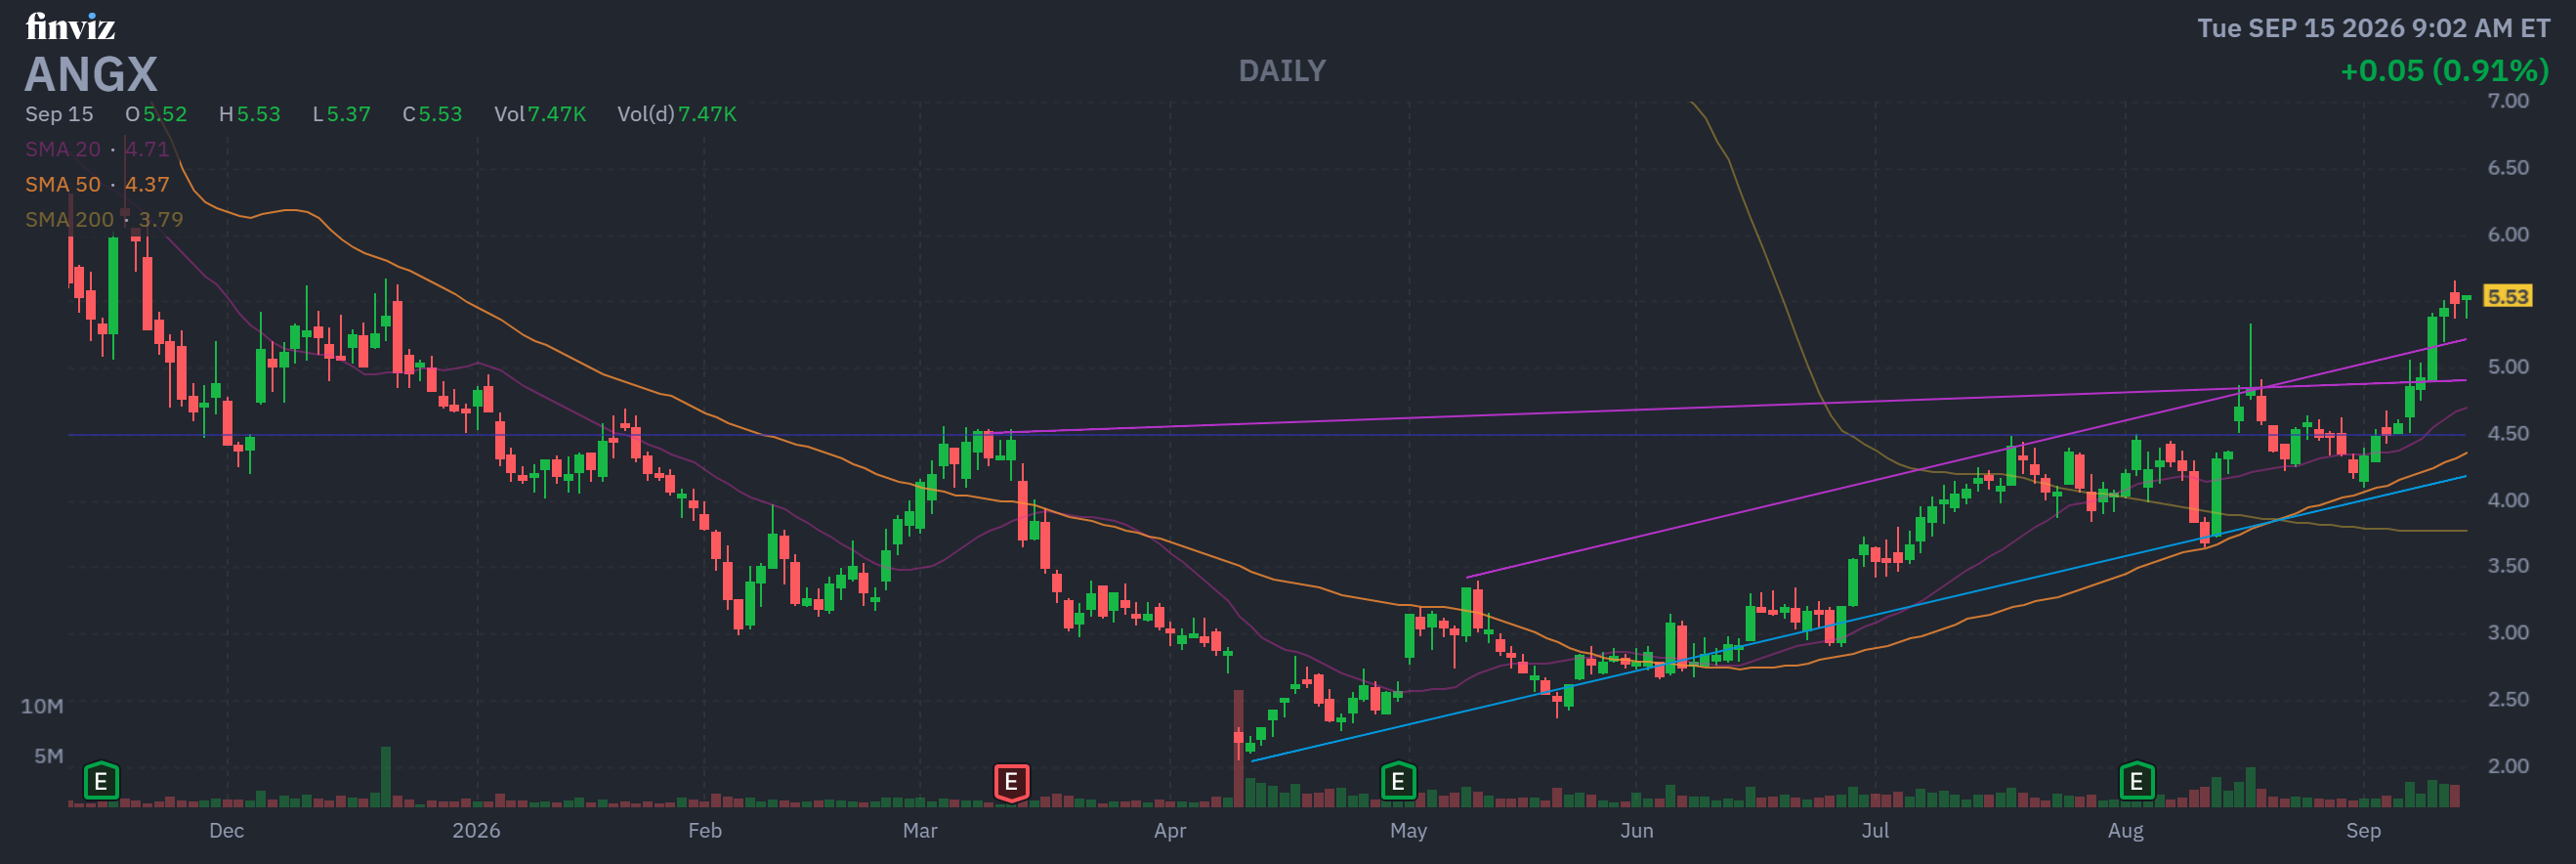
Name: Steven I. Sarowitz
Position: Director
Transaction Date: 09-11-2026 Shares Bought: 88,647 shares an average price paid of $5.33 for Cost: $472,604
Company: Angel Studios Inc. (ANGX)
Angel Studios, Inc. is a media and technology firm. The company produces and distributes films and television series, as well as licensed films and shows. The company’s streaming platform enables customers to watch movies, series, and documentaries of various ages. It also provides clothes, DVDs, Blu-rays, and books; a direct online store for Angel Studios-themed products; wholesale products to retail partners; and content licensing services. In addition, the organization offers Angel Guild memberships, theatrical ticket presales, theatrical distribution, theatrical pay it forward, and retail services. The company was previously known as VidAngel, Inc., but changed its name to Angel Studios, Inc. in March 2021. Angel Studios, Inc. was created in 2013 and is headquartered in Provo, Utah.
Steven I. Sarowitz has served as a Director of Angel Studios Inc. since September 2025, joining the Board upon the completion of the company’s business combination. He is the founder of Paylocity, a leading provider of payroll and HR software, and previously served as its Chairman until August 2024. Sarowitz also served as CEO of Blue Marble Payroll before its acquisition by Paylocity in 2021 and is a partner in Wayfarer Studios and several other investment ventures. In addition to his business leadership, he is an active philanthropist and film producer. He holds a Bachelor of Arts in Economics from the University of Illinois at Urbana.
Insomniac Hedge Fund Guy Opinion: ANGX is a high-growth story wrapped around a company that hasn’t figured out how to make money yet, but the people running it are putting their own cash where their mouth is, three separate buys from a director in September alone. The Perfect10 composite comes in at +1.3 on a -10 to +10 scale, a mixed-to-neutral read, dragged down by ugly cash flow and offset by bullish insider activity and an undervaluation signal against the Street’s $8 target. Modest short interest (3.8% of float, 3.4 days to cover) tells you bears aren’t convinced this is a slam-dunk short either. I’d call this a speculative buy for investors who can stomach volatility and want exposure to the subscriber growth story, not a name for anyone who needs profitability or a clean balance sheet to sleep at night. Size it like the high-risk bet it is.
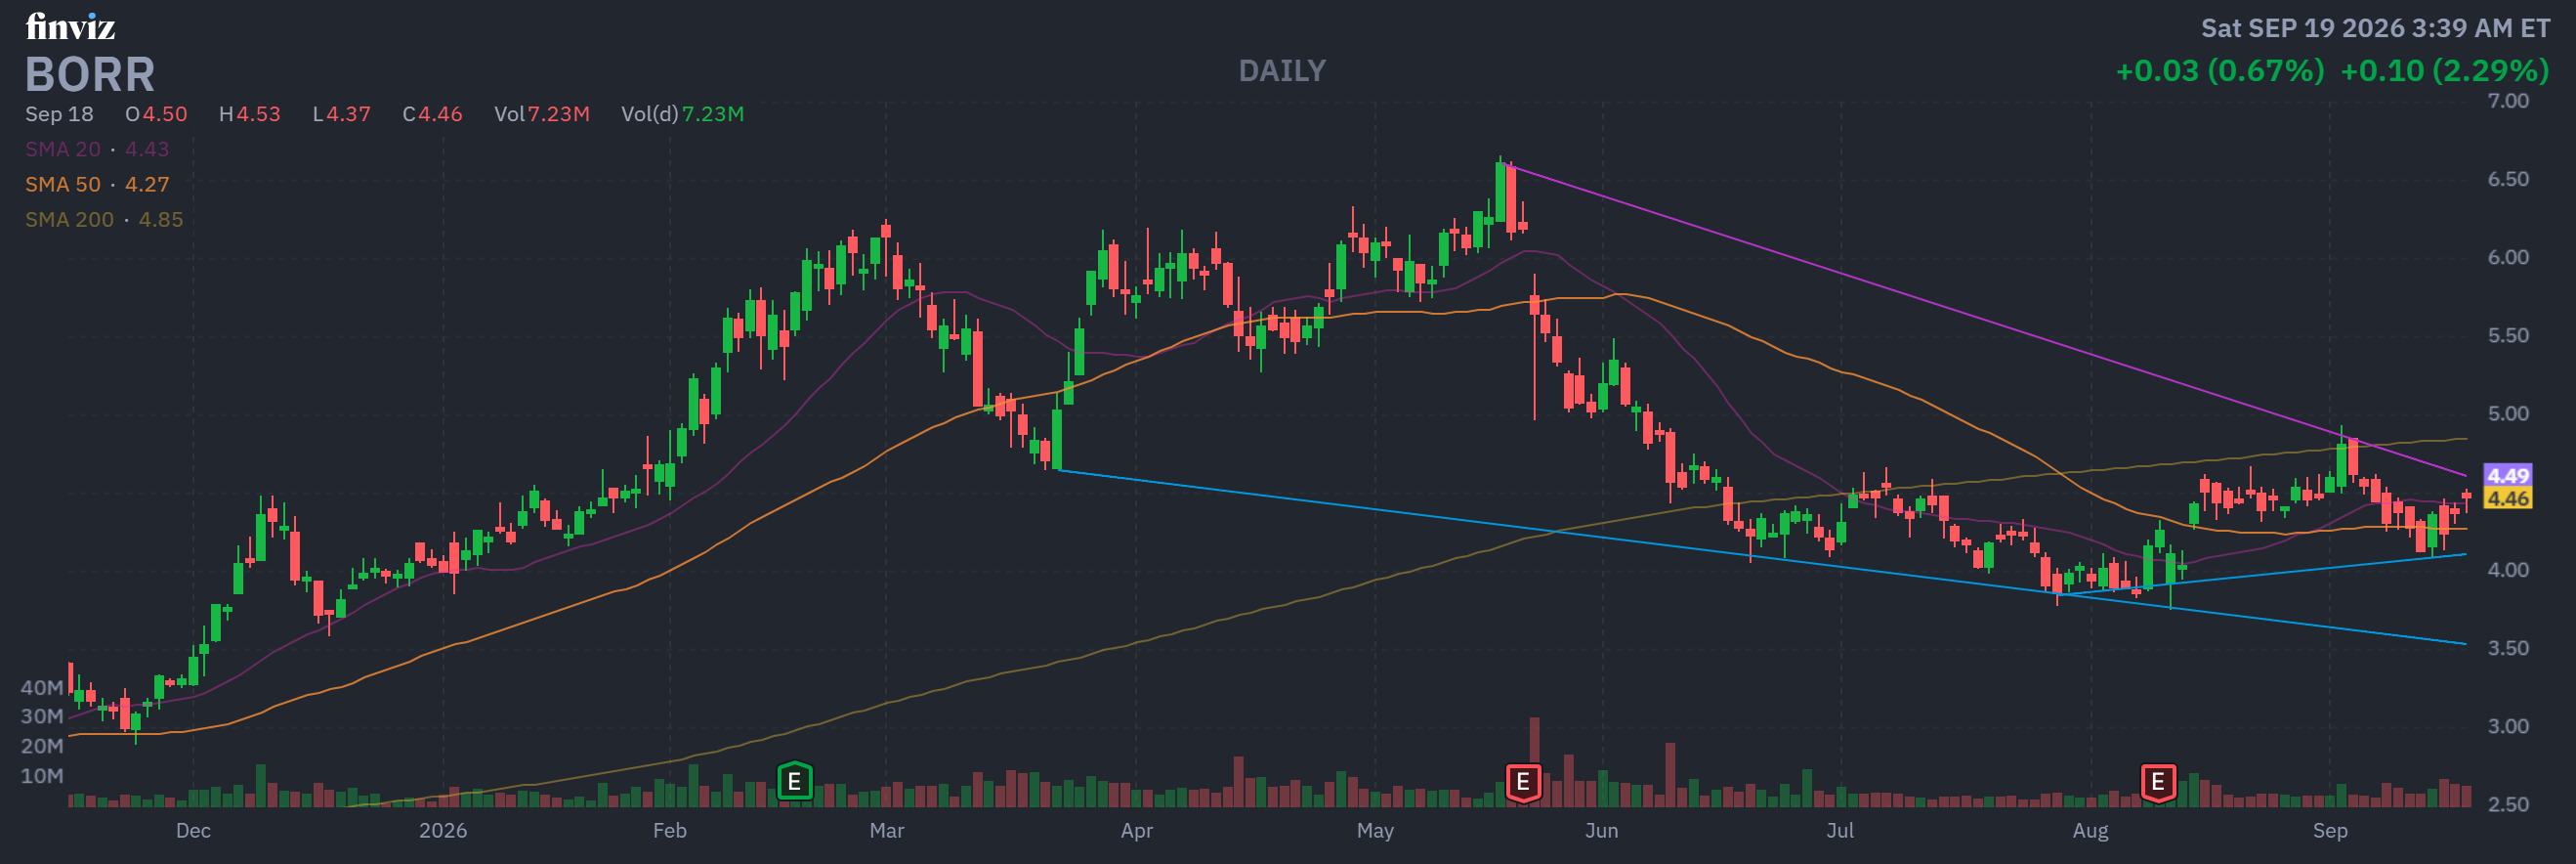
Name: Tor Olav Troim
Position: Director
Transaction Date: 09-18-2026 Shares Bought: 150,000 shares an average price paid of $4.38 for Cost: $656,925
Transaction Date: 09-17-2026 Shares Bought: 1,000,000 shares an average price paid of $4.30 for Cost: $4,299,500
Company: Borr Drilling Ltd. (BORR)
Borr Drilling Limited provides offshore shallow-water drilling services to the oil and gas industries in the Americas, Southeast Asia, West Africa, the Middle East, North Africa, and Europe. It owns, contracts, and operates jack-up rigs for shallow-water operations, as well as providing related equipment and work crews for oil and gas drilling and workover activities in exploration and production. It caters to oil and gas exploration and production companies, including integrated oil companies, state-owned national oil enterprises, and independent oil and gas producers. The company was previously known as Magni Drilling Limited before changing its name to Borr Drilling Limited in December 2016. Borr Drilling Limited was established in 2016 and is headquartered in Hamilton, Bermuda.
Tor Olav Troim has served as a Director of Borr Drilling Ltd. since the company’s incorporation in 2016 and was one of its founders. He has also served as Chairman of the Board from August 2017 to September 2019 and again from February 2022 to September 2025. Troim has more than 30 years of experience in the energy and offshore drilling industries, having previously held senior leadership positions, including CEO of Seadrill Ltd., Frontline Ltd., Golar LNG Partners LP, and DNO AS. He is also the founder of Magni Partners and serves on the boards of several international companies. He earned a Master of Science (MSc) degree in Naval Architecture from the University of Trondheim, Norway.
Insomniac Hedge Fund Guy Opinion: BORR is a modern fleet in a cyclical business that’s currently stuck between a shrinking backlog and a hopeful 2028 recovery story. The insider buying from Trøim is the loudest signal in this whole report, that’s real money from the person closest to the business betting the market has this wrong. Add a bullish chart setup and a Buy-rated analyst consensus, and there’s a credible short-term trading case here, especially given the double-digit short interest that could accelerate any move higher.
But the fundamentals underneath aren’t cheap enough to ignore the risk: declining backlog, a projected 2026 net loss, and 55x earnings on a business whose earnings are currently depressed. I’d call this a speculative buy for anyone comfortable riding offshore drilling cyclicality, not a core holding. Watch the backlog trend next quarter; if it stabilizes, the insider bulls look smart. If it keeps shrinking, the DCF math tips toward the low end of that $3.50-$5.00 range fast.
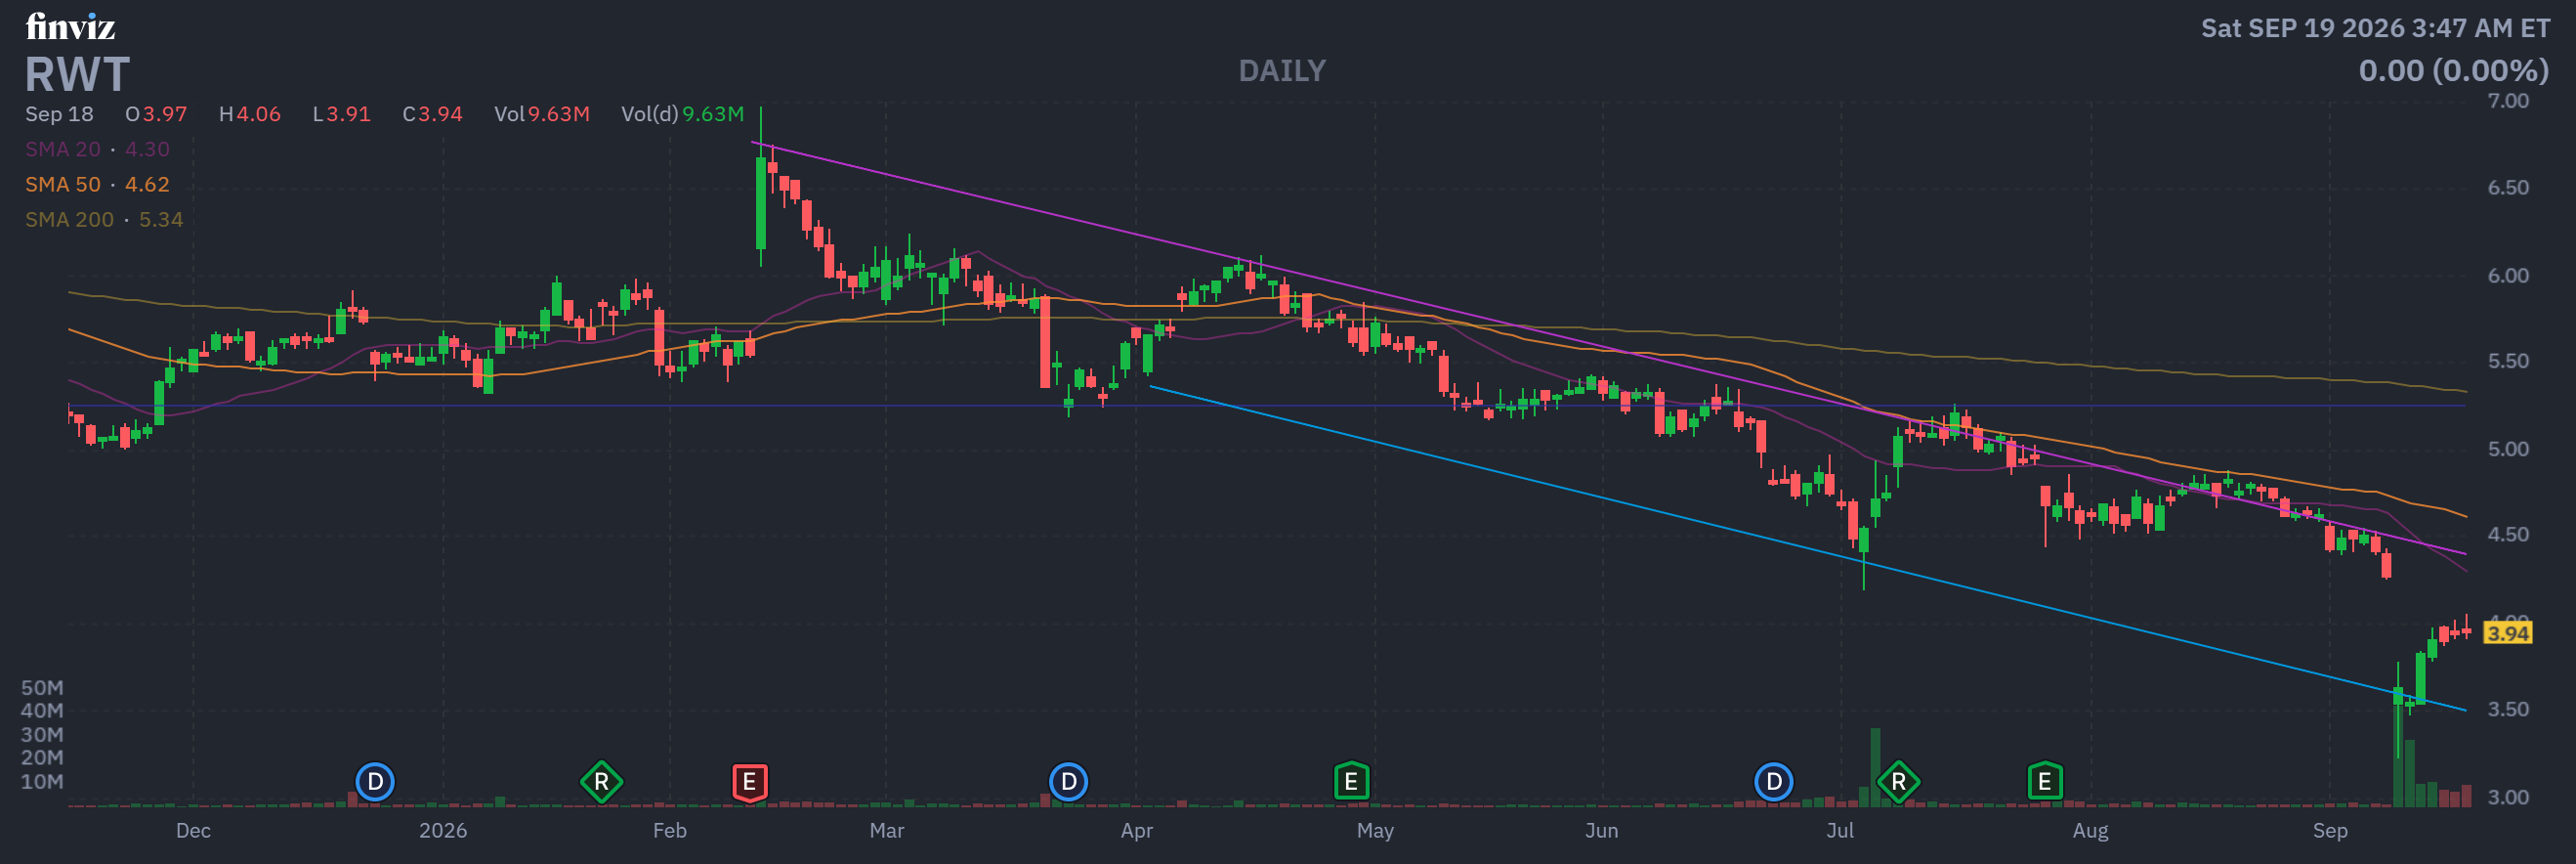
Name: Dashiell I. Robinson
Position: President
Transaction Date: 09-16-2026 Shares Bought: 63,211 shares an average price paid of $3.98 for Cost: $251,580
Name: Greg H. Kubicek
Position: Director
Transaction Date: 09-15-2026 Shares Bought: 50,000 shares an average price paid of $3.85 for Cost: $192,560
Name: Christopher J. Abate
Position: Chief Executive Officer
Transaction Date: 09-15-2026 Shares Bought: 100,000 shares an average price paid of $3.84 for Cost: $383,900
Company: Redwood Trust Inc. (RWT)
Redwood Trust, Inc. is a specialty finance corporation with four business segments: Sequoia Mortgage Banking, CoreVest Mortgage Banking, Redwood Investments, and Legacy Investments. The company purchases residential mortgage loans for sale, securitization, or investment and creates residential investor loans through its CoreVest platform. Its investment portfolio is primarily focused on housing credit-related investments, which include retained interests from its own securitizations and other internally generated investments. Legacy Investments manages non-core assets, such as legacy loans and residential securities, as they are sold, run off, or otherwise disposed of. Redwood Trust, Inc. was established in 1994 and is based in Mill Valley, California.
Dashiell I. Robinson has been President of Redwood Trust, Inc. since December 2017, having joined the company in September 2017. He joined Redwood’s Board of Directors in August 2021. Robinson was previously Head of Mortgage Finance in Wells Fargo Securities’ Asset-Backed Finance Group, and he had previously worked in banking, structuring, and risk reduction at Wachovia Capital Markets. He has substantial experience with mortgage finance, structured credit, and housing finance. Robinson earned a B.A. in English from Georgetown University.
Greg H. Kubicek has been a Director of Redwood Trust, Inc. since 2002 and now serves as Chair of the Board, which he has done since May 2022. He did not join Redwood as an employee; his involvement with the company began with his Board appointment. Kubicek is the founder and former CEO of The Holt Group, a real estate company, and then became CEO of GHK Enterprises after it was acquired by Sekisui House. He had previously served as Chair of Cascade Corporation. He earned an A.B. in Economics from Harvard College.
Christopher J. Abate joined Redwood Trust, Inc. in April 2006 and has been the company’s Chief Executive Officer since May 2018. He joined Redwood’s Board of Directors in December 2017 and was appointed CEO the following year. Before becoming CEO, he was President, Chief Financial Officer, and Controller, with substantial experience in accounting, finance, and complex finance. Prior to Redwood, he worked with PricewaterhouseCoopers. Abate has a B.A. in Accounting and Finance from Western Michigan University and an M.B.A. from the University of California, Berkeley, and Columbia University.
Insomniac Hedge Fund Guy Opinion: RWT is a battered mortgage REIT trading at roughly half of book value, carrying a dividend yield so high it’s practically waving a warning flag, and posting negative earnings. Normally that combination is a pass. But the CEO and President just put a combined $635,000 of their own money into the stock within days of each other, there’s an activist pushing for a sale, and analysts see 46% upside to target. This is a high-risk, high-conviction speculative situation, not a steady compounder. If the dividend holds and the strategic-alternatives process produces a sale or a real turnaround, there’s real upside from here. If book value keeps eroding, that discount is a trap, not a bargain. I’d call this a speculative buy for investors who can stomach REIT-level volatility and are watching the dividend coverage closely, not a name for anyone needing dependable income. Do your own homework before sizing a position, this is analysis, not a personal recommendation.
This blog is solely for educational purposes and the author’s own amusement. IT IS NOT INVESTMENT ADVICE. Think of the blog as part of my personal investment journal that I am willing to share with the DIY investor. We could be long, short, or have no position at all in any of the stocks mentioned and express no written or implied obligation to disclose any of that. Nothing contained here constitutes a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal, and past performance is not indicative of future results.
“The insomniac hedge fund guy” is a moniker Harvey Sax, the portfolio manager for The Insiders Fund” has used from time to time on email, blog ,and social media posts. While Mr. Sax is the portfolio manager of The Insiders Fund, these posts are not communications from, nor endorsed by, Alpha Wealth Funds, LLC or any of its managed funds. References to Alpha Wealth Funds or its affiliates are for identification only and do not imply sponsorship or approval.
All company names, logos, and trademarks belong to their respective owners. The use of company logos is solely for descriptive and illustrative purposes under fair use. Any information provided is based on publicly available data and should not be considered financial, investment, or legal advice. Readers should conduct their own research or consult with a professional before making any investment decisions. Insiders sell the stock for many reasons, but they generally buy for just one – to make money. You’ve always heard the best information is inside information. Everyone with any stock market experience pays close attention to what insiders are doing. After all, who knows a business better than the people running it? Officers, directors, and 10% owners are required to inform the public through a Form 4 Filing of any transaction, buy, sell, exercise, or any other within 48 hours of doing so.
This info is available for free from the SEC’s Web site, Edgar, although we subscribe to SECForm4 as they provide a way to manage and make sense of the vast realms of data. I’ve tried a lot of vendors. SECForm4 is one of the smaller ones, but I like supporting Frank. He is not arrogant. He’s helpful and has great prices. He also trades on his own data, so I like people that eat what they kill. The bar is different from selling because the natural state of management is to be a seller. This is because most companies provide significant amounts of management compensation packages as stock and options. Therefore, we analyze unusual patterns with selling, such as insiders selling 25 percent or more of their holdings or multiple insiders selling near 52-week lows. Another red flag is large planned sale programs that start without warning. Unfortunately, the public information disclosure requirements about these programs, referred to as Rule 10b5-1, are horrendously poor. Also, planned sales that pop up out of nowhere are basically sales and are seeking cover under this corporate welfare loophole.
I also generally ignore 10 percent shareholders as they tend to be OPM (other people’s money) and perhaps not the smart money on which we are trying to read the tea leaves. I say generally because some 10% shareholders are great investor, think Warren Buffett and others. Of course, insiders can also be wrong about their Company’s prospects. Don’t let anyone fool you into believing they never make mistakes. Do your own analysis. They can easily be wrong, and in many cases, maybe most cases, have no more idea what the future may hold than you or me. In short, you can lose money following them. We have, and we curse aloud; what were they thinking!
We like Fly on the Wall for keeping up with what events might be happening, analysts’ comments, and whatever else could be moving the stock. Dow Jones news service is an essential tool, but many services pick up their feed like they do Bloomberg. My assistant probes the 10k for a reasonable description of the business. I’ve found that to be the most accurate and succinct place to find out what a business actually does.
For more, please visit out website at https://insomniachedge.com/