We are rapidly approaching a surge of third-quarter earnings reports. While the market consensus anticipates earnings beats, I expect the subsequent webcast calls to reveal a lack of confidence regarding fourth-quarter forecasts. I invite you to utilize Veru’s 365 Attaboy strategy to evaluate analyst sentiment during this critical period. For a limited time, Attaboy is available at no additional cost with a subscription to The Insomniac Hedge Fund Guy. I encourage you to explore this opportunity, as similar market intelligence is frequently offered by premium services at a significant cost.
Economic conditions remain challenging across most sectors, with the notable exception of those benefiting from the unprecedented data center build-out; even that cohort, however, is showing signs of fatigue. A recent report from Gartner predicts that over 80% of neocloud providers will cease independent operations by 2030 due to a substantial revenue shortfall relative to capital expenditures, triggering significant market volatility. This, coupled with the realization that the Middle East’s trillion-dollar investment in AI infrastructure may be at risk, has undoubtedly exacerbated ongoing uncertainty. Furthermore, the extensive deployment of data centers has emerged as a key midterm election issue, with a significant majority of voters demanding a deceleration in infrastructure development. As the primary engine of growth begins to sputter, we must consider whether this will catalyze a capital reallocation toward beaten-down sectors or if rising Federal Reserve interest rates will stifle such a rotation entirely.
Name: Robert C. Pohlad
Position: Director
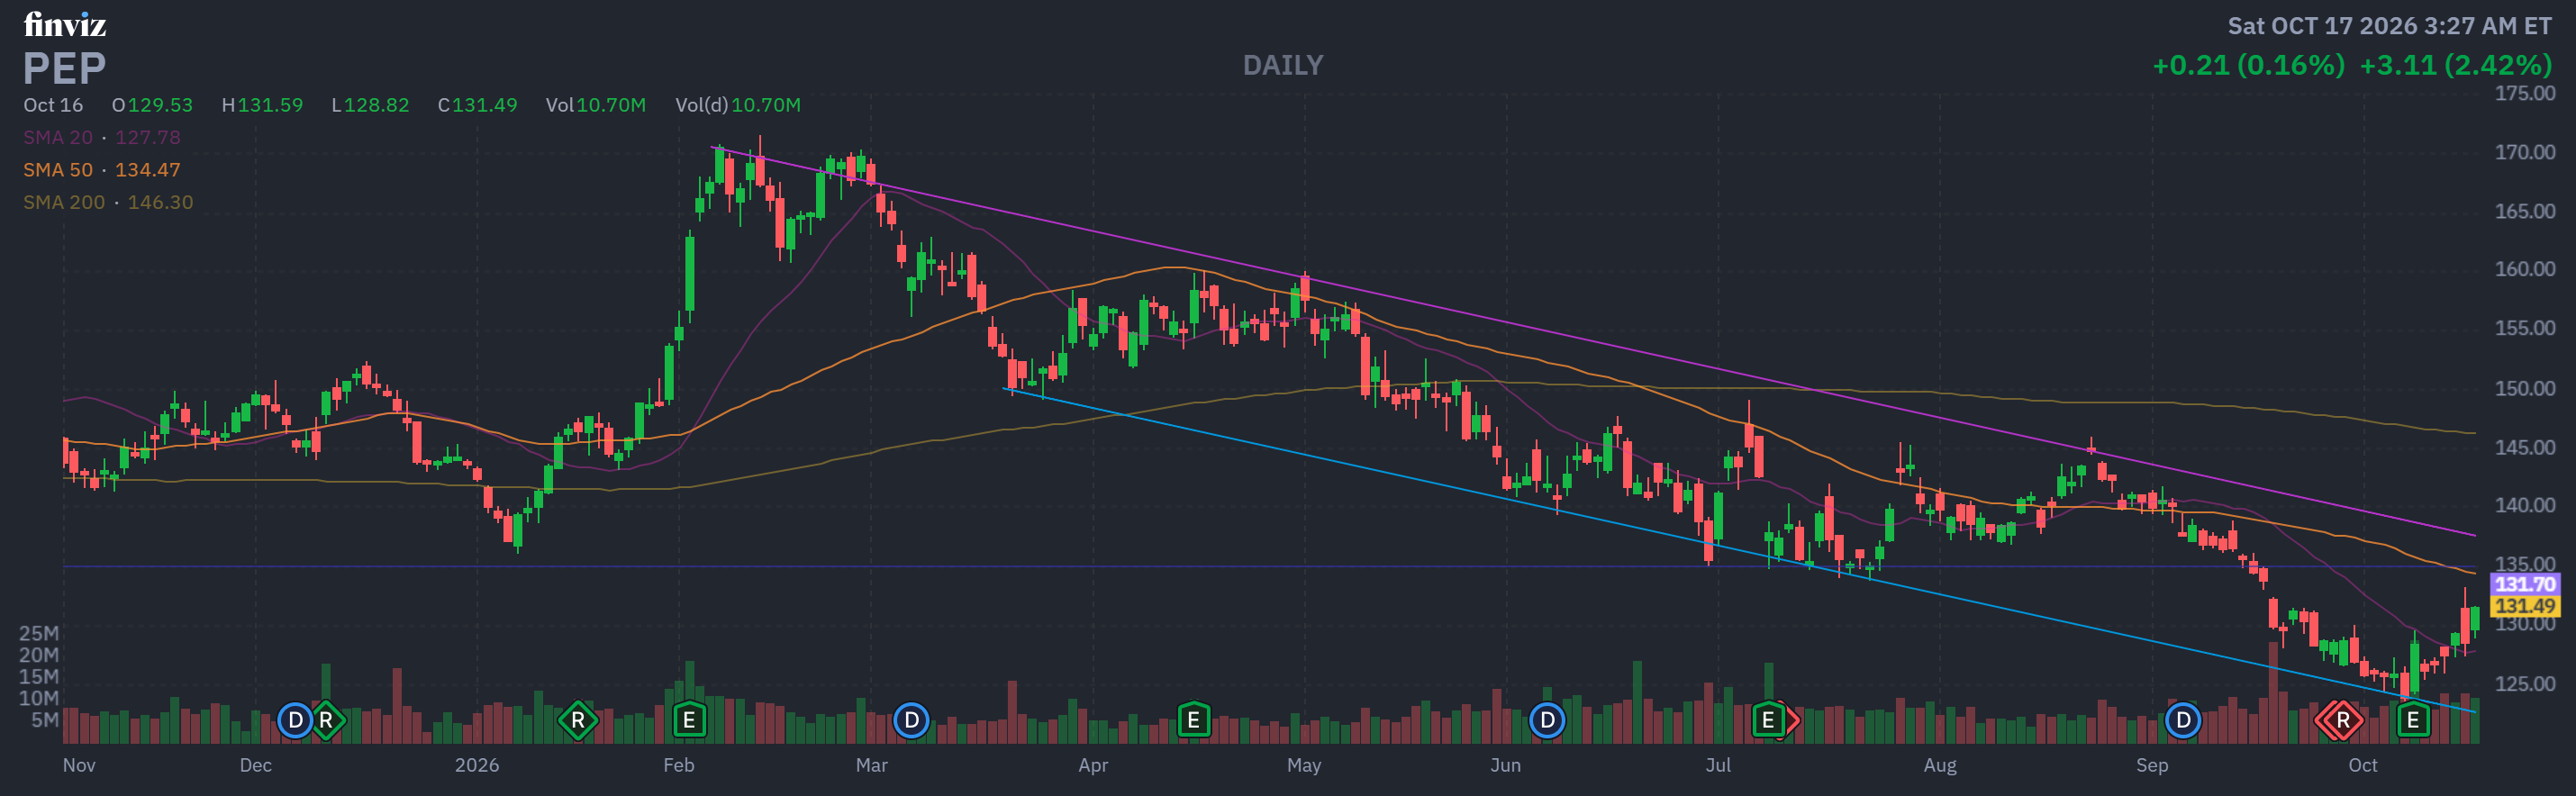
Transaction Date: 10-14-2026 Shares Bought: 184,646 shares an average price paid of $128.28 for Cost: $23,686,389
Company: Pepsico Inc. (PEP)
PepsiCo, Inc. is a multinational food and beverage company engaged in the manufacture, marketing, distribution, and sale of convenient foods and beverages worldwide. The company operates through six segments covering North America, Latin America, Europe, the Middle East, Africa, and Asia Pacific. Its product portfolio includes cereals, chips, dips, granola bars, oatmeal, pasta, rice, syrups, beverage concentrates, soft drinks, ready-to-drink tea and coffee, sparkling water products, and dairy products. The company markets products under various brands, including Pepsi, Lay’s, Gatorade, Quaker, and SodaStream. It serves retailers, distributors, foodservice customers, and consumers through extensive distribution networks and e-commerce platforms. PepsiCo, Inc. was founded in 1898 and is based in Purchase, New York.
Robert C. Pohlad has served as a Director of PepsiCo, Inc. since March 2015, when he joined the company’s Board of Directors as an independent director. He previously served as Chairman and Chief Executive Officer of PepsiAmericas from 2002 until its acquisition by PepsiCo in 2010, having held leadership roles in the Pepsi-Cola bottling business since the 1980s. He has served as President and CEO of Pohlad Holdings and its predecessor businesses since 1987, overseeing interests across several industries, including real estate, finance, and sports and entertainment. Pohlad graduated from Arizona State University.
Insomniac Hedge Fund Guy Opinion: PEP is a slow-growth, cash-generating consumer staple trading at a reasonable price after a guidance cut that the market has already shrugged off. The dividend yield above 4.5% and a DCF value modestly above the current price make this look more like a “park your money and collect the check” holding than a growth story. This is a tortoise, not a hare, and anyone buying it for upside beyond mid-single digits is in the wrong aisle. The real long-term threat isn’t North American margins, it’s the slow erosion of snack and soda demand from GLP-1 drugs, and that’s worth watching over the next several years, not the next quarter. On the numbers, this leans toward a cautious hold: fine for income-focused portfolios, unexciting for anyone chasing growth. None the less $24 billion insider buy is certainly a vote of confidence.
Name: Mark Lappe
Position: Chief Executive Officer
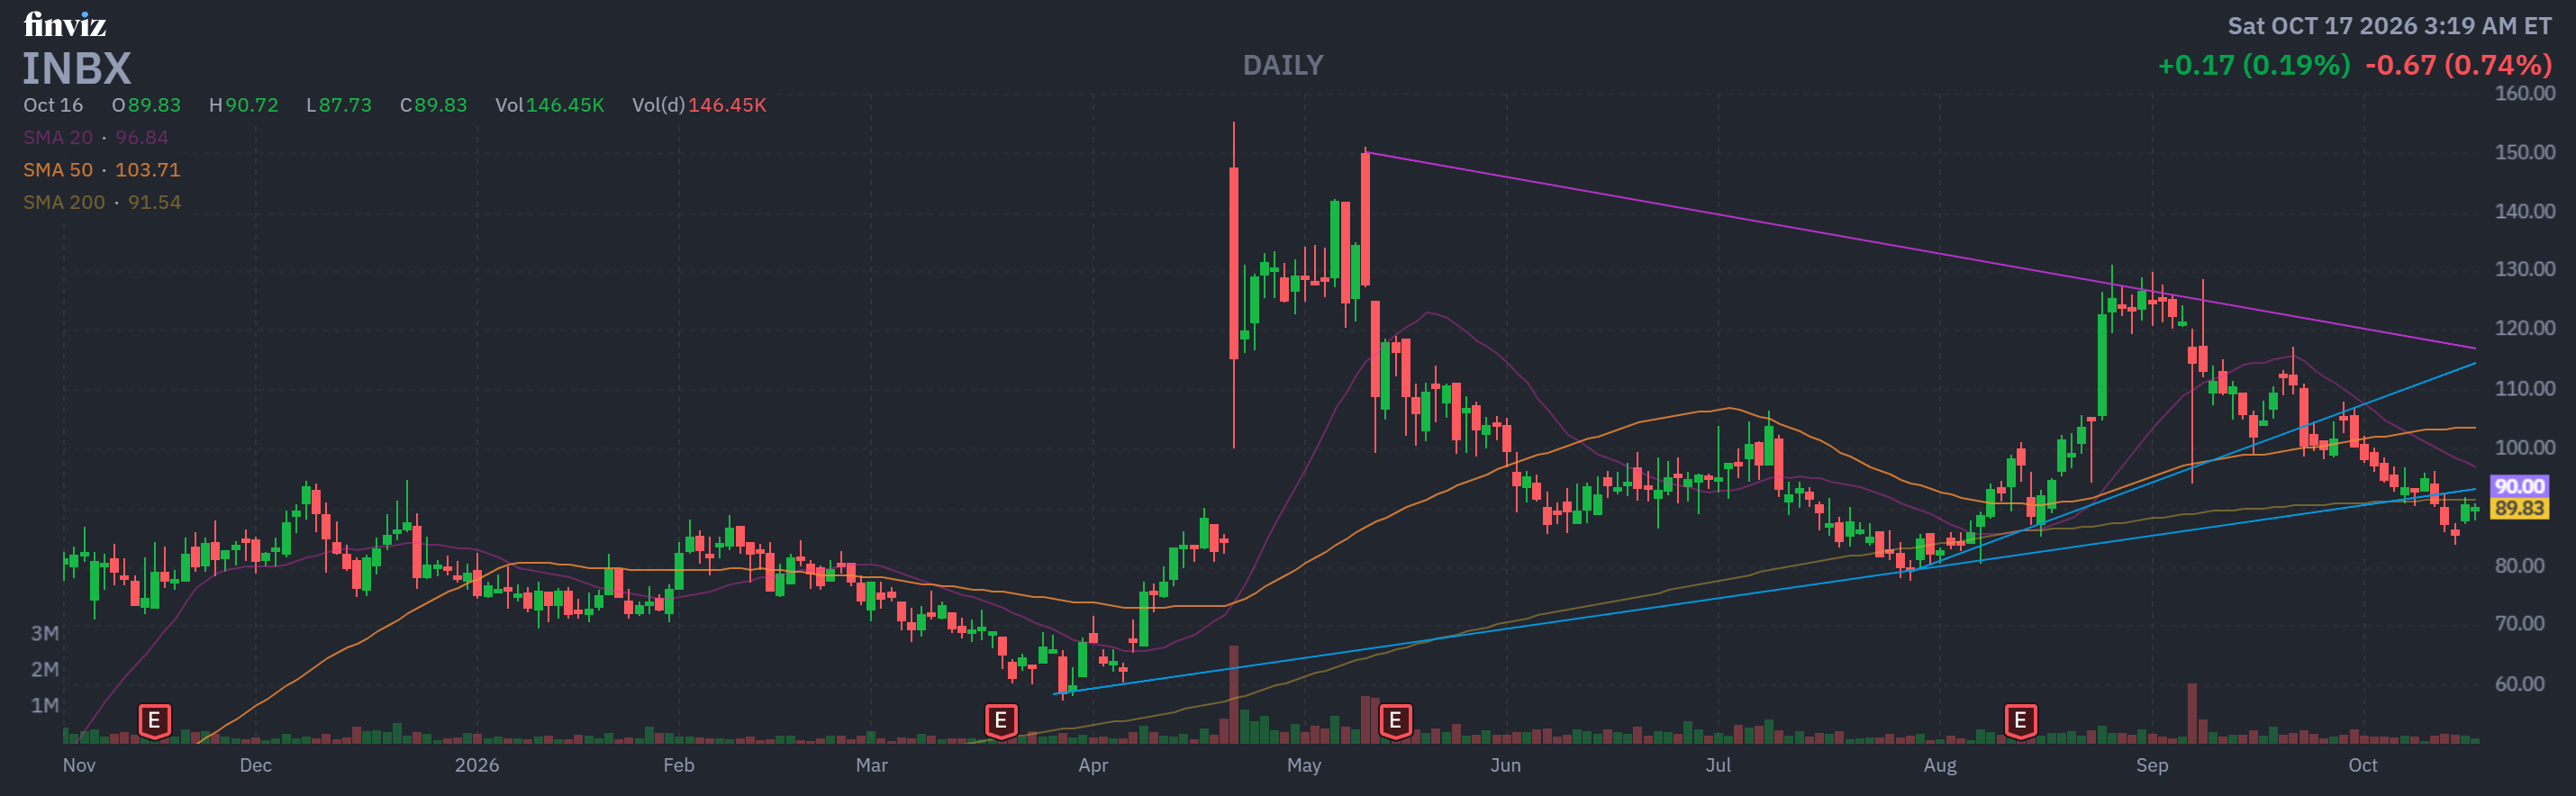
Transaction Date: 10-14-2026 Shares Bought: 10,040 shares an average price paid of $84.56 for Cost: $848,977
Company: Inhibrx Biosciences Inc. (INBX)
Inhibrx Biosciences, Inc. is a clinical-stage biopharmaceutical firm that develops biologic therapies for patients with life-threatening illnesses. INBRX-109, a tetravalent therapeutic candidate targeting death-receptor 5 to treat unresectable or metastatic conventional chondrosarcoma, and INBRX-106, a hexavalent sdAb-based therapeutic candidate targeting OX4 for the treatment of metastatic solid tumor, non-small cell lung cancer, melanoma, head non-small cell lung cancer cell carcinoma, gastric or gastroesophageal junction adenocarcinoma, renal cell carcinoma, Inhibrx Biosciences, Inc. was established in 2024 and is headquartered in La Jolla, California.
Mark P. Lappe is the Founder, CEO, and Chairman of the Board of Inhibrx Biosciences, Inc. He co-founded the company in 2010 and has served as CEO and Chairman of the Board since its start. He remained CEO and Chairman of Inhibrx Biosciences after it became a standalone public company in January 2024, ensuring continuity in the business’s leadership. Prior to creating Inhibrx, Lappe was the Founder and Managing Partner of Efficacy Biotech Fund, and he has over 30 years of experience in biotechnology, investment management, and executive recruitment.
Insomniac Hedge Fund Guy Opinion: The fundamentals are a mess by design, this is a cash-burning clinical biotech with no revenue, but the setup is genuinely compelling: FDA has accepted the BLA, Phase 2 data for the second asset just came in strong, insiders are buying aggressively with their own cash, and nearly a third of the float is sold short against all of that. The Perfect 10 composite reads +4.8 (constructive, on the -10 to +10 scale), with bullish reads on the chart, analyst sentiment, insider activity, sector outlook, and catalysts, offset mainly by the (expected) negative cash flow. On the numbers, the case leans bullish for investors who can stomach binary clinical-and-regulatory risk and a volatile, heavily-shorted name, but this is a high-conviction speculative bet, not a core holding, and the April 2027 PDUFA date is the single event that decides whether this thing runs or craters.
That call on sizing or whether it fits a portfolio is one to make with a financial advisor, not off a single report. And given the short interest and binary catalysts, this is textbook earnings-volatility territory: wild percentage swings tend to cluster around events like these, worth keeping an EVS (earnings volatility strategy) approach in mind if trading around the date rather than just holding through it.
Name: Ryan Cohen
Position: President, CEO, and Chairman
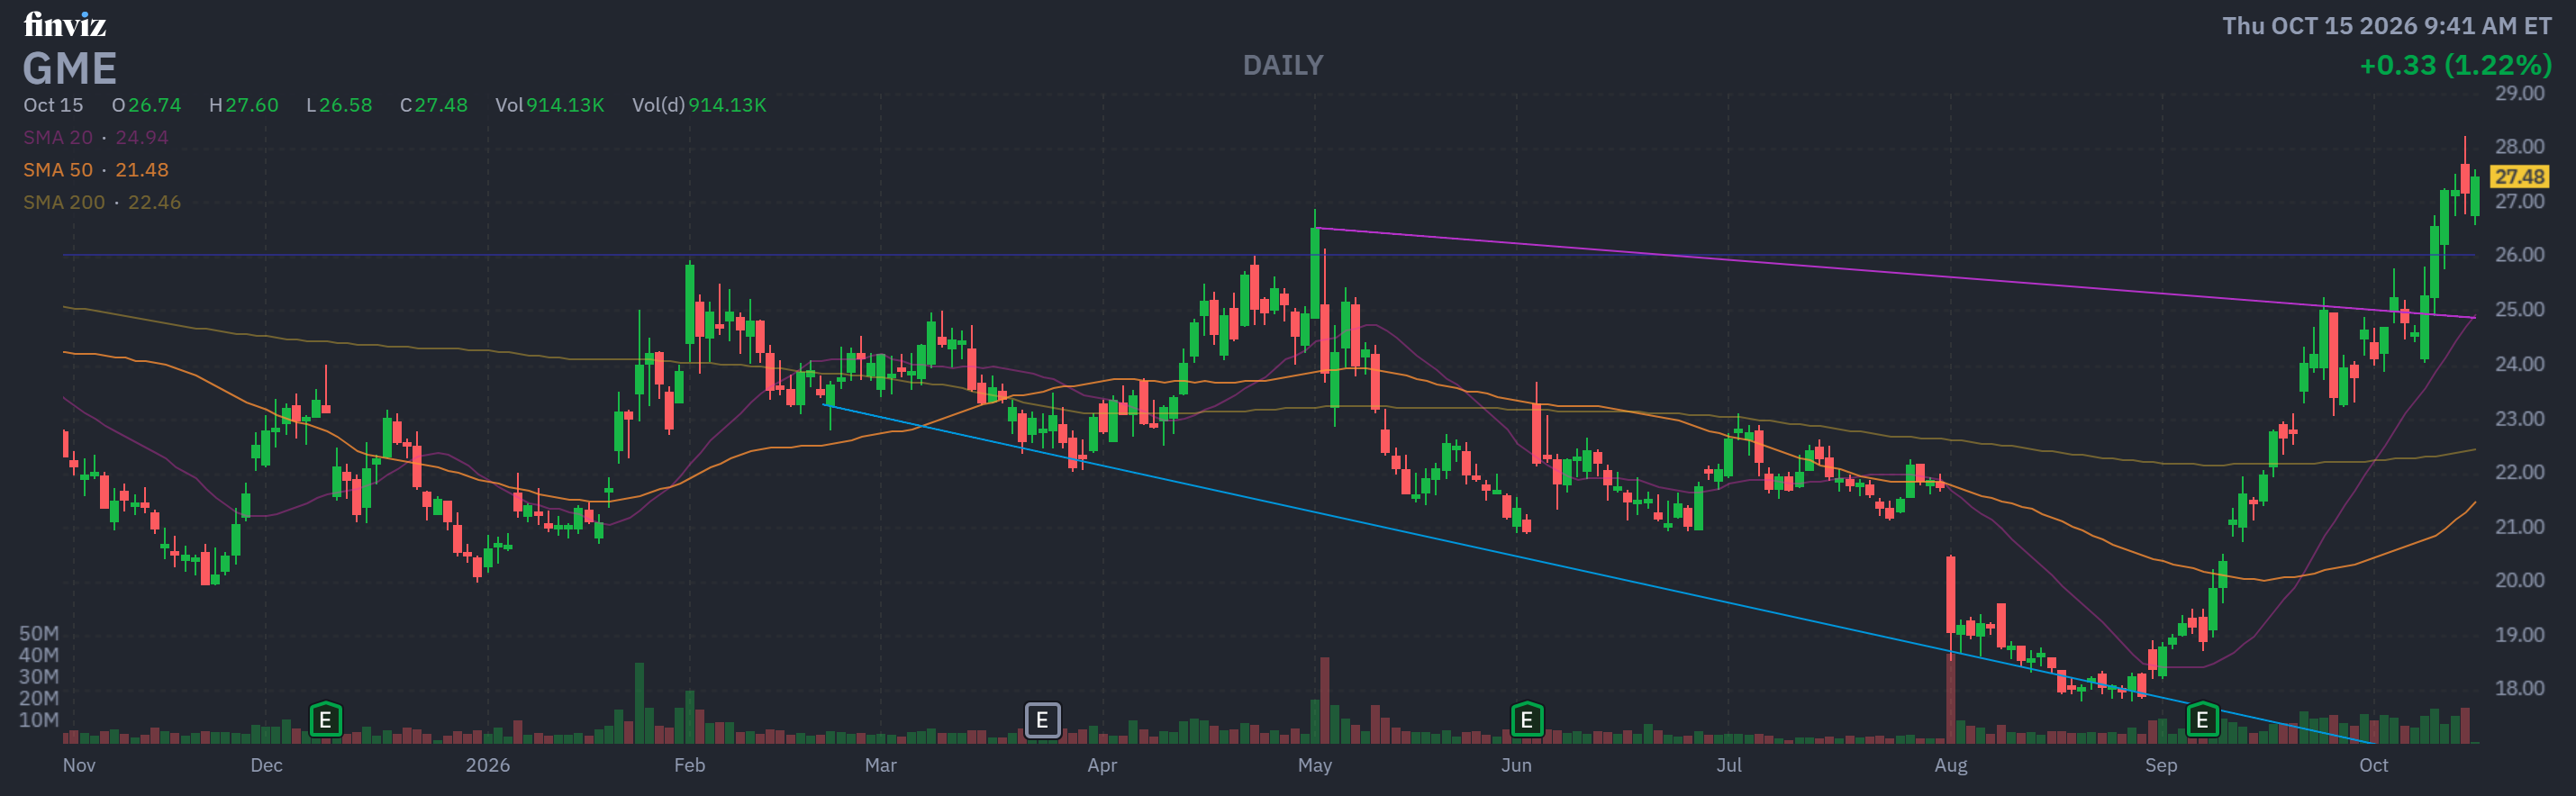
Transaction Date: 10-13-2026 Shares Bought: 844,130 shares an average price paid of $26.98 for Cost: $22,774,728
Company: GameStop Corp. (GME)
GameStop Corp. is a specialty retailer that sells games, collectibles, and entertainment products through physical stores and e-commerce platforms in the United States, Australia, and Europe. The company provides new and pre-owned gaming platforms; accessories such as controllers, gaming headsets, and other peripheral devices; new and pre-owned gaming software; and in-game digital currency, digital downloadable content, and full-game downloads. It also sells memorabilia such as clothing, toys, trading cards, gadgets, and other retail items for pop culture and technology fans. GameStop Corp., formerly GSC Holdings Corp., was formed in 1996 and is headquartered in Grapevine, Texas.
Ryan Cohen has served as President, CEO, and Chairman of the Board of GameStop Corp. He joined GameStop’s Board of Directors in January 2021 and was appointed Executive Chairman in June 2023. He was appointed President and CEO of the company in September 2023, with immediate effect, and he continues to occupy these positions. Cohen is Chewy’s co-founder and former CEO, with substantial experience in e-commerce, technology, consumer enterprises, and capital allocation. He attended McMaster University but did not complete his degree.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite reads +2.5, a Constructive (modestly bullish) score, with bullish insider activity, bullish cash flow quality, and a bullish PEG ratio offset by a bearish sector outlook and neutral valuation. This isn’t a retail turnaround story, it’s a capital-allocation bet on Ryan Cohen with a video game store attached. The insider buying is the strongest signal in this entire report: $98.8 million in purchases, zero sales, in 90 days. That’s conviction money, not a press release.
My lean: cautiously bullish as a speculative, event-driven name, not as a steady compounder. The retail business is still dying, the valuation already prices in most of the cash hoard, and the sector backdrop is working against it. But when the person running the company is buying tens of millions of dollars of stock with his own money while the retail story limps along, that’s a signal worth respecting more than the quarterly comps. Anyone considering a position should treat this as a volatile, thesis-driven trade on management, not a boring buy-and-hold, and that call is yours to make with your advisor.
Given the elevated options activity and the December 8 earnings date on the calendar, this is also a textbook candidate for an earnings volatility play, big percentage moves tend to show up around print day for names like this. Happy to walk through that setup if useful.
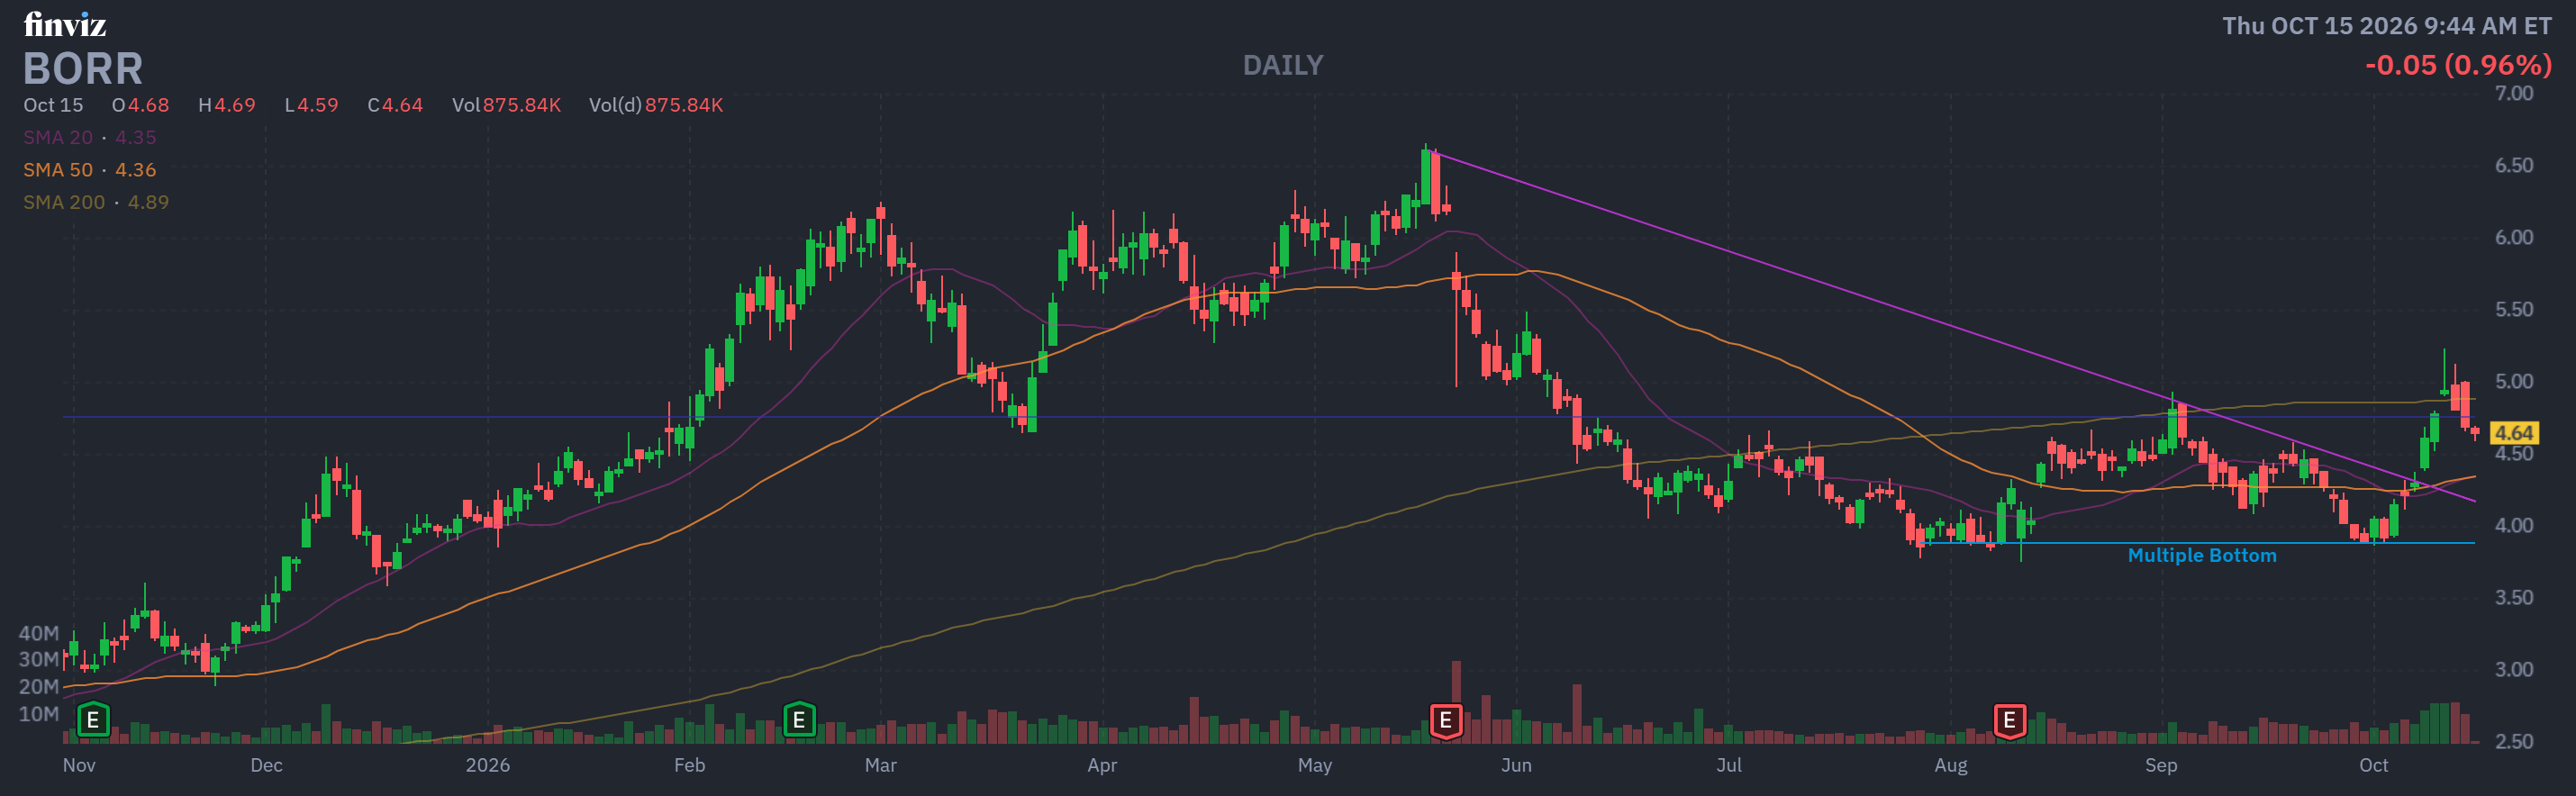
Name: Tor Olav Troim
Position: Director
Transaction Date: 10-12-2026 Shares Bought: 2,500,000 shares an average price paid of $4.74 for Cost: $11,843,500
Company: Borr Drilling Ltd. (BORR)
Borr Drilling Limited provides offshore shallow-water drilling services to the oil and gas industries in the Americas, Southeast Asia, West Africa, the Middle East, North Africa, and Europe. It owns, contracts, and operates jack-up rigs for shallow-water operations, as well as providing related equipment and work crews for oil and gas drilling and workover activities in exploration and production. It caters to oil and gas exploration and production companies, including integrated oil companies, state-owned national oil enterprises, and independent oil and gas producers. The company was previously known as Magni Drilling Limited before changing its name to Borr Drilling Limited in December 2016. Borr Drilling Limited was established in 2016 and is headquartered in Hamilton, Bermuda.
Tor Olav Troim has served as a Director of Borr Drilling Ltd. since the company’s incorporation in 2016 and was one of its founders. He has also served as Chairman of the Board from August 2017 to September 2019 and again from February 2022 to September 2025. Troim has more than 30 years of experience in the energy and offshore drilling industries, having previously held senior leadership positions, including CEO of Seadrill Ltd., Frontline Ltd., Golar LNG Partners LP, and DNO AS. He is also the founder of Magni Partners and serves on the boards of several international companies. He earned a Master of Science degree in Naval Architecture from the University of Trondheim, Norway.
Insomniac Hedge Fund Guy Opinion: The Perfect 10 composite score lands at +3.9 (constructive), a sum built on bullish analyst sentiment, bullish insider activity, bullish cash flow and a bullish sector tailwind, offset by bearish short-term chart momentum and a neutral valuation picture. On the numbers, this one leans bullish: a chairman buying tens of millions of dollars of stock with his own money, backlog stretching into 2027, cash flow quality that’s actually improving, and a DCF that suggests the market hasn’t fully priced the recovery. The debt load and rich trailing P/E are real risks, and the double-digit short interest means this isn’t a stock without a fight attached to it. This is a name for investors comfortable with offshore drilling cyclicality and leverage, not a sleep-well-at-night holding. That decision, and position sizing, is yours to make with your advisor.
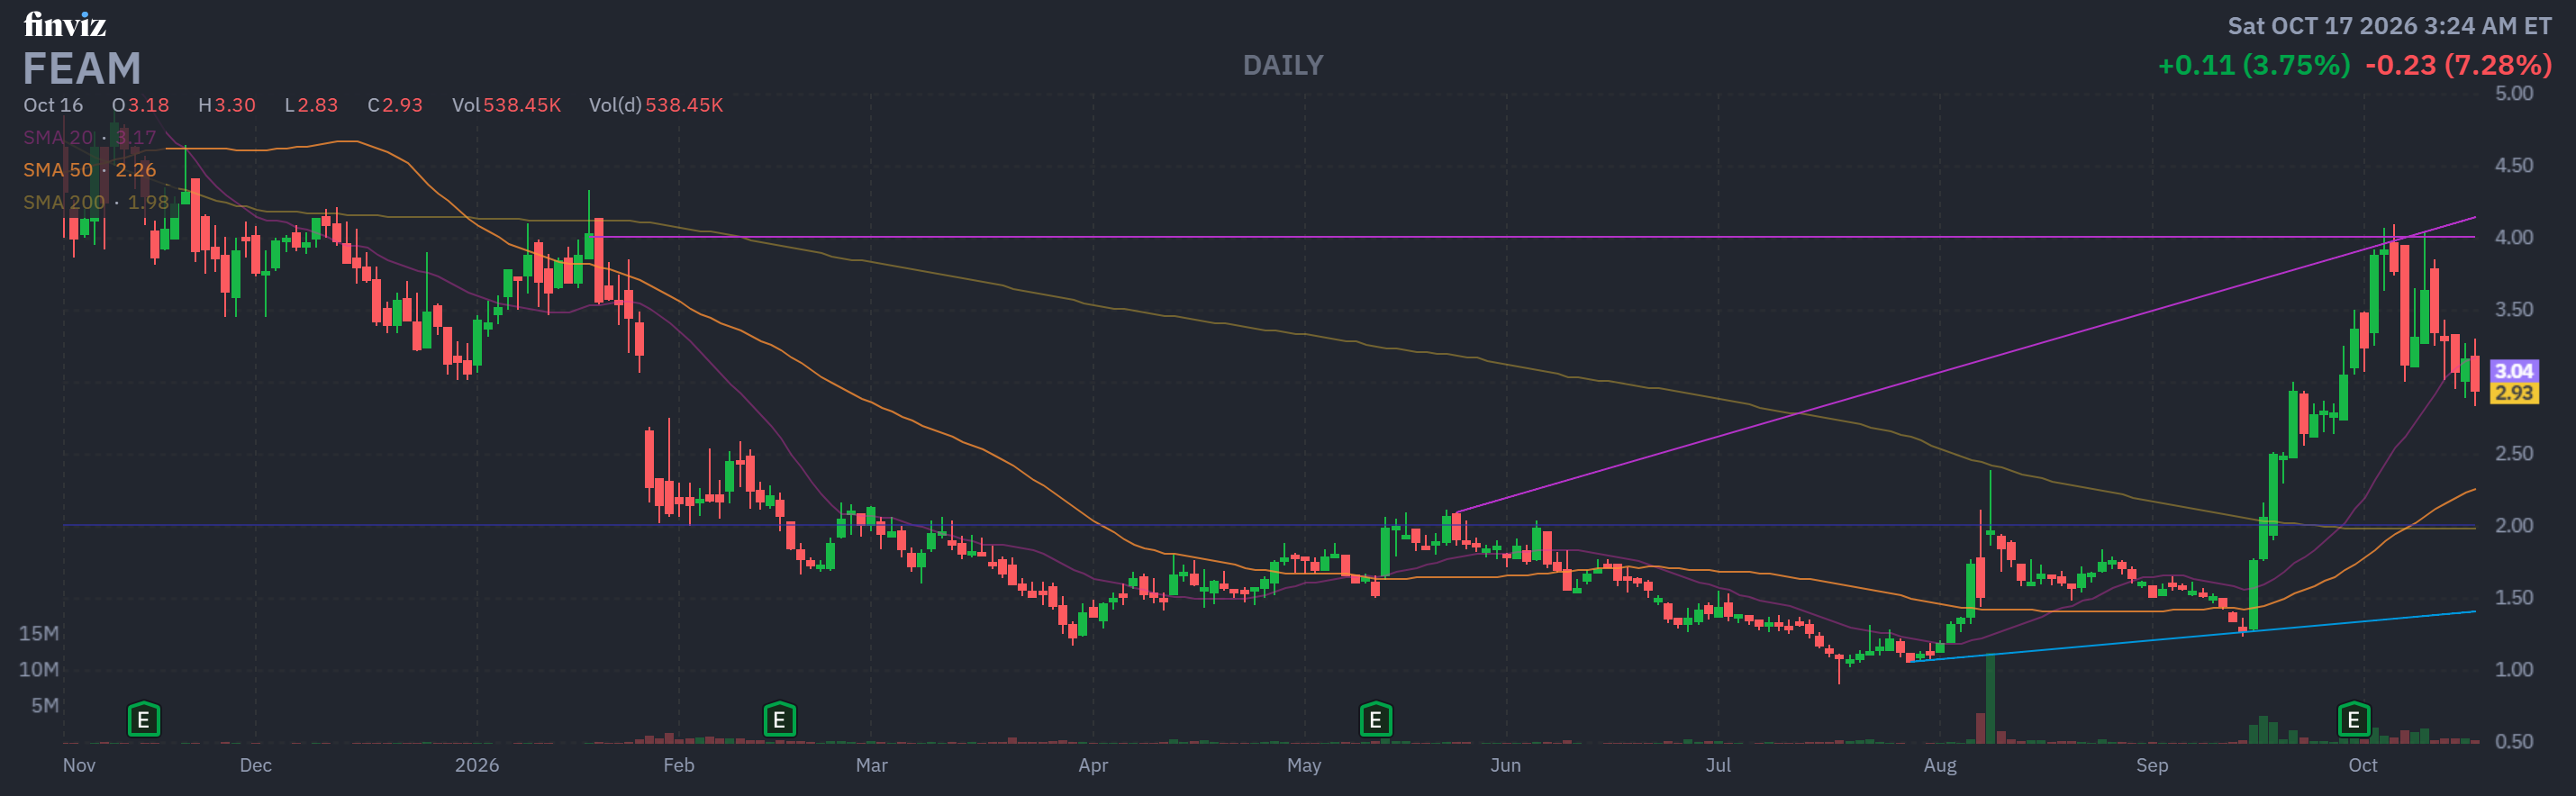
Name: Graham Van’t Hoff
Position: Director
Transaction Date: 10-08-2026 Shares Bought: 60,000 shares an average price paid of $3.59 for Cost: $215,400
Company: 5E Advanced Materials Inc. (FEAM)
5E Advanced Materials, Inc. is an exploration-stage company engaged in the exploration and development of mineral properties in the United States. The company focuses on borates and lithium deposits, which are used in various industrial and advanced technology applications. It holds a 100% interest in the Fort Cady project, located in the Mojave Desert region of eastern San Bernardino County, California. The company was formerly known as American Pacific Borates Limited before changing its name to 5E Advanced Materials, Inc. 5E Advanced Materials, Inc. was incorporated in 2021 and is based in Hesperia, California.
Graham van’t Hoff has served as a Director of 5E Advanced Materials, Inc. since October 2022, when he joined the company’s Board of Directors as a Non-Executive Director. He was appointed Chairman of the Board in 2026. He previously spent approximately 35 years at Royal Dutch Shell, where he served as Executive Vice President of Global Chemicals, Chairman of Shell UK, and Executive Vice President of Alternative Energies and CO₂. He brings extensive experience in global chemicals, energy, business restructuring, and corporate leadership. He holds a Bachelor of Arts and a Master of Chemistry from the University of Oxford, as well as an MBA with distinction from Alliance Manchester Business School.
Insomniac Hedge Fund Guy Opinion: FEAM just went from a speculative boron dream to an actual, revenue-producing operation in the span of weeks, and that changes the entire conversation. The Perfect 10 composite score lands at +0.6 (mixed/neutral on the -10 to +10 scale), reflecting a genuine tug-of-war: bullish analyst coverage and insider buying on one side, a going-concern warning and negative cash flow on the other. This is a show-me story now, not a buy-the-story story. The DCF above suggests modest upside from today’s price if management hits its EBITDA target, but the going-concern language means the downside case is real too. This one belongs on the watchlist for the next two quarters of integration results, not in a portfolio on faith alone.
This blog is solely for educational purposes and the author’s own amusement. IT IS NOT INVESTMENT ADVICE. Think of the blog as part of my personal investment journal that I am willing to share with the DIY investor. We could be long, short, or have no position at all in any of the stocks mentioned and express no written or implied obligation to disclose any of that. Nothing contained here constitutes a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal, and past performance is not indicative of future results.
“The insomniac hedge fund guy” is a moniker Harvey Sax, the portfolio manager for The Insiders Fund” has used from time to time on email, blog ,and social media posts. While Mr. Sax is the portfolio manager of The Insiders Fund, these posts are not communications from, nor endorsed by, Alpha Wealth Funds, LLC or any of its managed funds. References to Alpha Wealth Funds or its affiliates are for identification only and do not imply sponsorship or approval.
All company names, logos, and trademarks belong to their respective owners. The use of company logos is solely for descriptive and illustrative purposes under fair use. Any information provided is based on publicly available data and should not be considered financial, investment, or legal advice. Readers should conduct their own research or consult with a professional before making any investment decisions. Insiders sell the stock for many reasons, but they generally buy for just one – to make money. You’ve always heard the best information is inside information. Everyone with any stock market experience pays close attention to what insiders are doing. After all, who knows a business better than the people running it? Officers, directors, and 10% owners are required to inform the public through a Form 4 Filing of any transaction, buy, sell, exercise, or any other within 48 hours of doing so.
This info is available for free from the SEC’s Web site, Edgar, although we subscribe to SECForm4 as they provide a way to manage and make sense of the vast realms of data. I’ve tried a lot of vendors. SECForm4 is one of the smaller ones, but I like supporting Frank. He is not arrogant. He’s helpful and has great prices. He also trades on his own data, so I like people that eat what they kill. The bar is different from selling because the natural state of management is to be a seller. This is because most companies provide significant amounts of management compensation packages as stock and options. Therefore, we analyze unusual patterns with selling, such as insiders selling 25 percent or more of their holdings or multiple insiders selling near 52-week lows. Another red flag is large planned sale programs that start without warning. Unfortunately, the public information disclosure requirements about these programs, referred to as Rule 10b5-1, are horrendously poor. Also, planned sales that pop up out of nowhere are basically sales and are seeking cover under this corporate welfare loophole.
I also generally ignore 10 percent shareholders as they tend to be OPM (other people’s money) and perhaps not the smart money on which we are trying to read the tea leaves. I say generally because some 10% shareholders are great investor, think Warren Buffett and others. Of course, insiders can also be wrong about their Company’s prospects. Don’t let anyone fool you into believing they never make mistakes. Do your own analysis. They can easily be wrong, and in many cases, maybe most cases, have no more idea what the future may hold than you or me. In short, you can lose money following them. We have, and we curse aloud; what were they thinking!
We like Fly on the Wall for keeping up with what events might be happening, analysts’ comments, and whatever else could be moving the stock. Dow Jones news service is an essential tool, but many services pick up their feed like they do Bloomberg. My assistant probes the 10k for a reasonable description of the business. I’ve found that to be the most accurate and succinct place to find out what a business actually does.
For more, please visit out website at https://insomniachedge.com/